
| Visit TheInvestorCall.com → |
01 / THE ESSENTIAL ECONOMY / OCTOBER 21, 2026 THE BREAD AND BUTTER |  |
The businesses that keep the economy running are delivering growth. Are investors giving them enough attention?
MATERIALS / MACHINERY / POWER / AUTOMATION / SERVICES
Before the opening bell, an excavator is already moving earth. A factory is drawing electricity. Building controls are adjusting airflow, production lines are consuming materials, and collection trucks are clearing yesterday’s waste. The market has not opened. The economy has.
These everyday activities support businesses whose growth is easy to overlook. Familiarity can make an enterprise feel fully understood. Its earnings, order book and cash generation may tell a more interesting story.
Yesterday, 3M reported higher adjusted earnings and raised its annual profit outlook. That is today’s starting point. We then examine the latest published results from Caterpillar, Eaton, Honeywell Technologies and Waste Management.
Our research question: which companies are improving profitability, which are expanding demand, and which are turning essential services into stronger cash flow? Each path deserves its own explanation.
| MMM | CAT | ETN | HON | WM |
THE MARKET HAS NOT OPENED.
THE ECONOMY HAS.
Research as of October 21, 2026. 3M: Q3 2026; other company results: Q2 2026. All dollar figures are U.S. dollars. Company reporting is distinguished from our editorial interpretation.
02 / 3M / NYSE: MMM A FAMILIAR NAME. |  |
The improvement is visible in the relationship between sales, margins and earnings per share.
$6.6B Q3 2026 REPORTED SALES 3M | 26.2% ADJUSTED OPERATING MARGIN Company-defined non-GAAP | $2.50 ADJUSTED EPS +12% year over year |
What changed inside?
3M sells materials and products across industrial safety, transportation, electronics and consumer markets. Its filing identifies manufacturing productivity, procurement savings and pricing among the factors helping offset cost pressures.
Its adjusted operating margin rose from 25.1% to 26.2%. A wider margin means more operating profit per sales dollar. Diluted weighted-average shares fell from 538.1 million to 522.6 million, also supporting per-share results.
Read the comparison carefully.
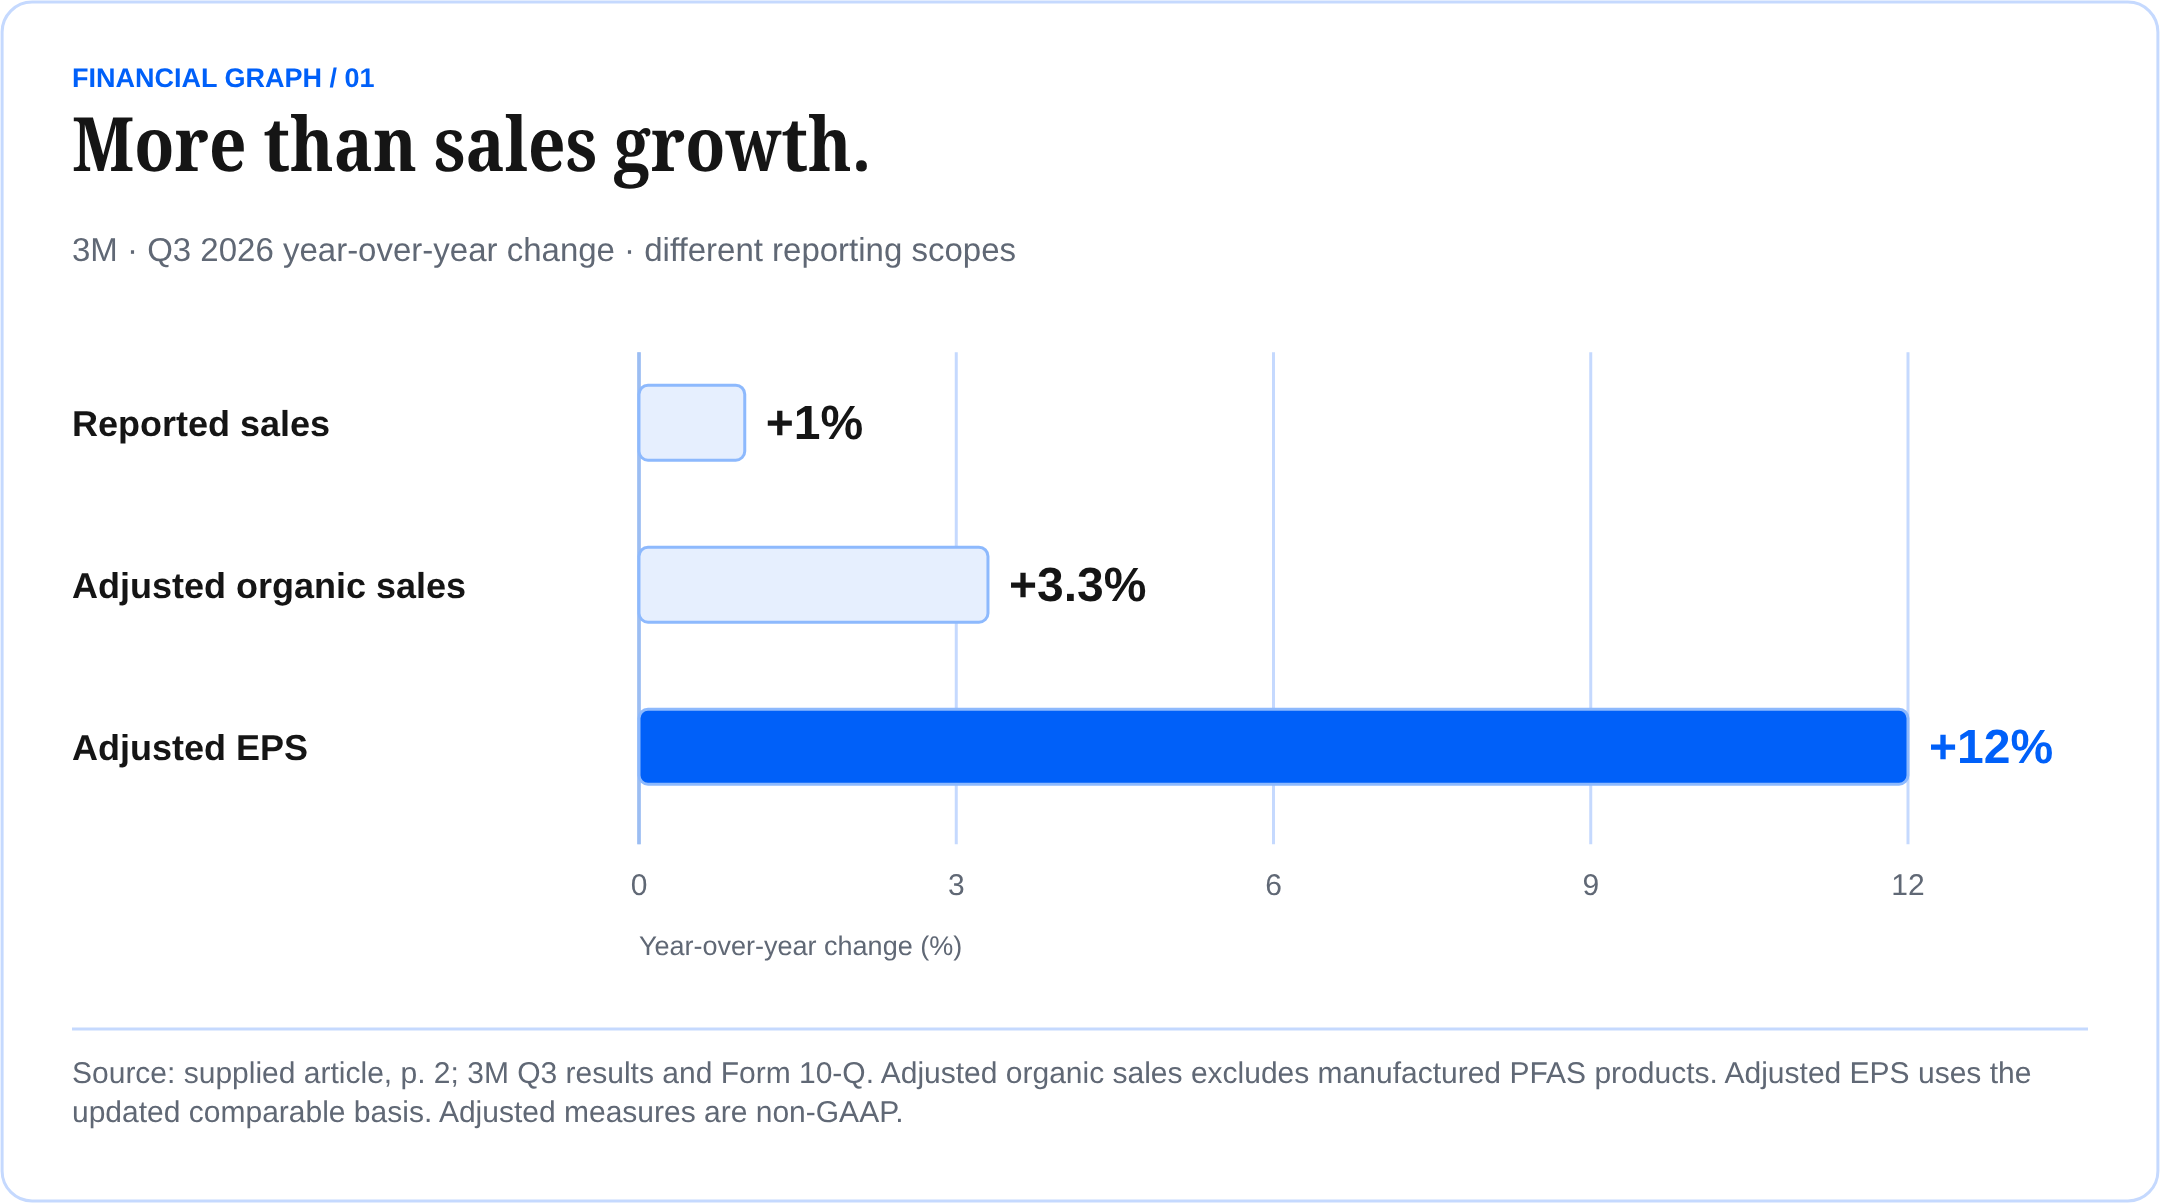
Reported sales grew 1%; adjusted organic sales grew 3.3%. These measures have different scopes. 3M also revised adjusted reporting to exclude intangible amortization, applying the change to comparative periods.
Full-year adjusted EPS guidance is now $9.10–$9.15, incorporating performance, an acquisition and the reporting change. Our interpretation: improving operations and fewer shares both matter. The headline alone cannot explain the increase.
KEEP THE UNITS STRAIGHT
Margin increased 1.1 percentage points; it did not rise 1.1%.
Common scale in the graph: 0% to 12%. Adjusted organic sales excludes manufactured PFAS products; adjusted EPS uses 3M’s updated comparable basis. Adjusted figures are company-defined non-GAAP measures. EPS means earnings per share. Margin increased 1.1 percentage points; it did not rise 1.1%. Guidance is a management forecast.
03 / CATERPILLAR / NYSE: CAT WHEN CUSTOMERS BUY |  |
Caterpillar’s second quarter offers something tangible: a large increase in equipment sales volume.
$20.54B Q2 2026 REVENUE +24% year over year | $8.17 ADJUSTED EPS vs. $4.72 | 21.9% ADJUSTED OPERATING MARGIN vs. 17.6% a year earlier |
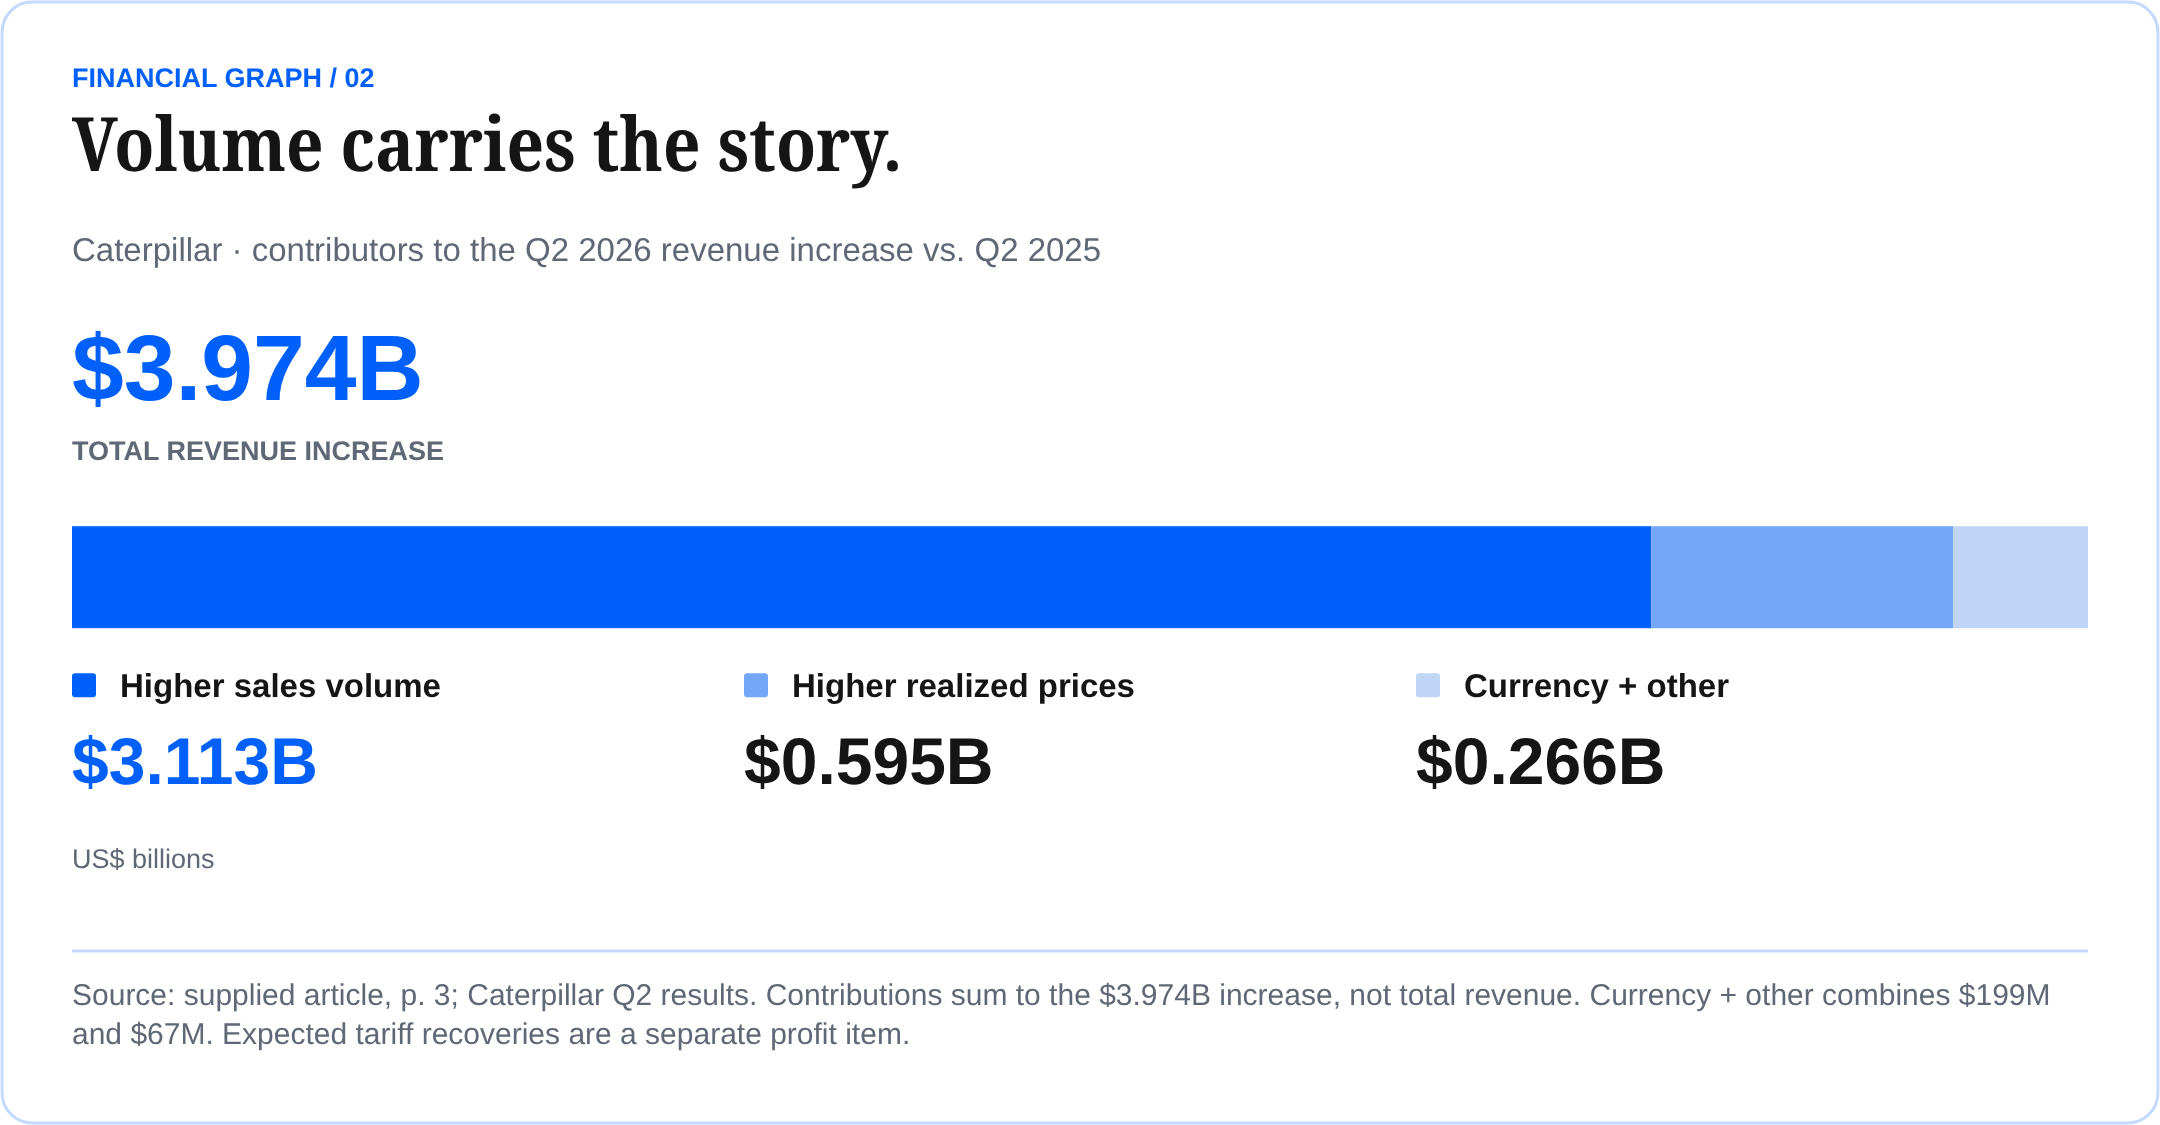
Volume carries the story.
Caterpillar supplies construction and mining equipment, engines, turbines and related services. When customers invest in projects and operating capacity, equipment demand can translate into revenue and a larger installed base to support.
Revenue increased by $3.974 billion. Higher sales volume contributed $3.113 billion; better prices added $595 million. The release attributes the volume increase mainly to higher equipment sales to end users.
Growth with greater scale.
Segment sales rose 35% in Construction Industries, 20% in Resource Industries and 17% in Power & Energy. Adjusted operating margin reached 21.9%, versus 17.6% a year earlier.
Operating profit also included $392 million of expected tariff recoveries. Our reading: demand strengthened, but that benefit should be separated when judging repeatable profitability. Watch the October 29 results for the next test of momentum.
VOLUME CARRIES THE STORY.
Q2 2026 results were released August 4. Revenue bridge totals $3.974B; currency and other combine $199M and $67M. Adjusted EPS and margins exclude restructuring costs.
| Visit TheInvestorCall.com → |
04 / EATON + HONEYWELL / ETN + HON POWER THE ECONOMY. |  |
Electricity must reach the equipment. Controls must help that equipment perform. Two businesses expose different parts of the same investment cycle.
ETN / EATON
14% Q2 ORGANIC SALES GROWTH Q2 2026 | 43% ELECTRICAL BACKLOG GROWTH Not recognized revenue |
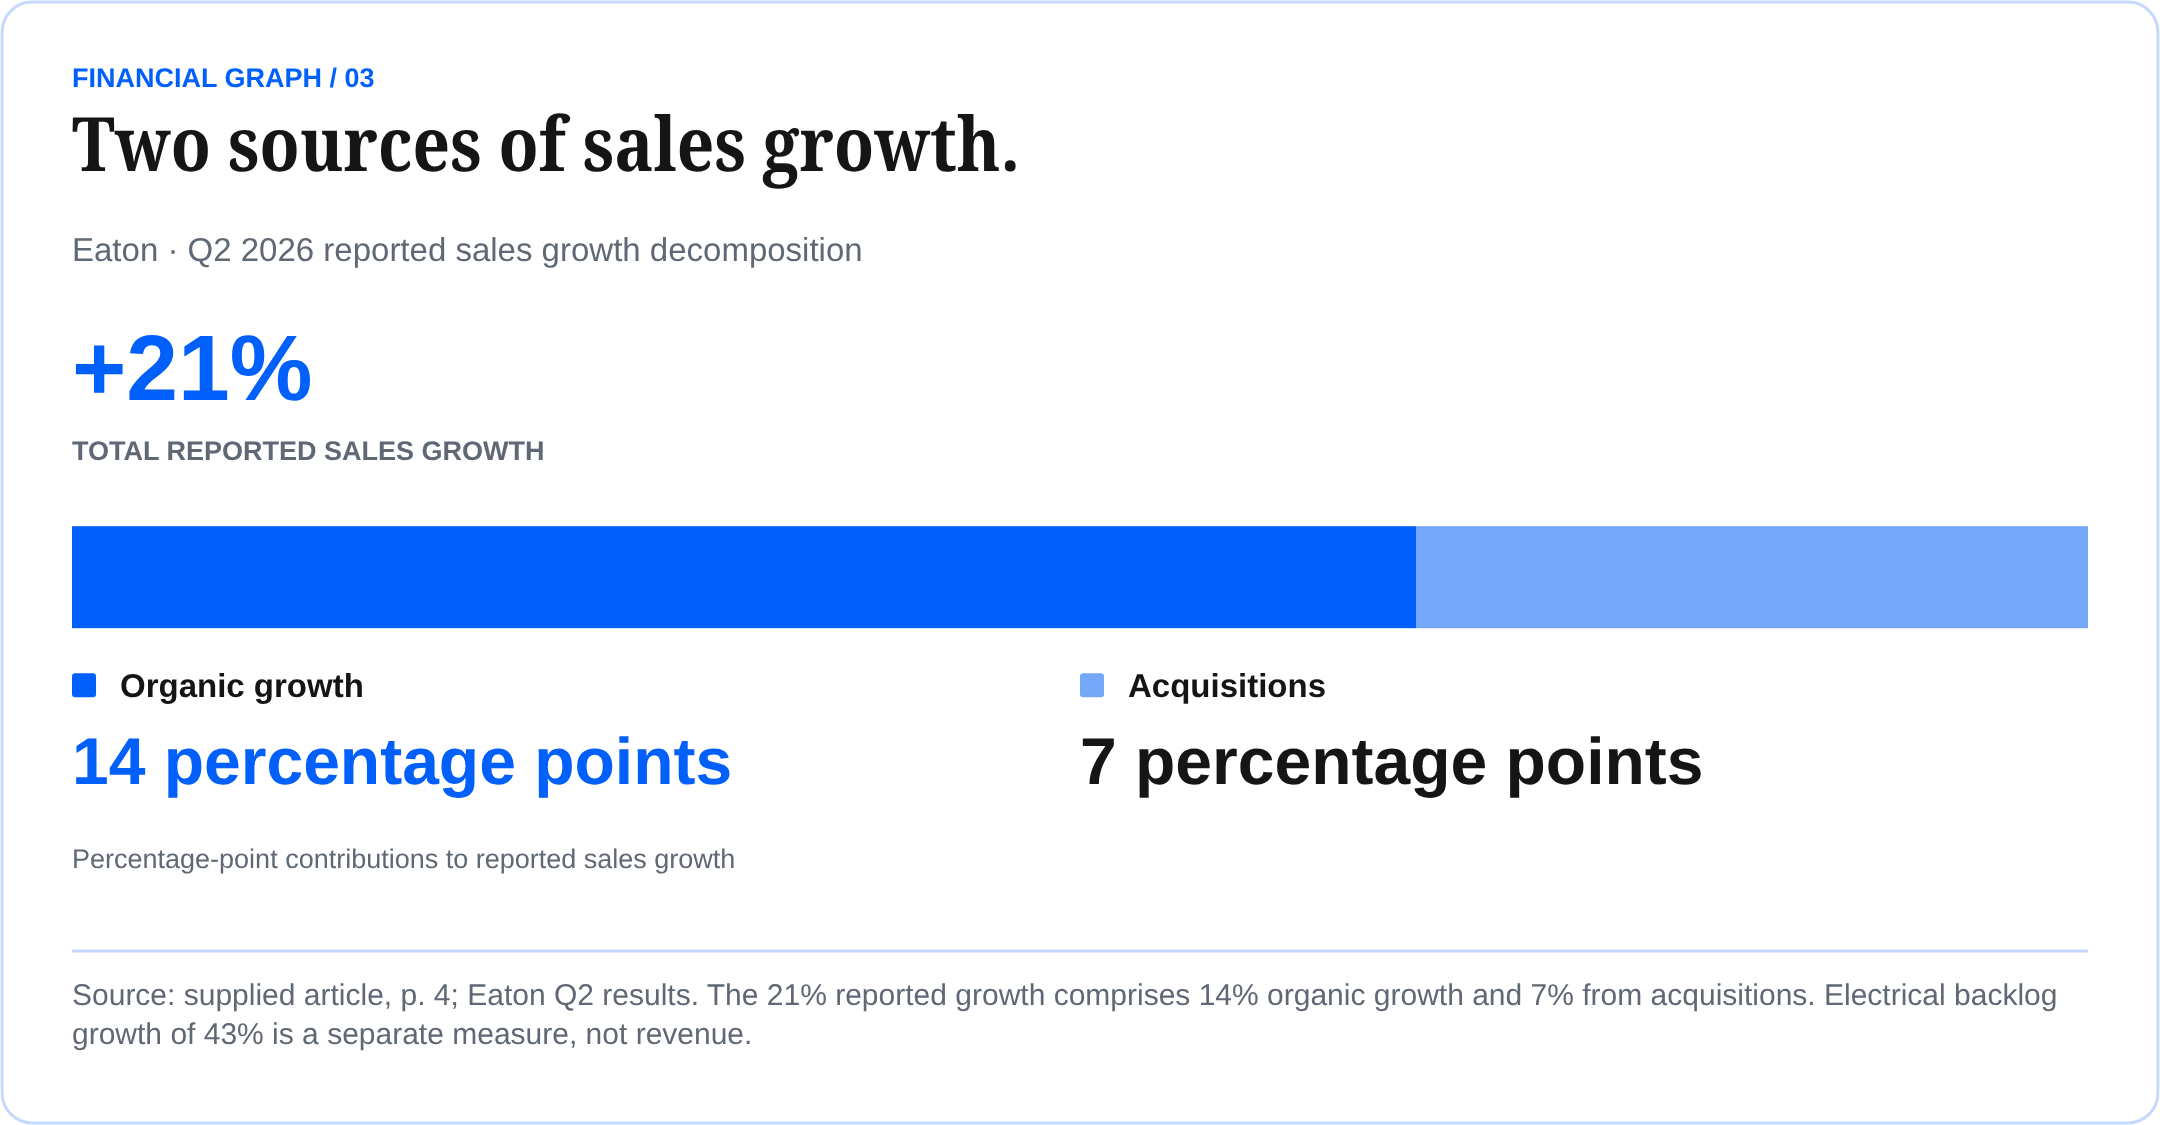
Eaton supplies power-management equipment and systems. Q2 sales reached $8.5 billion, up 21%: 14% organic growth and 7% from acquisitions. Organic growth removes acquisition and currency effects to clarify underlying sales performance.
Electrical backlog grew 43%. That is demand still to be converted into delivered revenue. Management projected full-year organic growth of 11%–13% in its July report. Overall segment margin was 23.1%, down 0.8 percentage points year over year.
Our interpretation: strong demand is established; profitable execution on the backlog is the next question. The next earnings release is scheduled for November 3.
HON / HONEYWELL TECHNOLOGIES
16% Q2 ORDERS GROWTH Excluding Aerospace | $1.95 ADJUSTED EPS +10% year over year |
Honeywell’s automation businesses help control buildings and industrial processes. On a basis excluding the separated Aerospace business, Q2 sales were $5.19 billion: up 3% reported and 4% organically. Adjusted EPS rose 10% to $1.95.
Orders increased 16%. Building Automation grew 9% organically, while Process Automation and Technology declined 1%. The overall picture is improving, with differences between operations. Aerospace now trades separately as HONA.
Our interpretation: an order book can signal opportunity before sales accelerate. Tomorrow’s October 22 earnings are the next test of conversion and margins.
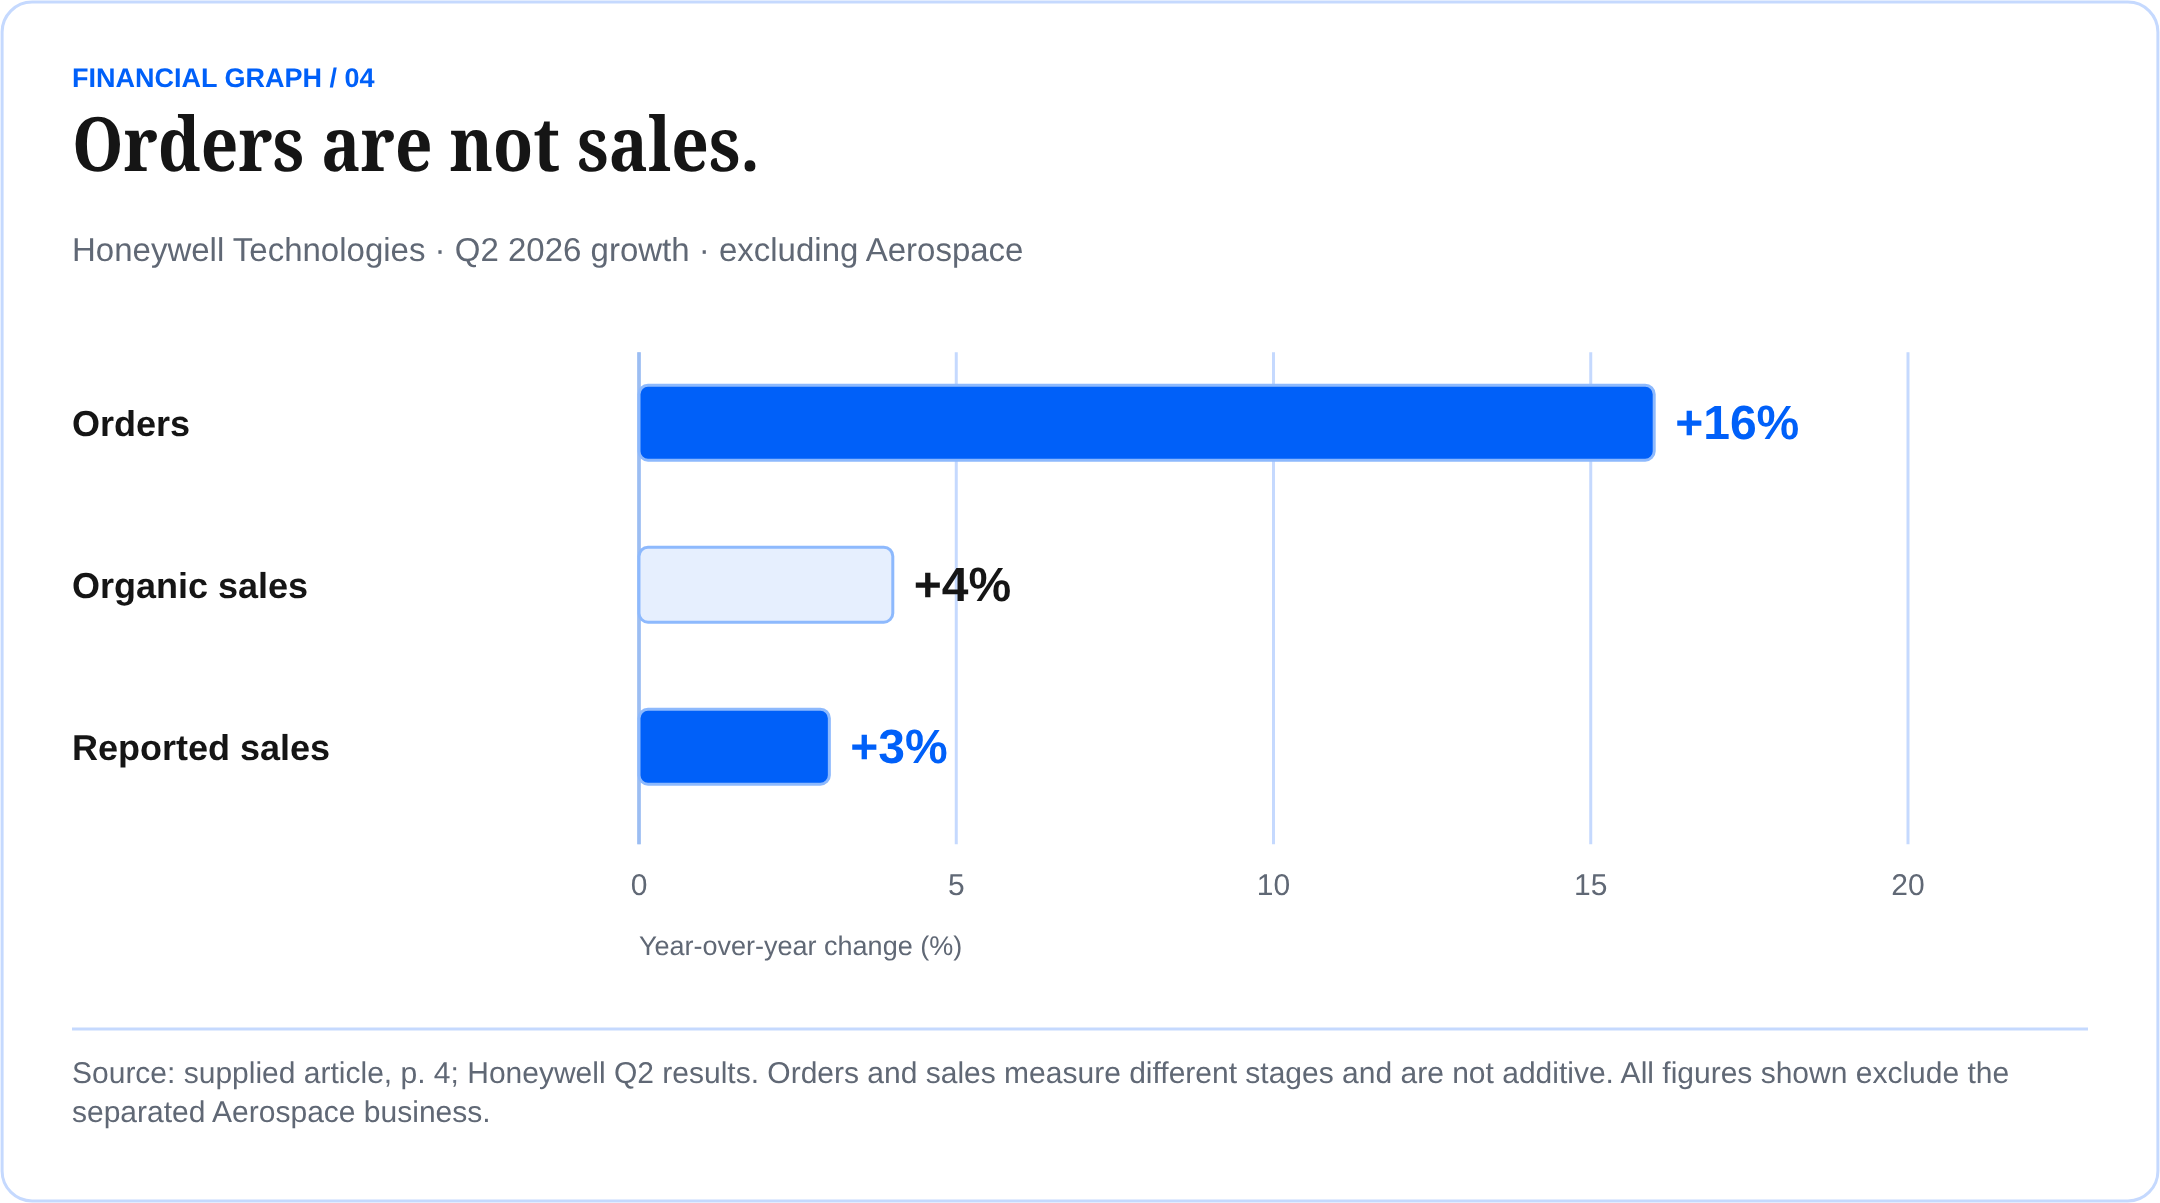
BACKLOG AND ORDERS
ARE NOT RECOGNIZED REVENUE.
Q2 2026 company results. Honeywell figures above exclude Aerospace. Backlog and orders are not recognized revenue. Forecasts reflect management’s published outlook, not achieved results.
Eaton Q2 results · Honeywell Q2 results · HON next report · ETN next report
05 / WASTE MANAGEMENT / NYSE: WM AN EVERYDAY NECESSITY. |  |
Collection routes, disposal infrastructure and operational discipline turn an essential service into a measurable financial story.
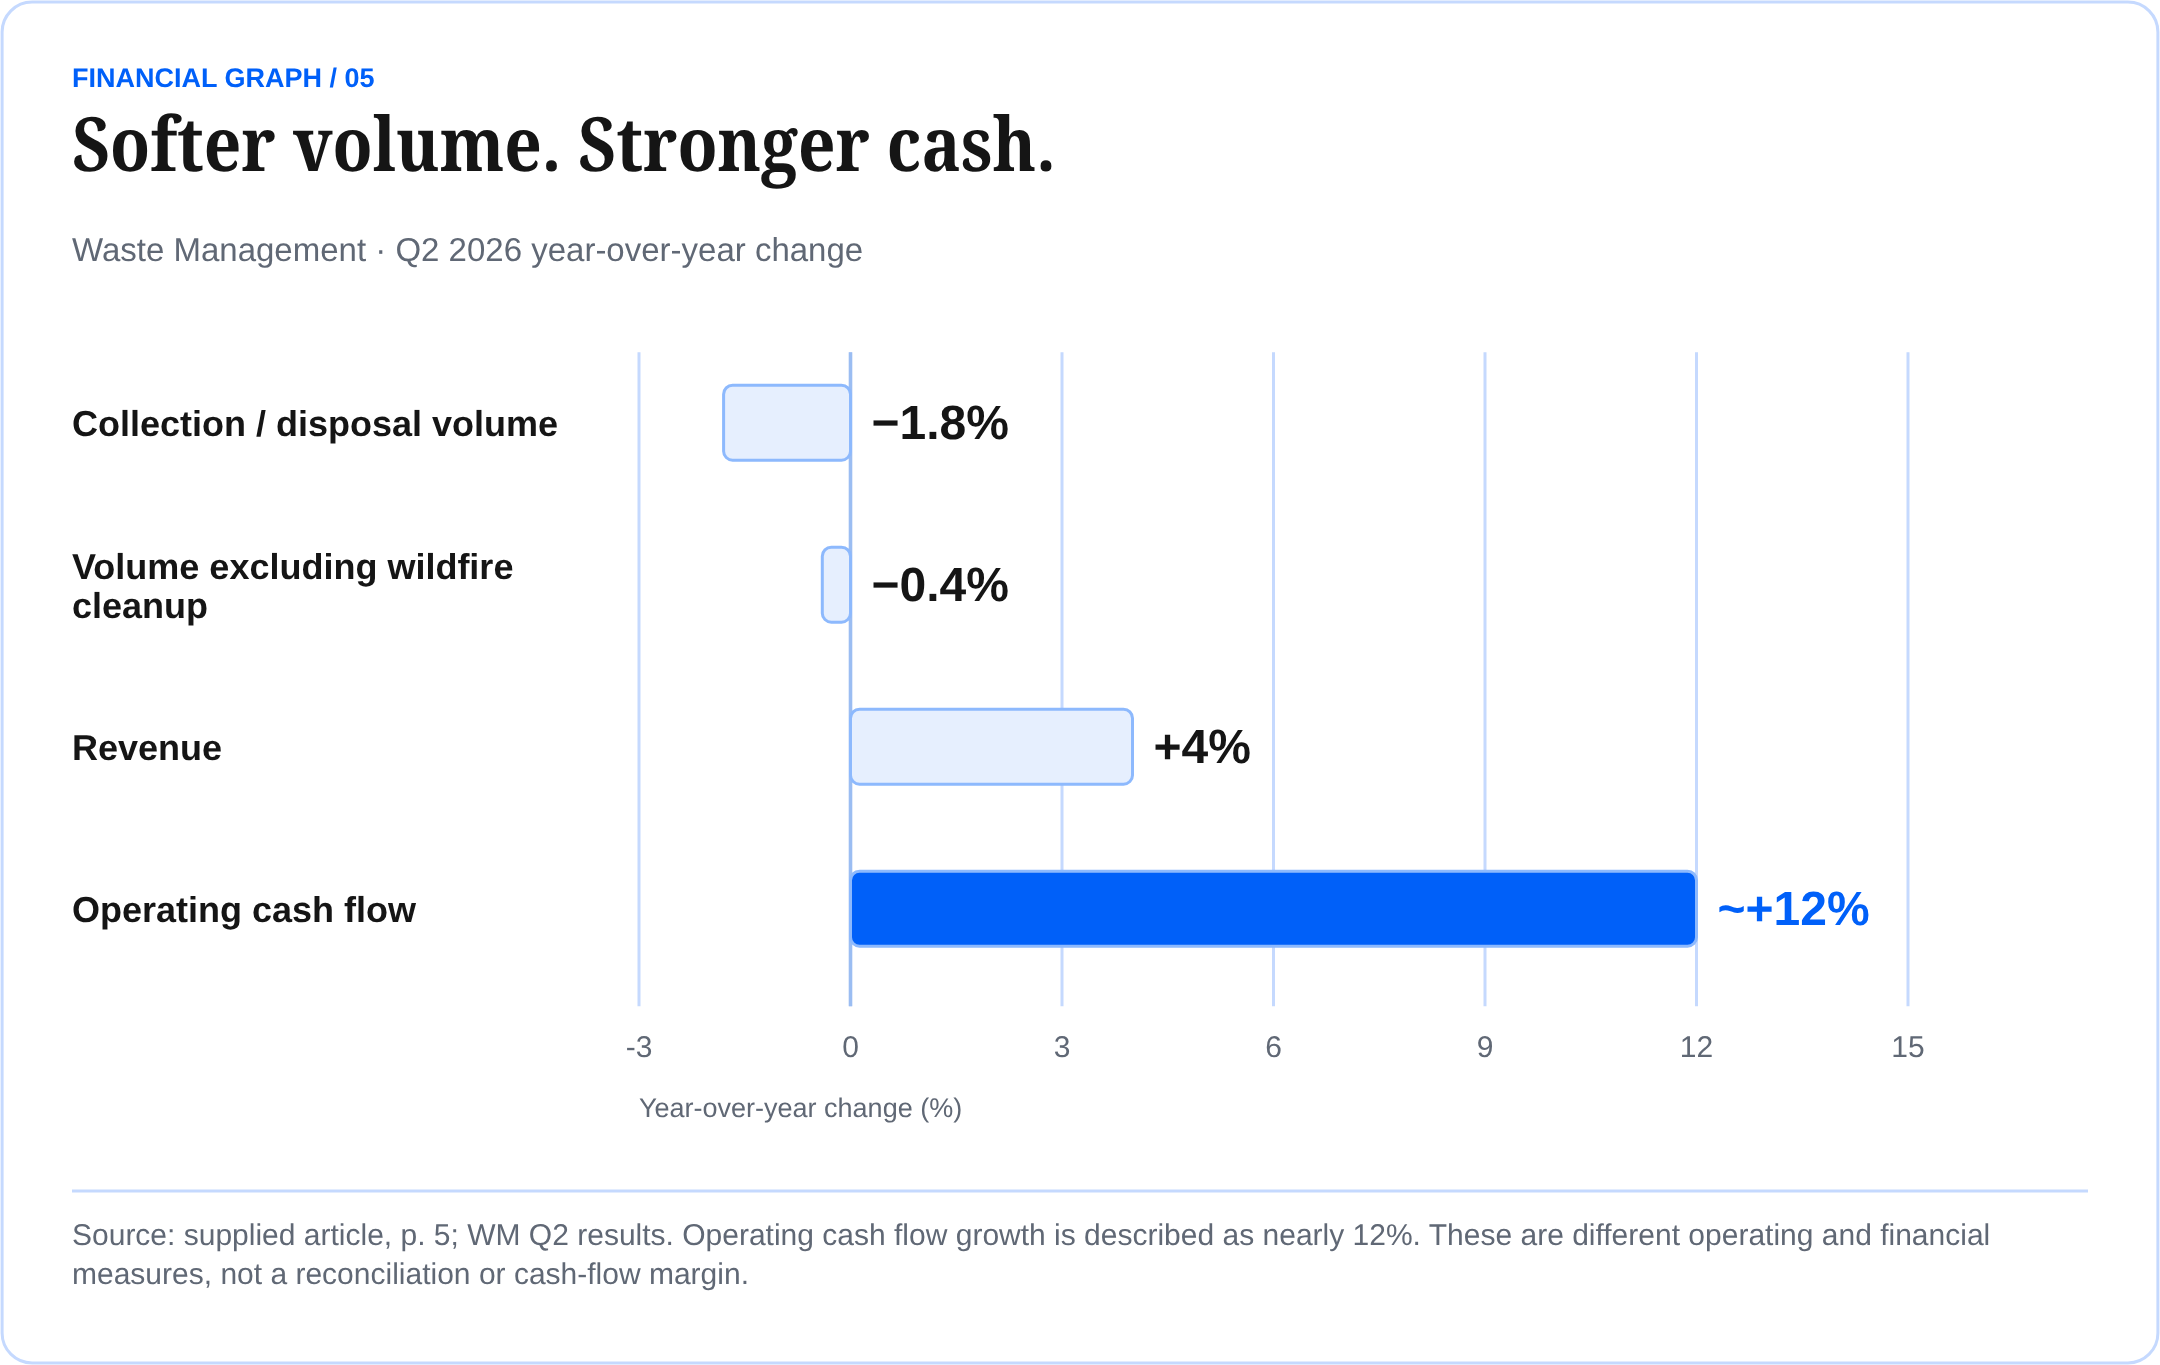
$6.68B Q2 2026 REVENUE +4% year over year | $2.02 ADJUSTED EPS vs. $1.92 | ~12% OPERATING CASH FLOW GROWTH Year over year |
A BUSINESS CAN GROW WITHOUT
MORE COLLECTION VOLUME.
PRICING + EFFICIENCY + INFRASTRUCTURE
The task is to understand which of these forces is driving the result.
The service keeps moving.
WM’s network collects, processes and disposes of waste, with recycling, renewable energy and healthcare services adding to the operating mix. Customers pay for reliable execution of a recurring operational need.
Q2 revenue rose 4% and operating cash flow increased nearly 12%. Collection and disposal volumes declined 1.8%, partly because the prior-year period included wildfire cleanup activity. Excluding that activity, volumes declined 0.4%.
Pricing, new project contributions and efficiency help explain how revenue and cash can improve while collection activity is softer.
Follow the cash.
Adjusted EPS increased from $1.92 to $2.02. Adjusted operating EBITDA margin moved from 30.5% to 30.9%. EBITDA measures earnings before interest, taxes, depreciation and amortization; WM’s operating measure also reflects its stated adjustments.
Our interpretation: the strongest question is whether pricing and operating improvements keep producing cash after the investment needed to maintain and expand the network.
Across this edition, growth takes different forms: better margins at 3M, more equipment sold at Caterpillar, electrical demand at Eaton, automation orders at Honeywell, and cash generation at WM.
Q2 2026 comparisons are year over year. Adjusted EPS and operating EBITDA are non-GAAP measures. Pricing and operational progress should be assessed alongside volumes and capital spending.
06 / THE INVESTOR CALL / RESEARCH BOARD FIVE TICKERS. |  |
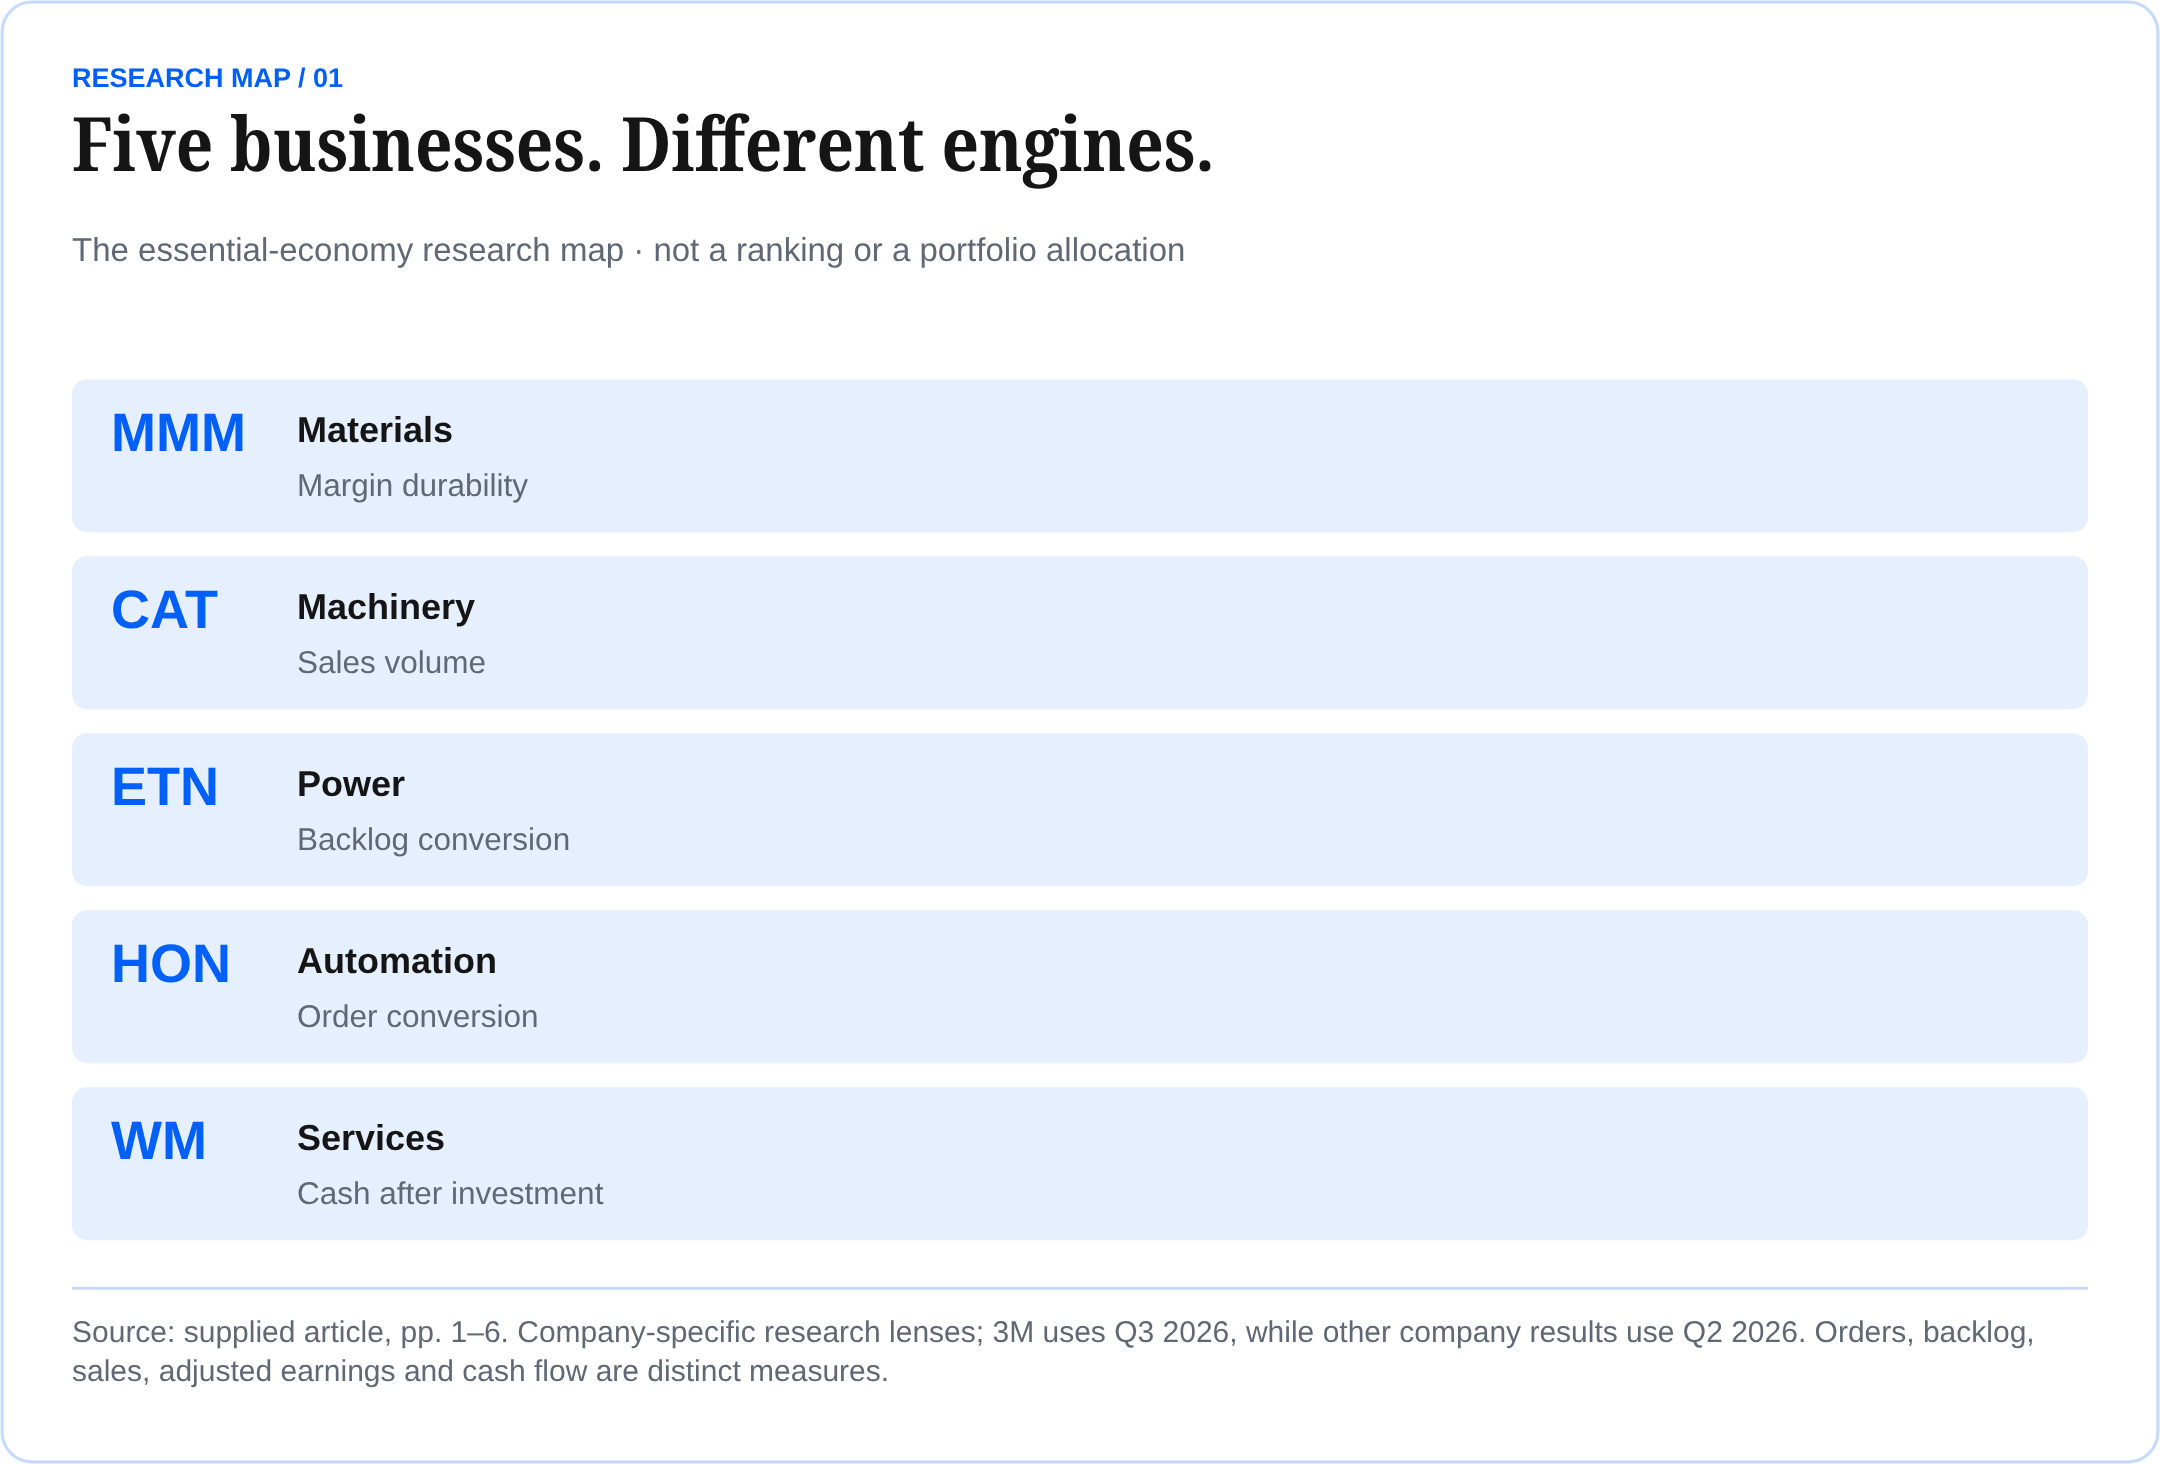
Essential businesses. Different growth engines. A research list to evaluate alongside valuation, financial strength and cash generation.
MMM / 3M
Materials + industrial products
Q3 adj. EPS +12%; adj. margin 26.2%.
Watch: organic growth and margin durability.
CAT / Caterpillar
Machinery + power equipment
Q2 revenue +24%; adj. EPS $8.17.
Watch: volume, orders and tariff benefits.
ETN / Eaton
Electrical infrastructure
Q2 organic sales +14%; electrical backlog +43%.
Watch: backlog conversion and profitability.
HON / Honeywell Technologies
Building + industrial automation
Q2 orders +16%; organic sales +4%, ex-Aerospace.
Watch: October 22 results and order conversion.
WM / Waste Management
Collection + disposal services
Q2 revenue +4%; operating cash flow up ~12%.
Watch: volume trends and cash after investment.
Growth earns attention. The price paid determines how much future success is already assumed. Compare valuation with sustainable earnings and cash flow before committing capital.
EXPLORE YOUR TRADING PLATFORM
| Fidelity | Charles Schwab |
| Interactive Brokers | Tiger Trade |
Platform access and security availability depend on your country, account and permissions.
RESEARCH THE BUSINESS.
INVEST WITH CONVICTION.
GIVE LONG-TERM VALUE TIME TO DEVELOP.
| Subscribe now for free | Get in touch with our team |
| Visit TheInvestorCall.com → |
 Research that matters. Insight you can trust. |  |
Production note: this is a design adaptation of the supplied October 21, 2026 article. Figures, company terminology, reporting periods, guidance and original link destinations are retained as supplied, not independently verified or updated. Charts visualize the supplied figures only. General editorial research, not personalized investment advice.
