
|
01 / THE MARKET / A NEW ENTRY POINT? / OCTOBER 30, 2026 Google just |  |
Google’s sell-off. Anthropic’s $80 billion loss headline. Five stocks - and the evidence to read before investing.
$283.82 GOOGL / OCT. 29 CLOSE | −12.64% IN ONE SESSION |
| GOOGL | MSFT | AVGO | TSM | FCCN |
Imagine opening two headlines over your morning coffee. Anthropic reports an enormous loss. Alphabet reports growing revenue and operating profit. Instinct offers a quick verdict: avoid the first and applaud the second.
The market gives us a more interesting story. Anthropic is pursuing an IPO. Alphabet’s Class A shares closed October 29 down 12.64%, at $283.82. The same week asks investors to interpret very different kinds of financial evidence.
A loss can contain financing adjustments. A growing business can disappoint expectations. A falling share price can improve an entry point while leaving important questions unanswered.
Today we examine what those headlines actually mean, then connect the story to five tickers. Our lead idea is Alphabet; our test is whether its earning power can justify the investment required to expand it. The price changed. Now the business must make the case.
The price changed. Now the business must make the case.
Research dated October 30, 2026; market price uses the October 29 regular-session close. Dollars are U.S. dollars unless stated. Investment views are editorial judgments for a multiyear horizon.
Opening corner artwork is a schematic market illustration; the line is not a price history.
02 / ANTHROPIC / READ BEYOND THE HEADLINE The loss was huge. |  |
How a reported $80.7 billion loss became a debate about accounting, growth, and the price of an IPO.
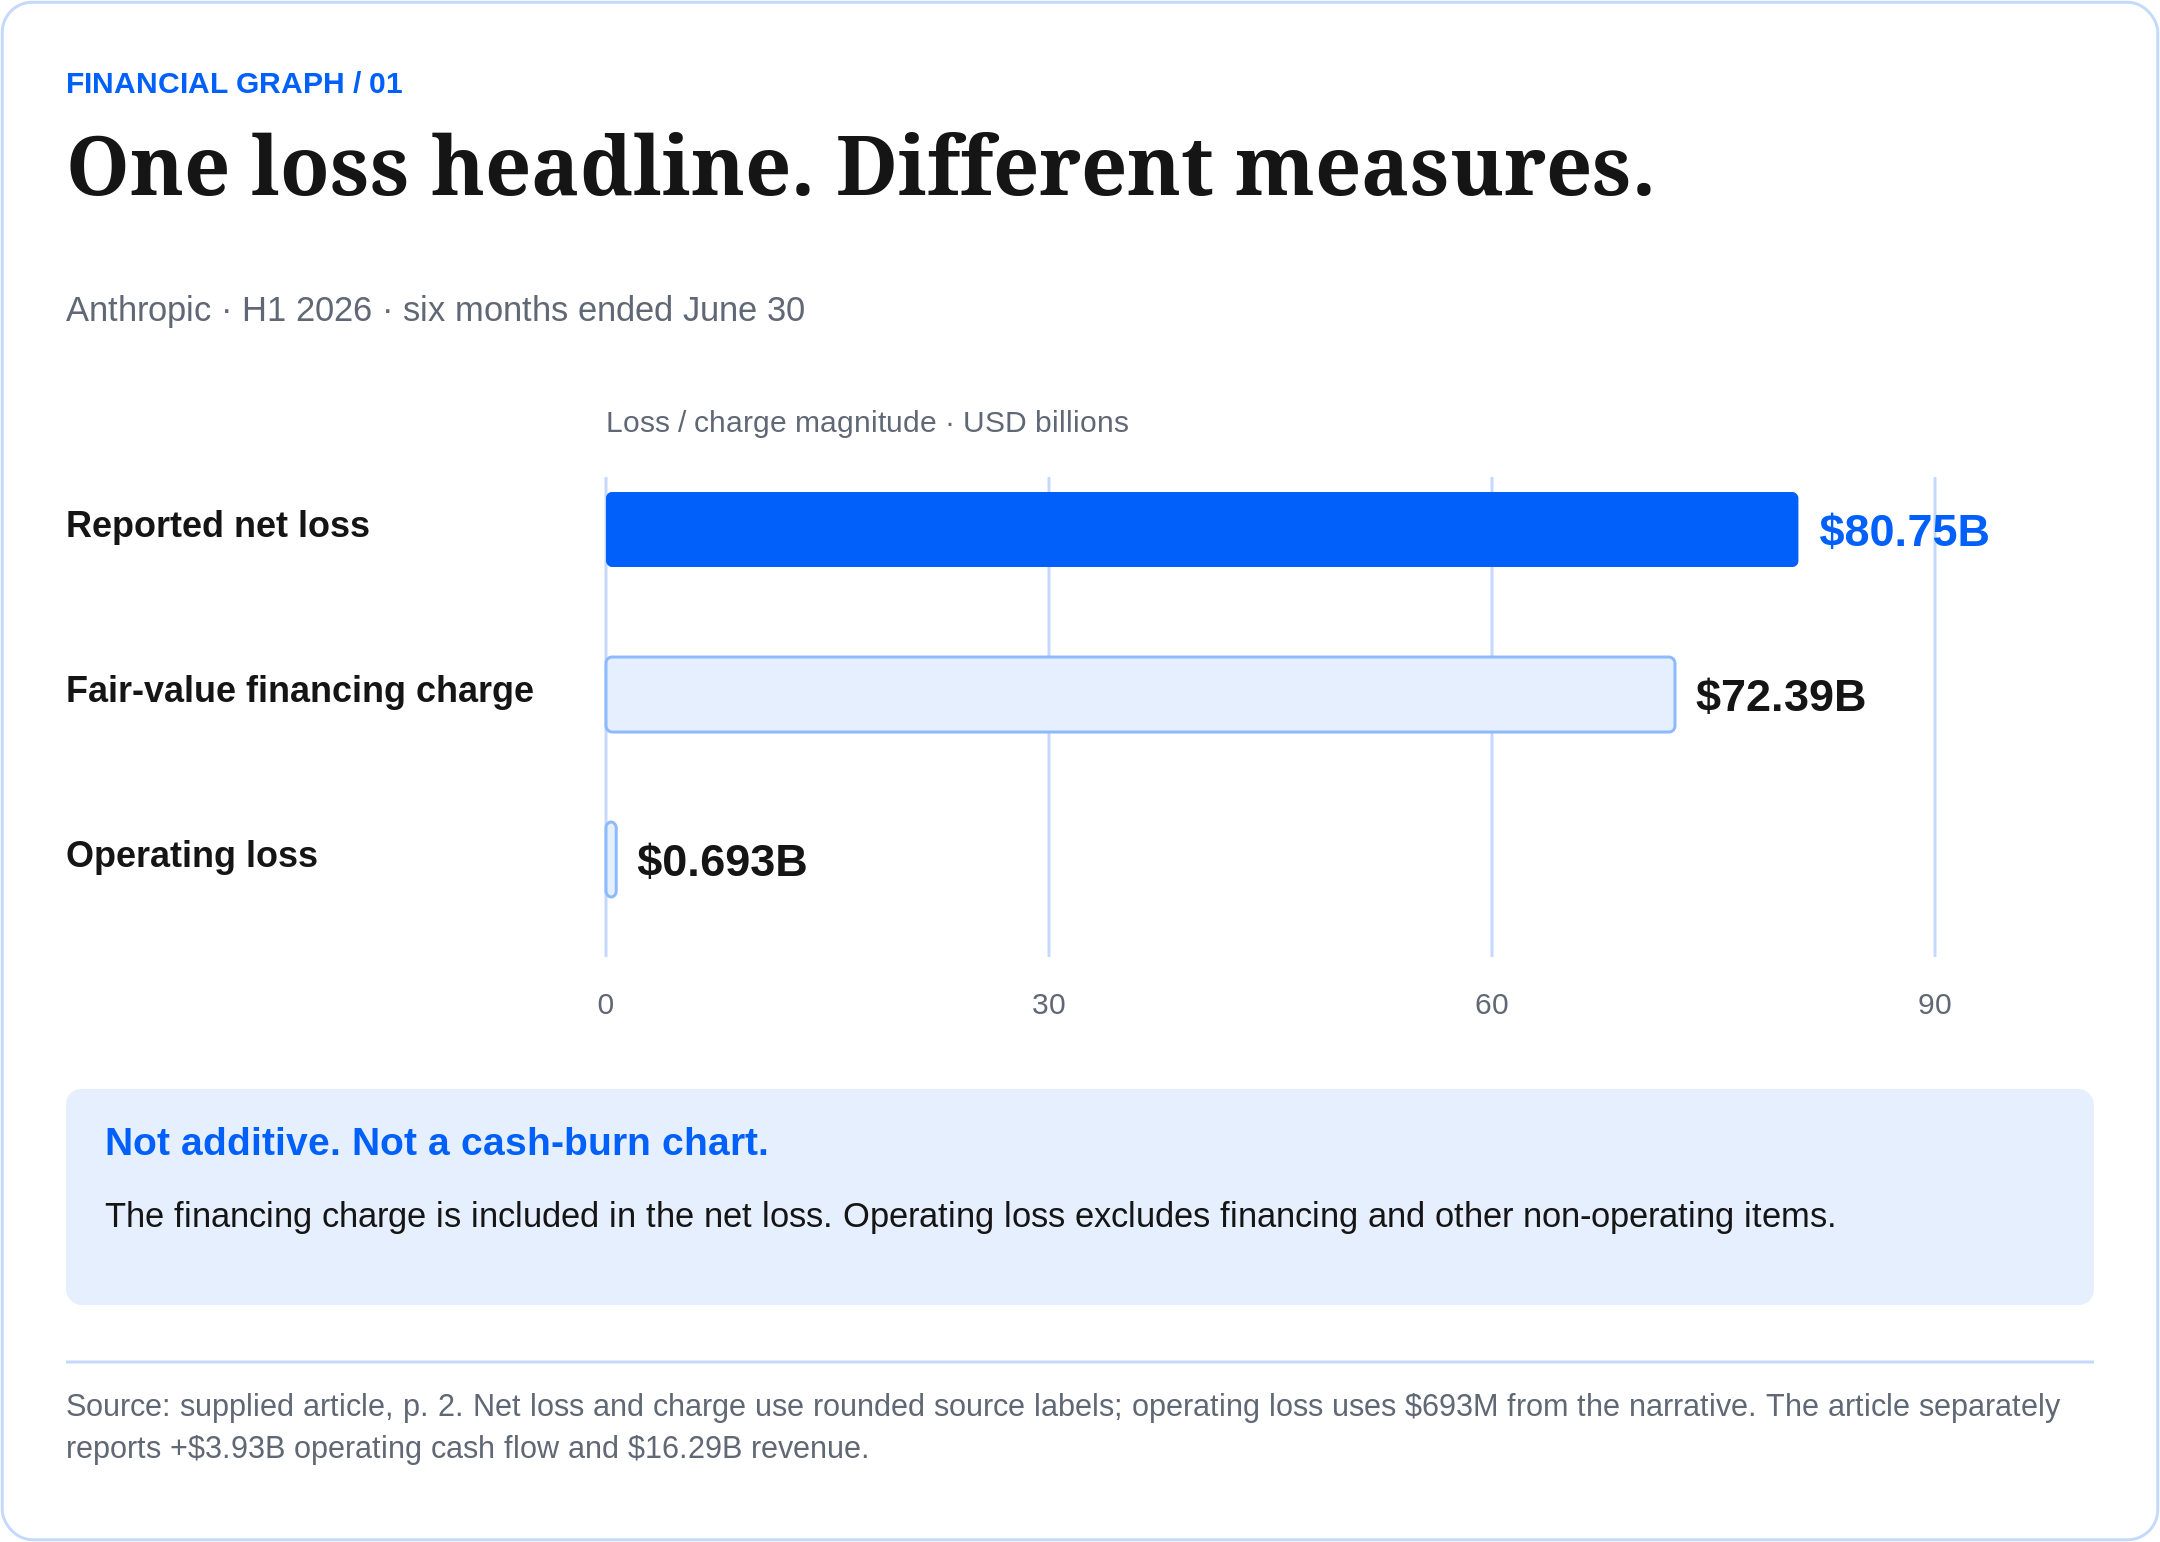
$80.75B H1 2026 net loss | $72.39B Fair-value financing charge | $0.69B H1 2026 operating loss |
These measures are not additive. The fair-value charge is included in the net loss; operating loss excludes financing and other non-operating items.
Why the numbers differ
Anthropic’s filing records a $72.4 billion charge from revaluing convertible notes, derivative liabilities, and SAFEs, a form of early-stage financing. It says the adjustment primarily reflected a higher enterprise valuation. As the company became more valuable, these obligations were remeasured upward.
That charge dominates the reported loss without representing the same amount of cash leaving the business. It does not explain every remaining expense. The operating loss was $693 million; operating cash flow was positive $3.93 billion. Revenue reached $16.29 billion in the first half.
Our interpretation: a headline loss cannot answer the funding question. Cash receipts, vendor payment timing, investment requirements, and future commitments must also be examined. Even positive operating cash flow in one period does not settle the long-term economics.
The reaction was selective
Reuters reported that some current and prospective investors discussed a valuation around $1.5 trillion, compared with roughly $2 trillion a week earlier, after financial details were shared at an investor event. These were private valuation expectations, not a public share-price collapse.
It would be too strong to attribute that change solely to the loss headline. Investors also faced an ambitious valuation, intense competition, and substantial computing commitments. Excitement about growth could coexist with a demand for a better entry price.
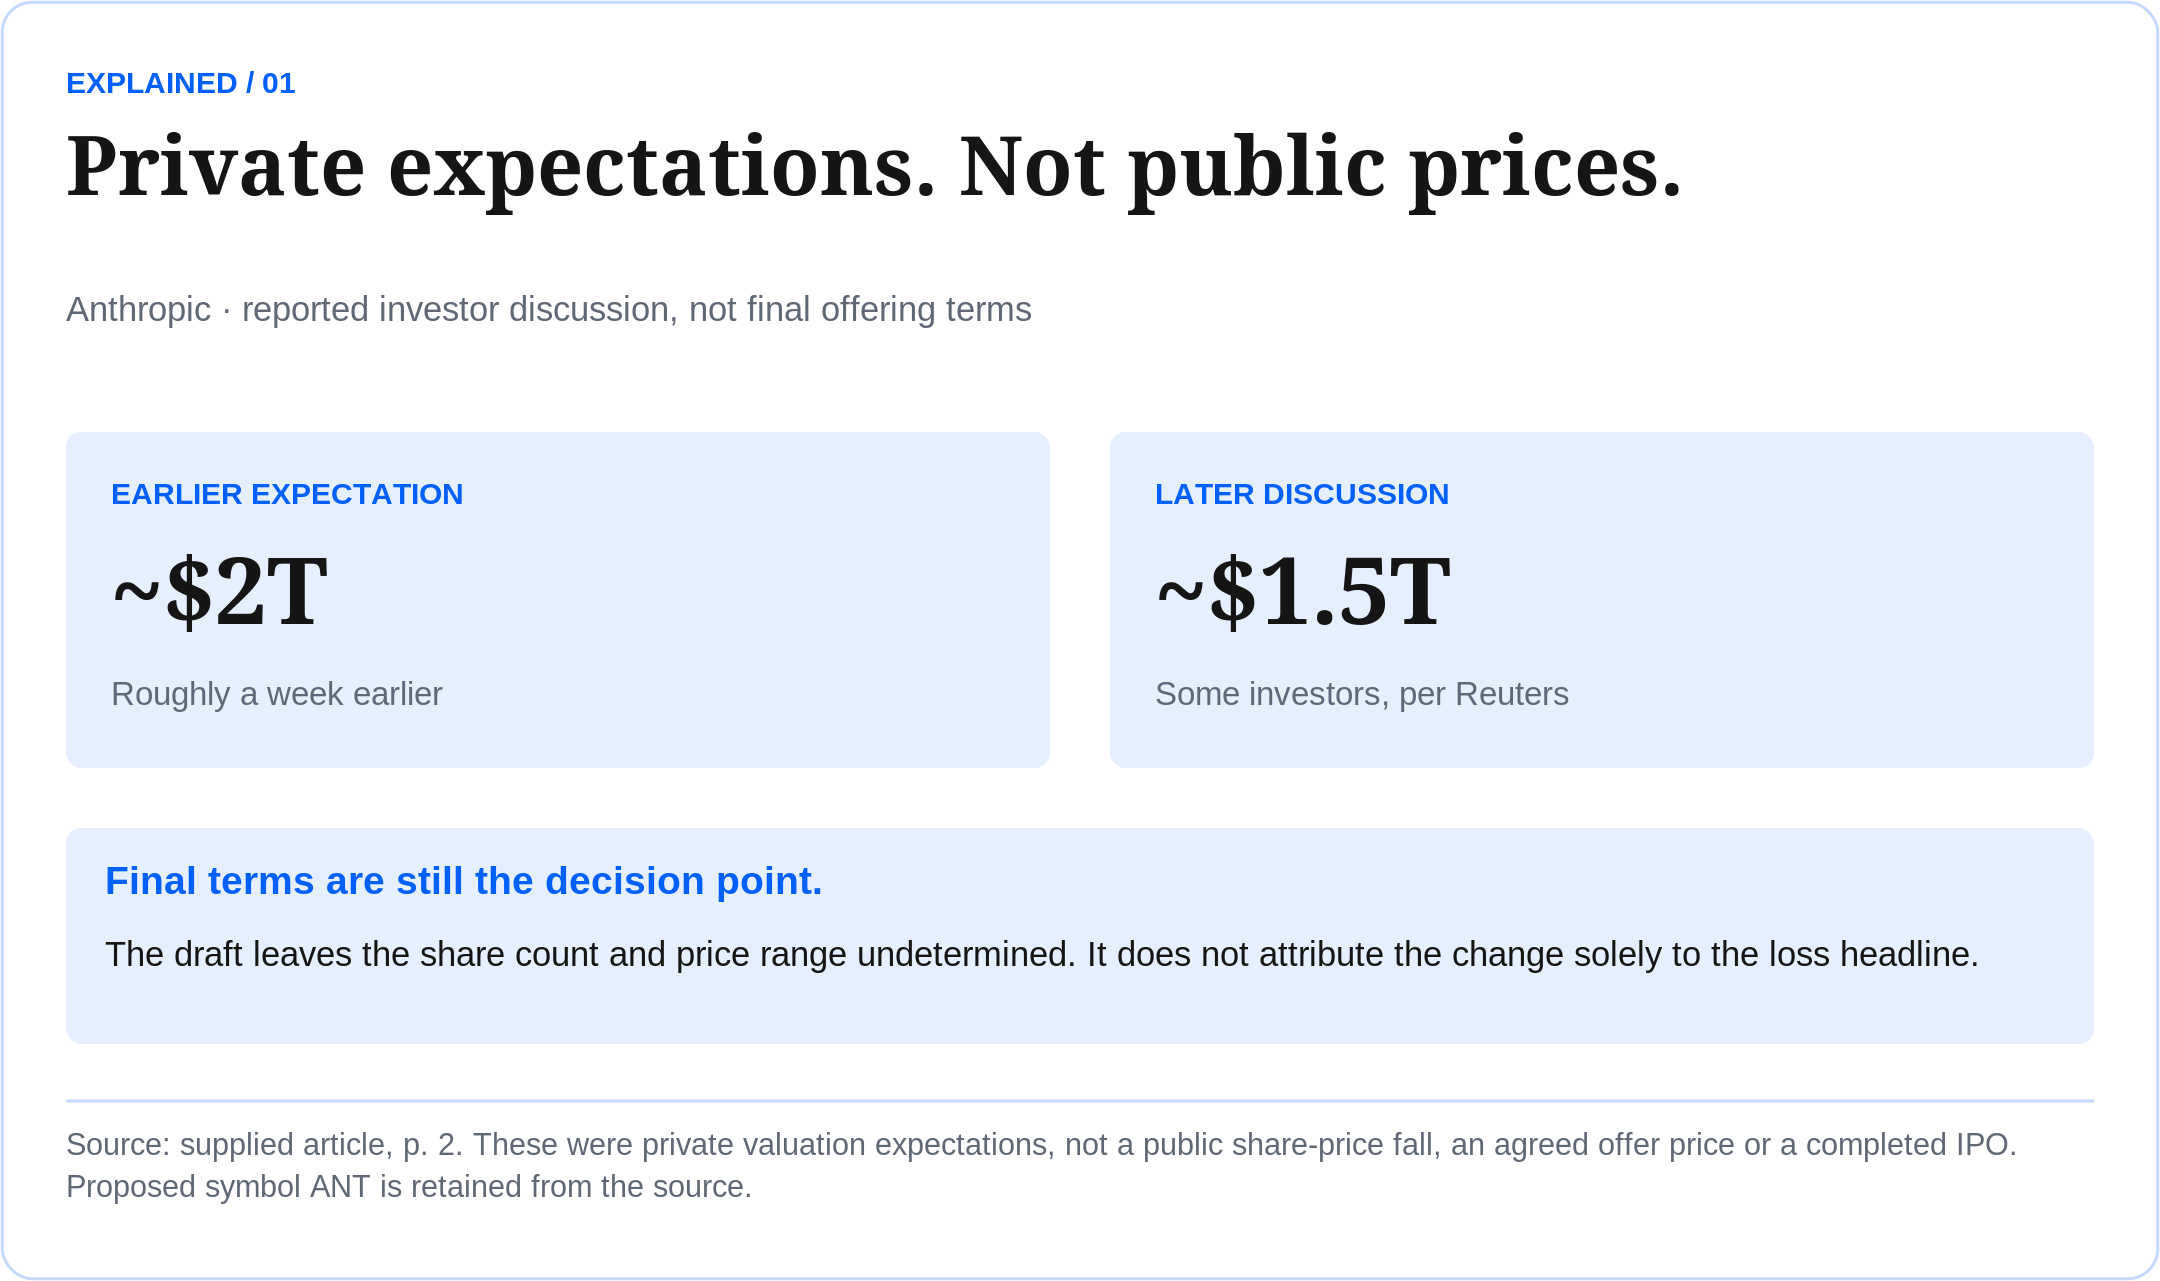
Our stance: wait for final offering terms. Anthropic’s October 26 announcement proposed Nasdaq symbol ANT and left the share count and price range undetermined. Assess dilution, governance, and funding obligations before deciding what the opportunity is worth.
H1 means the six months ended June 30, 2026. Rounded figures from the registration statement. Proposed IPO terms can change; a filing is not a completed offering. Financial figures and cash movements use different accounting bases.
Anthropic S-1 · Official IPO announcement · Reuters / investor reaction
03 / ALPHABET / NASDAQ: GOOGL A lower price. |  |
Our lead idea: consider a measured first position, then let operating evidence justify the next purchase.
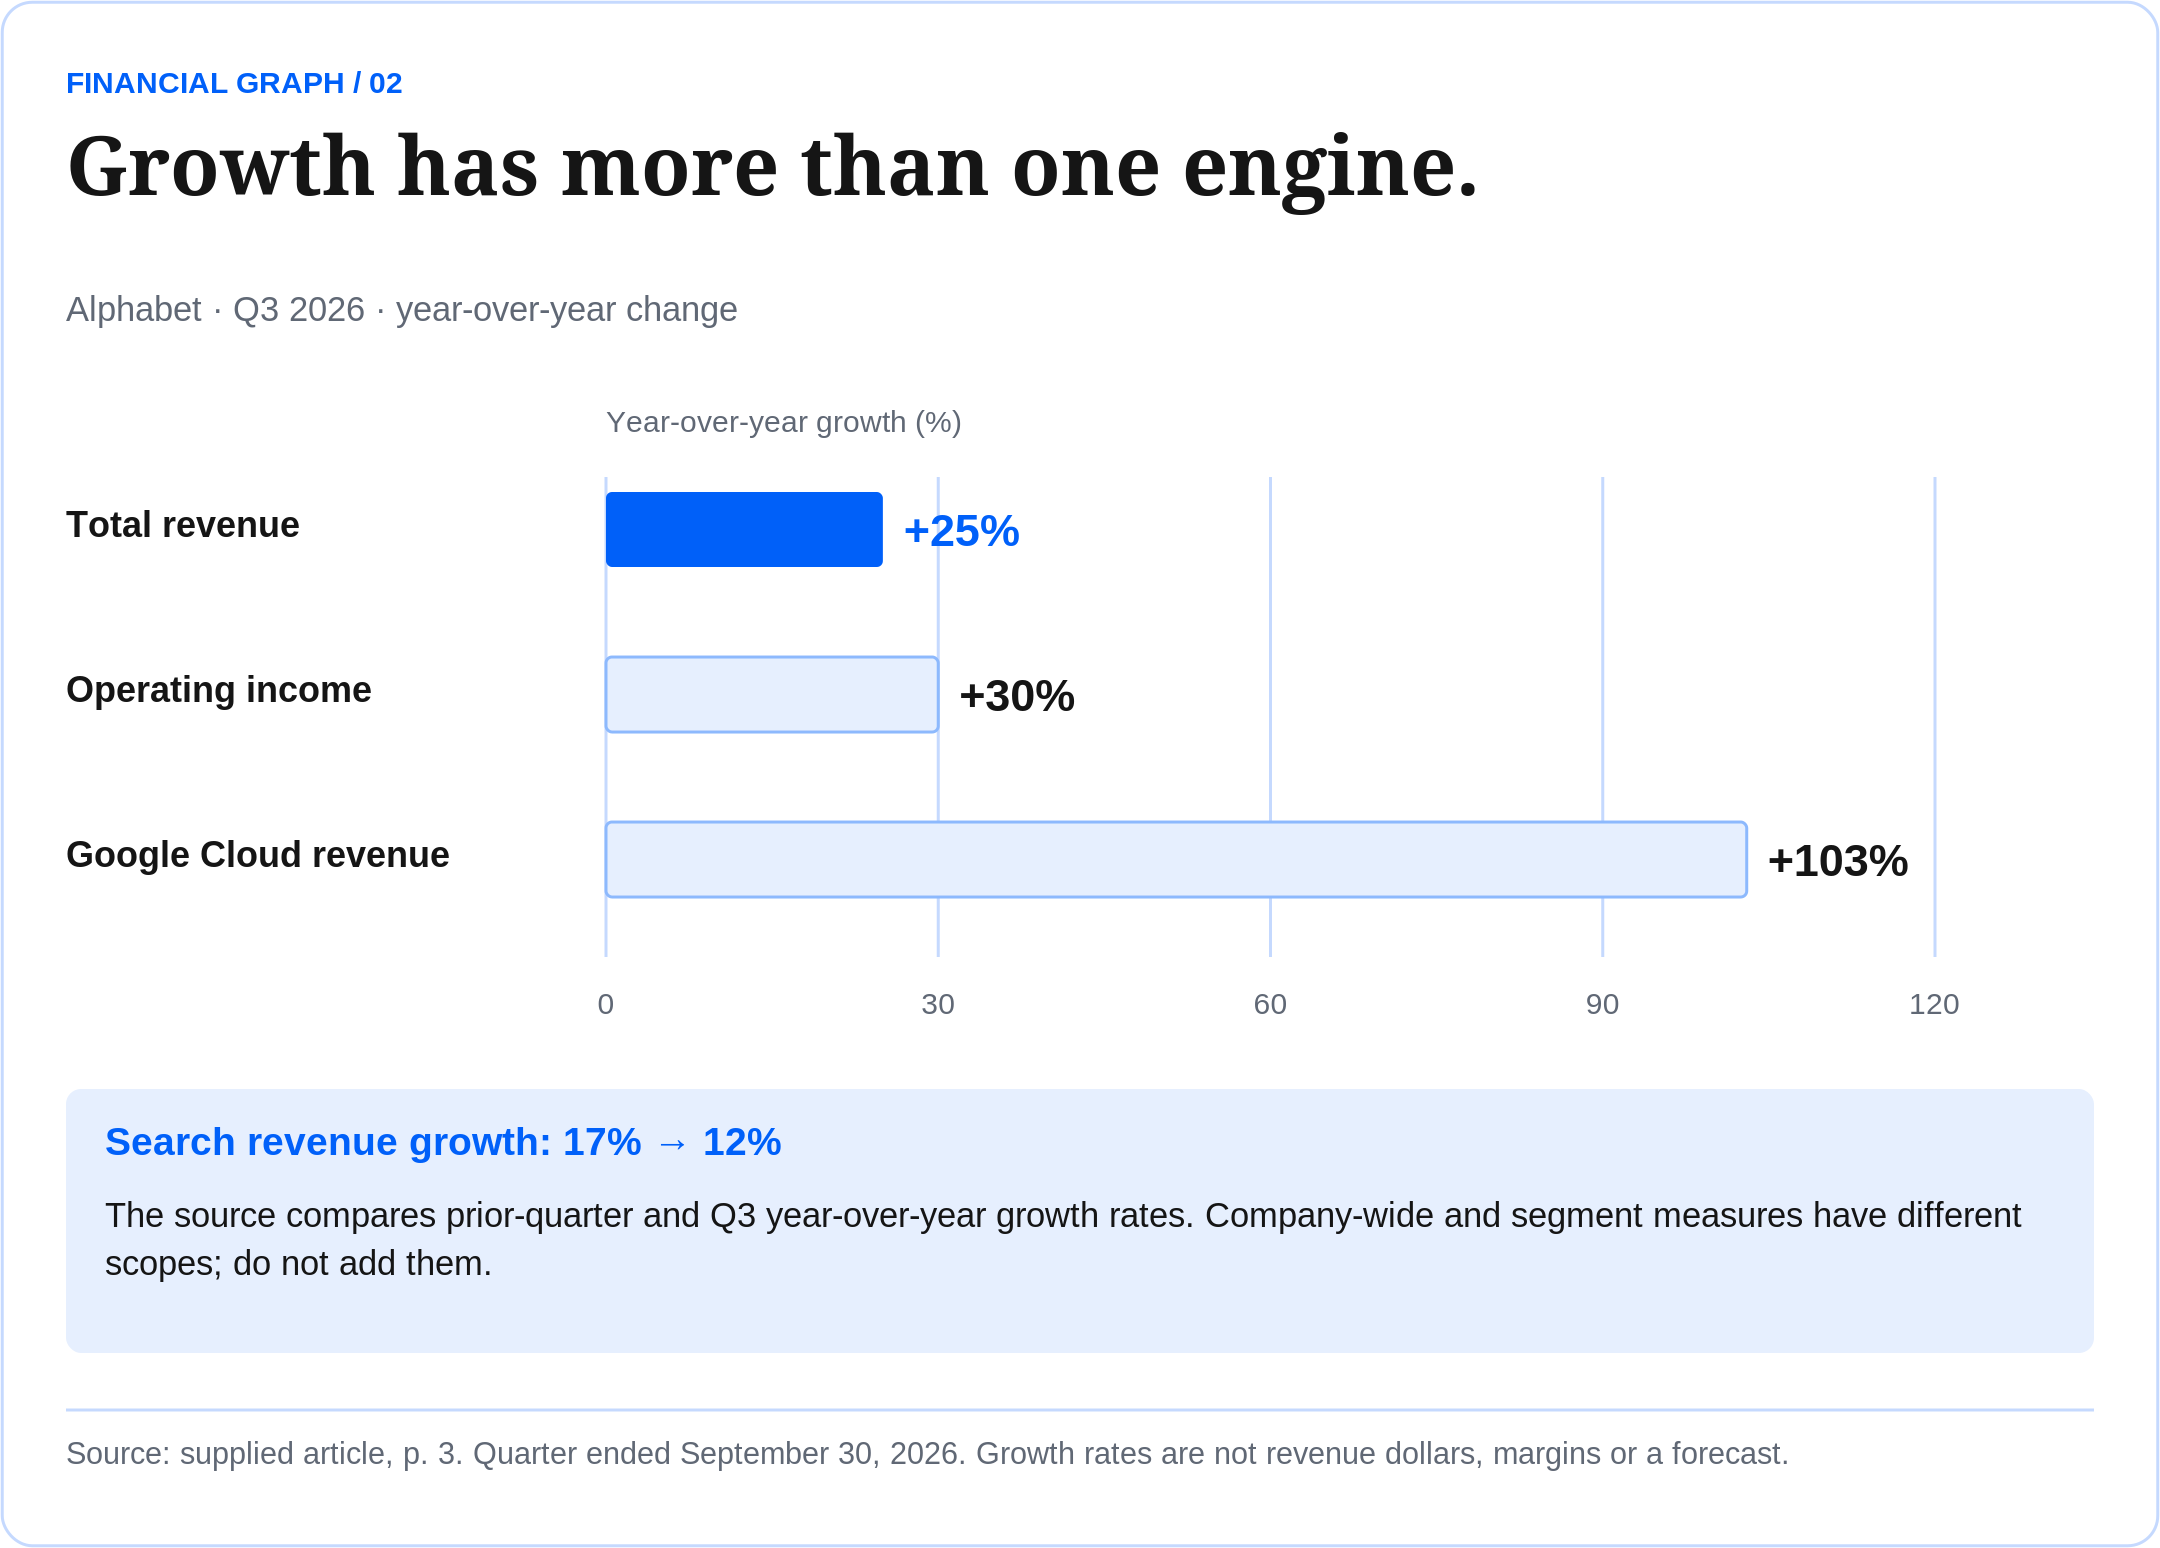
+25% Q3 2026 revenue growth | +30% Operating income growth | +103% Google Cloud revenue growth |
What investors are buying
Search connects commercial intent with advertisers. YouTube adds advertising and subscriptions. Google Cloud supplies computing services. Together, these operations give Alphabet several routes to monetize customer activity.
Search revenue growth slowed to 12% from 17% in the prior quarter. AFP reported advertising results below expectations. An equity-investment loss also weighed on net income, separately from operating performance.
Our opportunity thesis: if Search remains commercially durable and Cloud scales profitably, a lower purchase price could improve the return available to a patient shareholder.
What must improve next
Capital spending exceeded operating cash generation in the quarter. That is the financial hurdle behind the growth story. Revenue expansion must eventually produce cash after the spending required to support it.
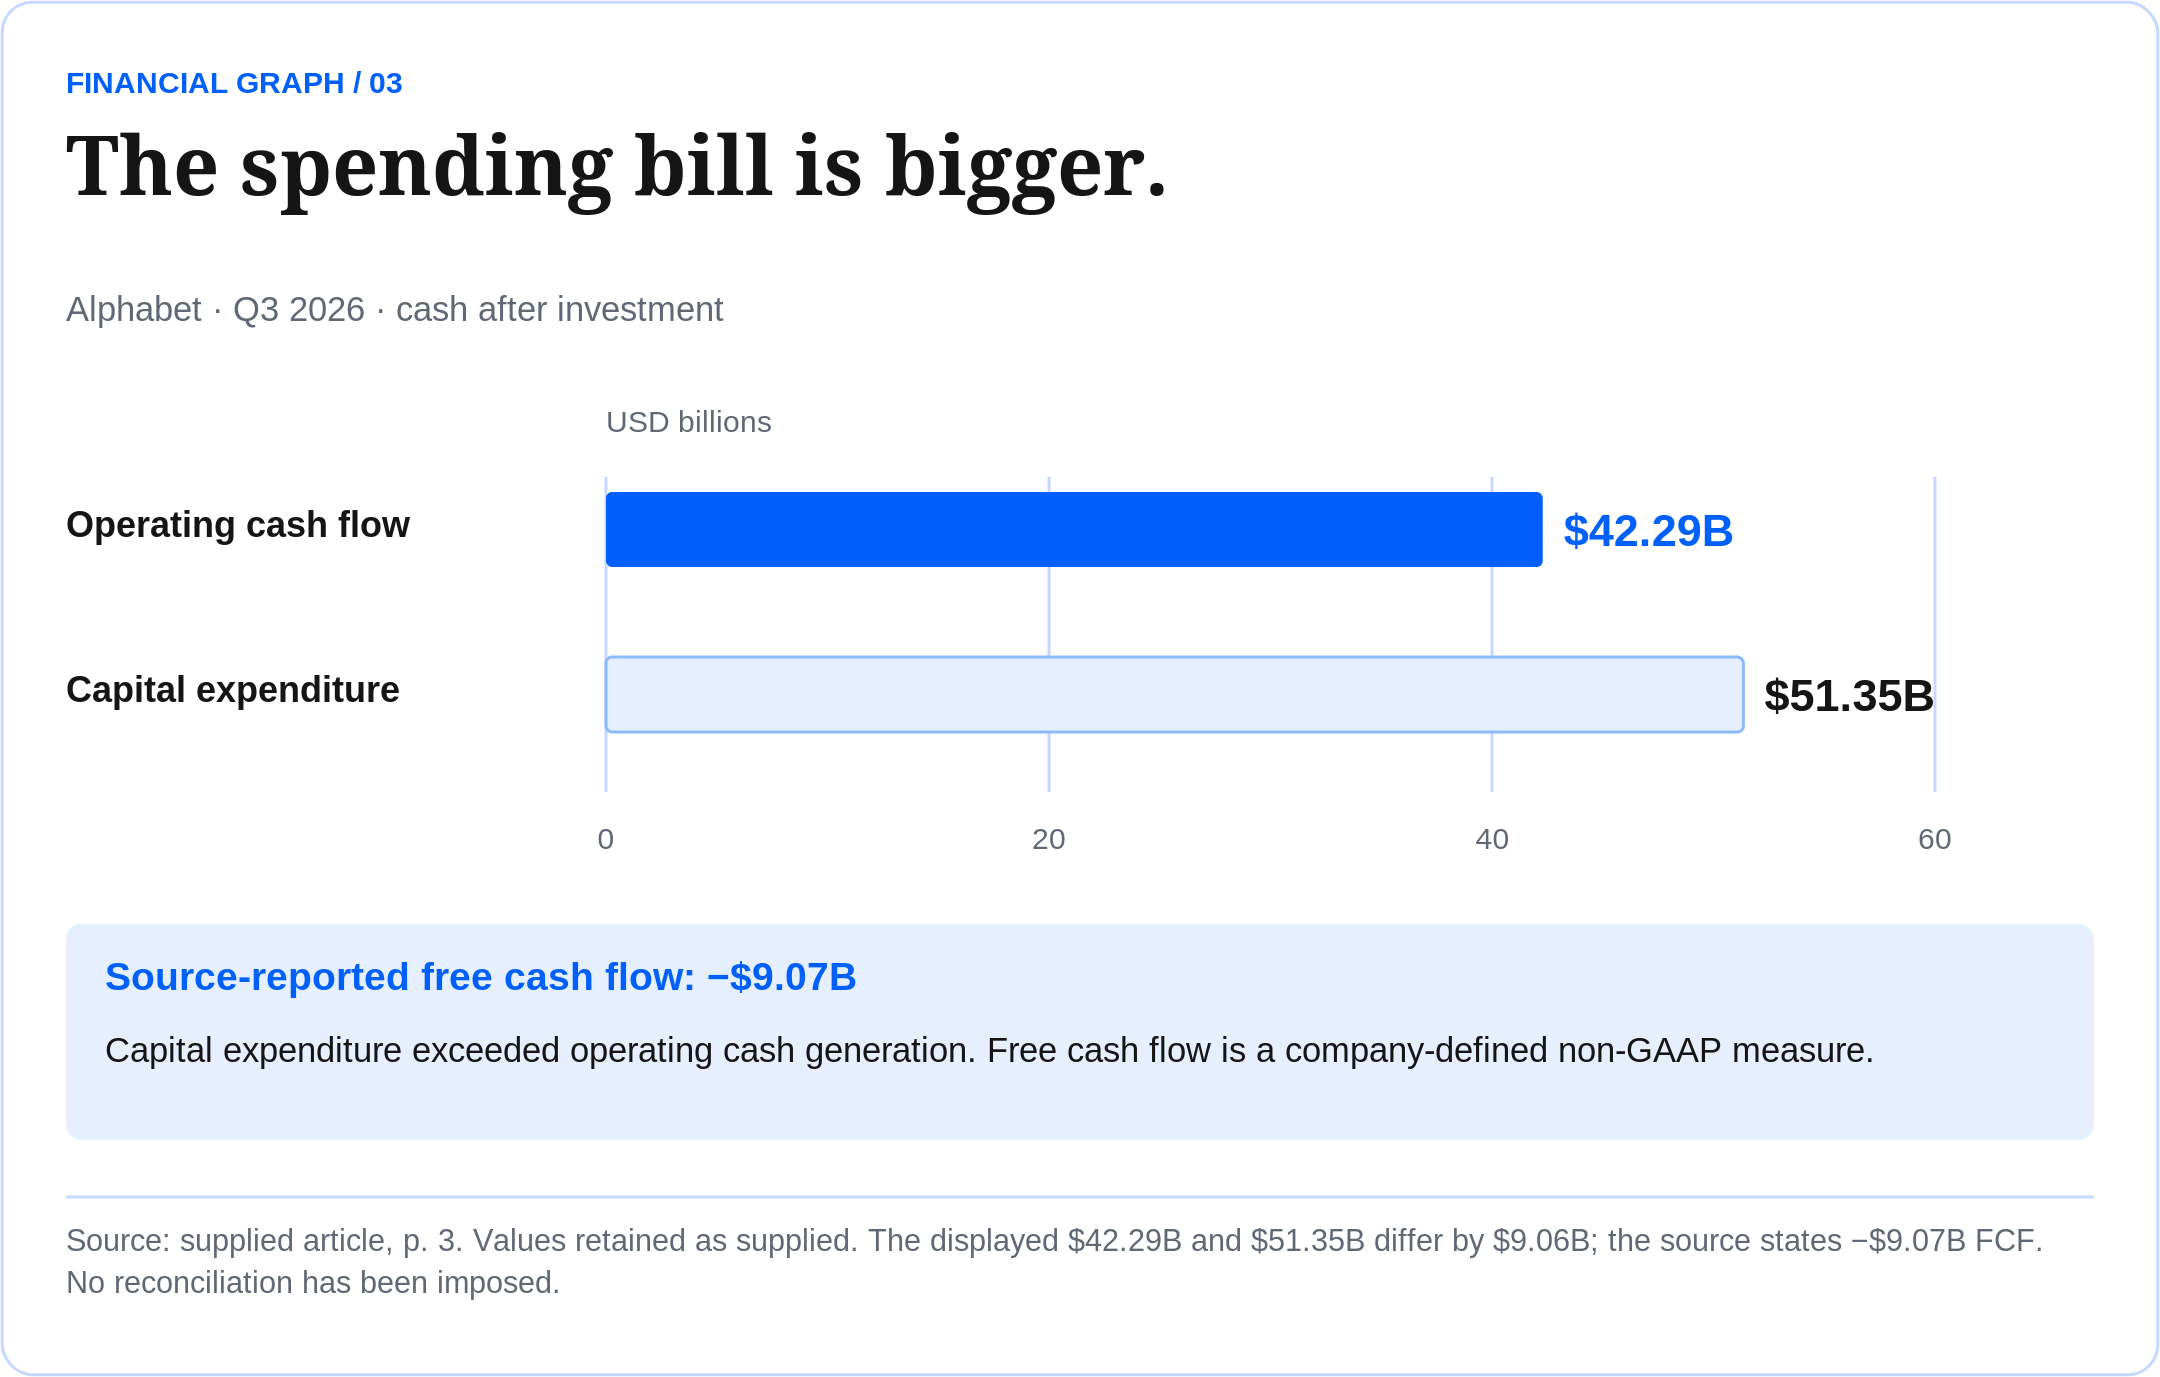
Our view: consider a small initial position for a multiyear horizon. Add only as Search durability, cloud profitability, and cash conversion strengthen. A further decline in cash generation would weaken the case.
This is a conditional judgment, not a valuation model. The sell-off changes the entry price without proving the shares are cheap. Returns depend on execution and the price paid.
A lower price still needs operating proof.
Q3 is the quarter ended September 30, 2026. Growth is year over year unless stated. Free cash flow equals operating cash flow less purchases of property and equipment; it is a company-defined non-GAAP measure.
Alphabet Q3 / cash-flow reconciliation · AFP / earnings reaction
|
04 / MSFT + AVGO + TSM / THREE ROUTES INTO DEMAND The platforms. |  |
Different economic roles, with a shared question: how much cash reaches shareholders after growth is funded?
MSFT / NASDAQ
Microsoft
+48% Azure revenue growth |
Microsoft combines enterprise software with cloud infrastructure. Its latest quarter produced $45.9 billion in operating income, up 21%, and $18.6 billion in free cash flow. Existing customer relationships provide a route for selling additional cloud and AI services.
Our view: an alternative accumulation candidate, subject to valuation. Watch whether infrastructure investment continues to support profits and cash. A strong quarter establishes execution; it does not establish an attractive share price. FY27 Q1 ended September 30, 2026.
AVGO / NASDAQ
Broadcom
$13.7B Quarterly free cash flow |
Broadcom supplies custom AI accelerators and networking, alongside infrastructure software. Fiscal Q3 revenue reached $29.6 billion, including $16.7 billion of AI semiconductor revenue. Free cash flow was $13.7 billion, reflecting the cash economics of its own business model.
Our view: a valuation-sensitive infrastructure candidate. Watch customer concentration, order conversion, and recurring cash generation. Selling into a spending boom offers opportunity, but demand can change. Fiscal Q3 ended August 2, 2026; it is not the same period as Microsoft’s quarter.
TSM / NYSE ADR
TSMC
58.7% Q3 operating margin |
TSMC manufactures semiconductors for customers designing advanced chips. Its U.S.-listed ADR offers exposure to that manufacturing role. Q3 dollar revenue reached $46.72 billion, up 41.2% year over year, with an operating margin of 58.7%.
Our view: a long-term research candidate. Advanced-node demand and profitable capacity expansion are the operating tests. Semiconductor cycles and Taiwan exposure also matter. Evaluate ADR terms and valuation alongside results. Q3 ended September 30, 2026; accounts follow TIFRS.
Reporting periods differ; the metrics above are not a like-for-like ranking. Microsoft and Broadcom free cash flow are company-defined measures. Growth and operating results do not by themselves establish fair value.
Microsoft results · MSFT cash flow · Broadcom results · TSMC results
05 / SPECTRAL CAPITAL / OTCQB: FCCN An operating base. |  |
International telecommunications provides the business foundation. Implementation must establish the value of the technology strategy.
$646.8M H1 2026 revenue | $5.27M Cash at June 30, 2026 | $1.56M H1 operating cash outflow |
The business already operating
Spectral operates international voice and messaging businesses through Telvantis Voice Services and 42 Telecom, also described as FortyTwo. The company reported $318.3 million of Q2 revenue, bringing first-half revenue to $646.8 million.
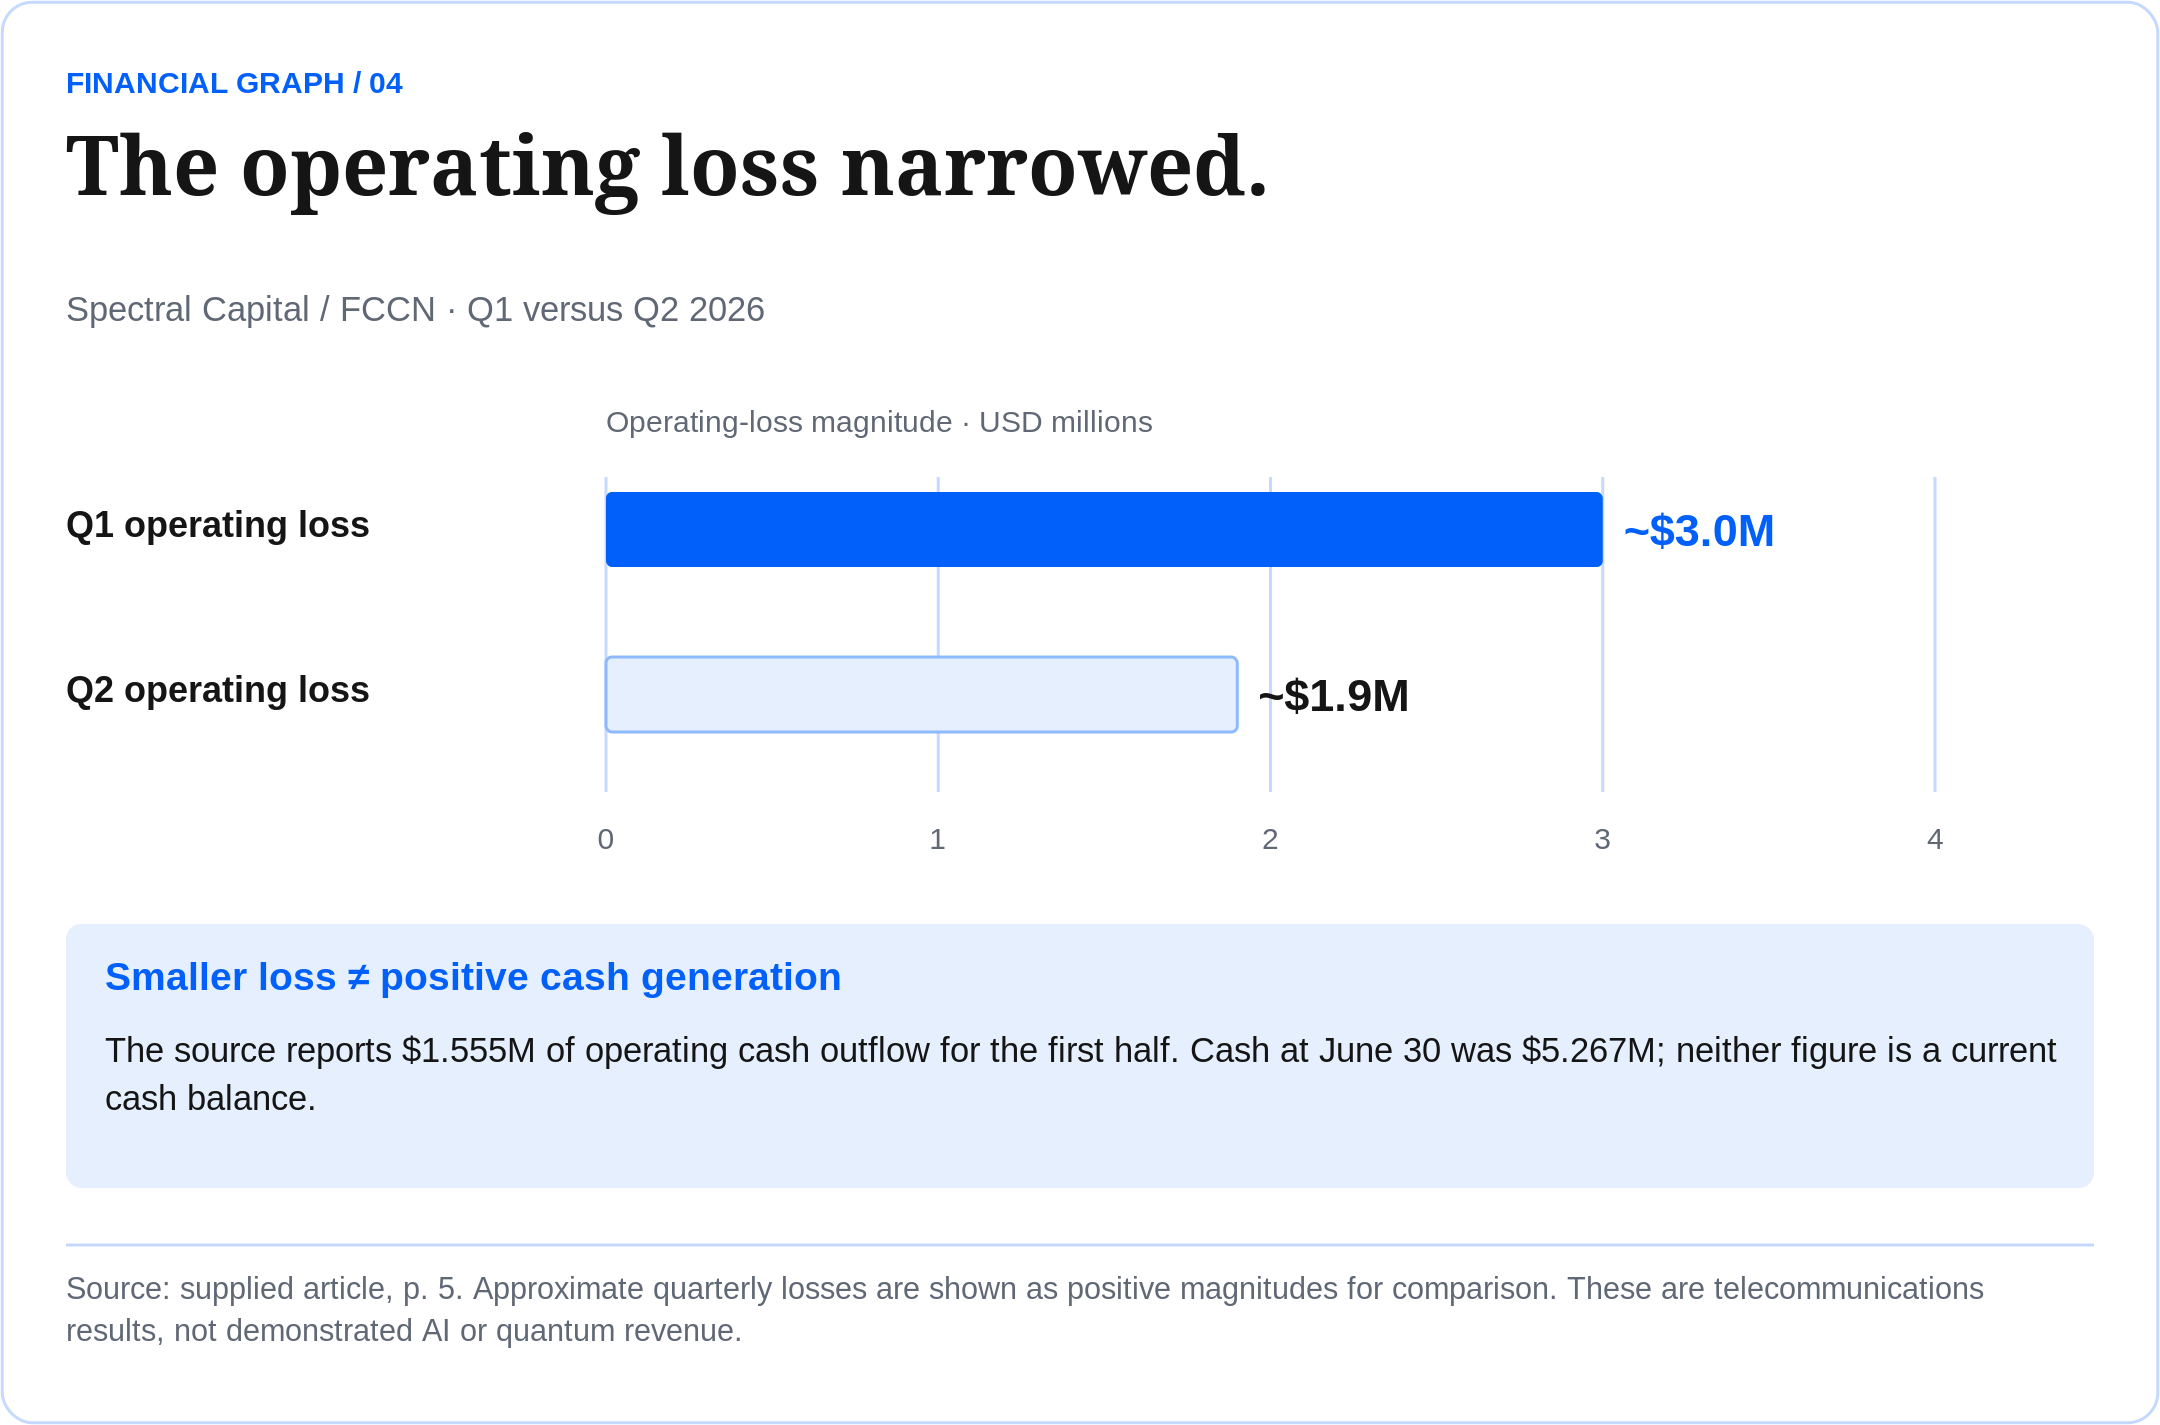
The expanded consolidated group explains the revenue scale; it should not be read as a like-for-like organic growth rate. Q2 gross profit was approximately $3.3 million, while the operating loss narrowed to about $1.9 million from $3.0 million in Q1.
These are telecommunications results. Prospective AI, quantum-computing, and intellectual-property applications need separate evidence of deployment and customer economics. Revenue from an existing service does not establish revenue from a future technology.
Our research question is practical: can the operating network become a platform for measurable efficiency improvements and stronger cash conversion? That is where implementation could make the story more valuable.
Milestones that earn conviction
The September 18 registration statement described an application for Nasdaq Capital Market listing. A September 28 amendment updated exhibits rather than establishing a completed listing. The sources reviewed continue to identify FCCN with OTCQB; an application is not approval.
Cash was $5.267 million at June 30. Operating activities used $1.555 million in the first half. Proposed offering proceeds are future financing, not cash already received. Funding terms, dilution, and liquidity therefore belong in the implementation assessment.
The filing describes an intellectual-property development strategy. Applications and research goals must remain distinct from issued patents, validated performance, and commercial revenue. Successful customer deployment would be more informative than an application count.
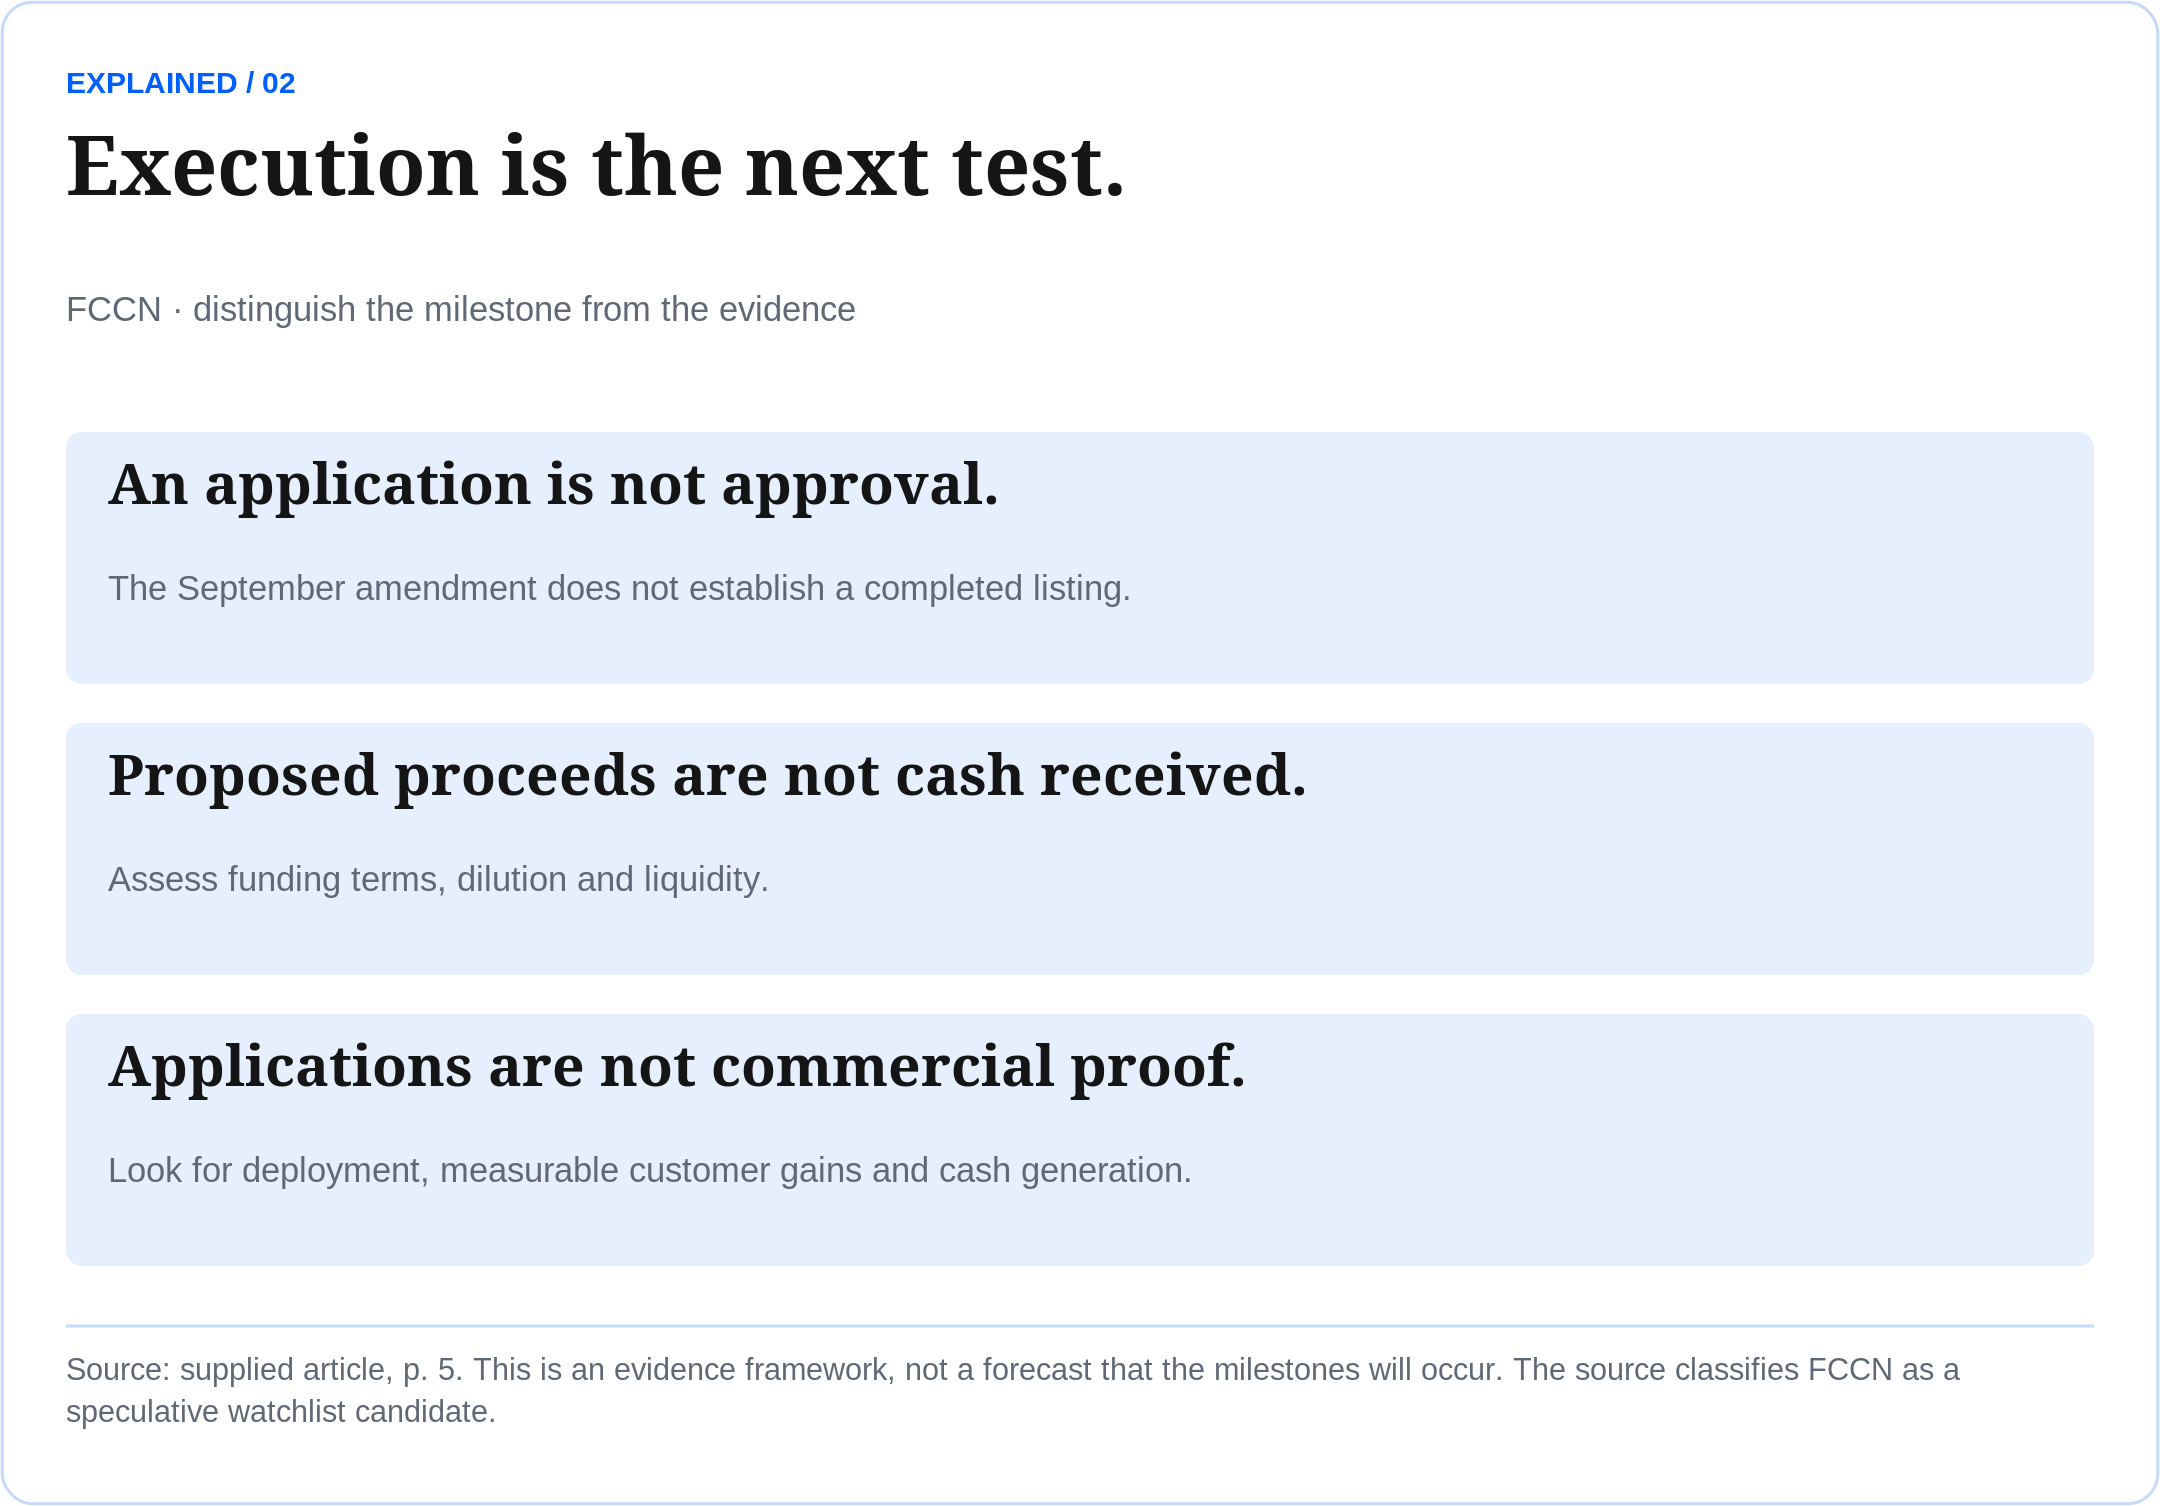
Our view: a speculative watchlist candidate. Funded deployment, measurable customer gains, and sustained cash generation would strengthen the investment case.
Financial figures refer to periods ended June 30, 2026; they are not current cash balances. FCCN is a speculative development exposure. Listing, financing, and technology milestones remain subject to verification and execution.
Spectral Q2 results · September 18 S-1/A · September 28 amendment
06 / THE INVESTOR CALL / INVESTMENT VIEW Five tickers. |  |
Alphabet leads this edition. The alternatives broaden the research; FCCN adds a speculative development story.
GOOGL | Search + cloud Consider a measured initial position. Watch Search durability and cash conversion. |
MSFT | Enterprise software + cloud Alternative accumulation candidate. Watch profits after infrastructure spending. |
AVGO | AI chips + networking Valuation-sensitive research candidate. Watch customer mix, orders, and cash flow. |
TSM | Semiconductor manufacturing Long-term research candidate. Watch advanced-node demand and returns. |
FCCN | Telecom + technology development Speculative watchlist. Watch funding, deployment, and cash generation. |
These businesses share exposure to technology spending; owning all five is not broad diversification. Consider a gradual Alphabet entry, assess the alternatives against valuation, and wait for Anthropic’s final offering terms.
EXPLORE TRADING PLATFORMS
| Fidelity | Charles Schwab |
| Interactive Brokers | Tiger Trade |
Availability, permissions, fees, and account eligibility depend on broker and jurisdiction. These links open broker websites; they are not orders or confirmation of ticker availability.
Research the business. Invest with conviction. Give long-term value time to develop.
| Subscribe now for free | Get in touch with our team |
|
Production note. This is a design edition of the supplied October 30, 2026 article. Figures, company claims, editorial stances and source-link destinations are retained as supplied, not independently verified or updated. Charts use the supplied figures and preserve reporting periods and qualifications. General editorial research, not personalized investment advice.
 Research that matters. Insight you can trust. |  |
