
THE INVESTOR CALL / THE AI INFRASTRUCTURE EDITION / OCTOBER 5, 2026
|
THE AI INFRASTRUCTURE EDITION FOLLOW THE MONEY. |  |
Trillions are moving into AI. We followed the capital to find out what is actually being built - and which companies get paid before the AI revolution reaches the customer.
AI IS NO LONGER ONLY A SOFTWARE STORY.
It is becoming one of the largest physical infrastructure buildouts of our generation.
CAPITAL → DATA CENTERS → CHIPS → POWER → COMPUTE → CUSTOMERS |
The question is not whether AI matters.
The question is where the money becomes something real - concrete, silicon, cooling, transformers, turbines, megawatts and ultimately revenue.
THE INVESTOR CALL TEST Show us the data center. Show us the chip. Show us the power. Show us the customer. |
01 / FROM PRESS RELEASE TO PHYSICAL ASSET $100 BILLION |  |
The headline number is only the beginning. Investors need to know what stage the capital has actually reached.
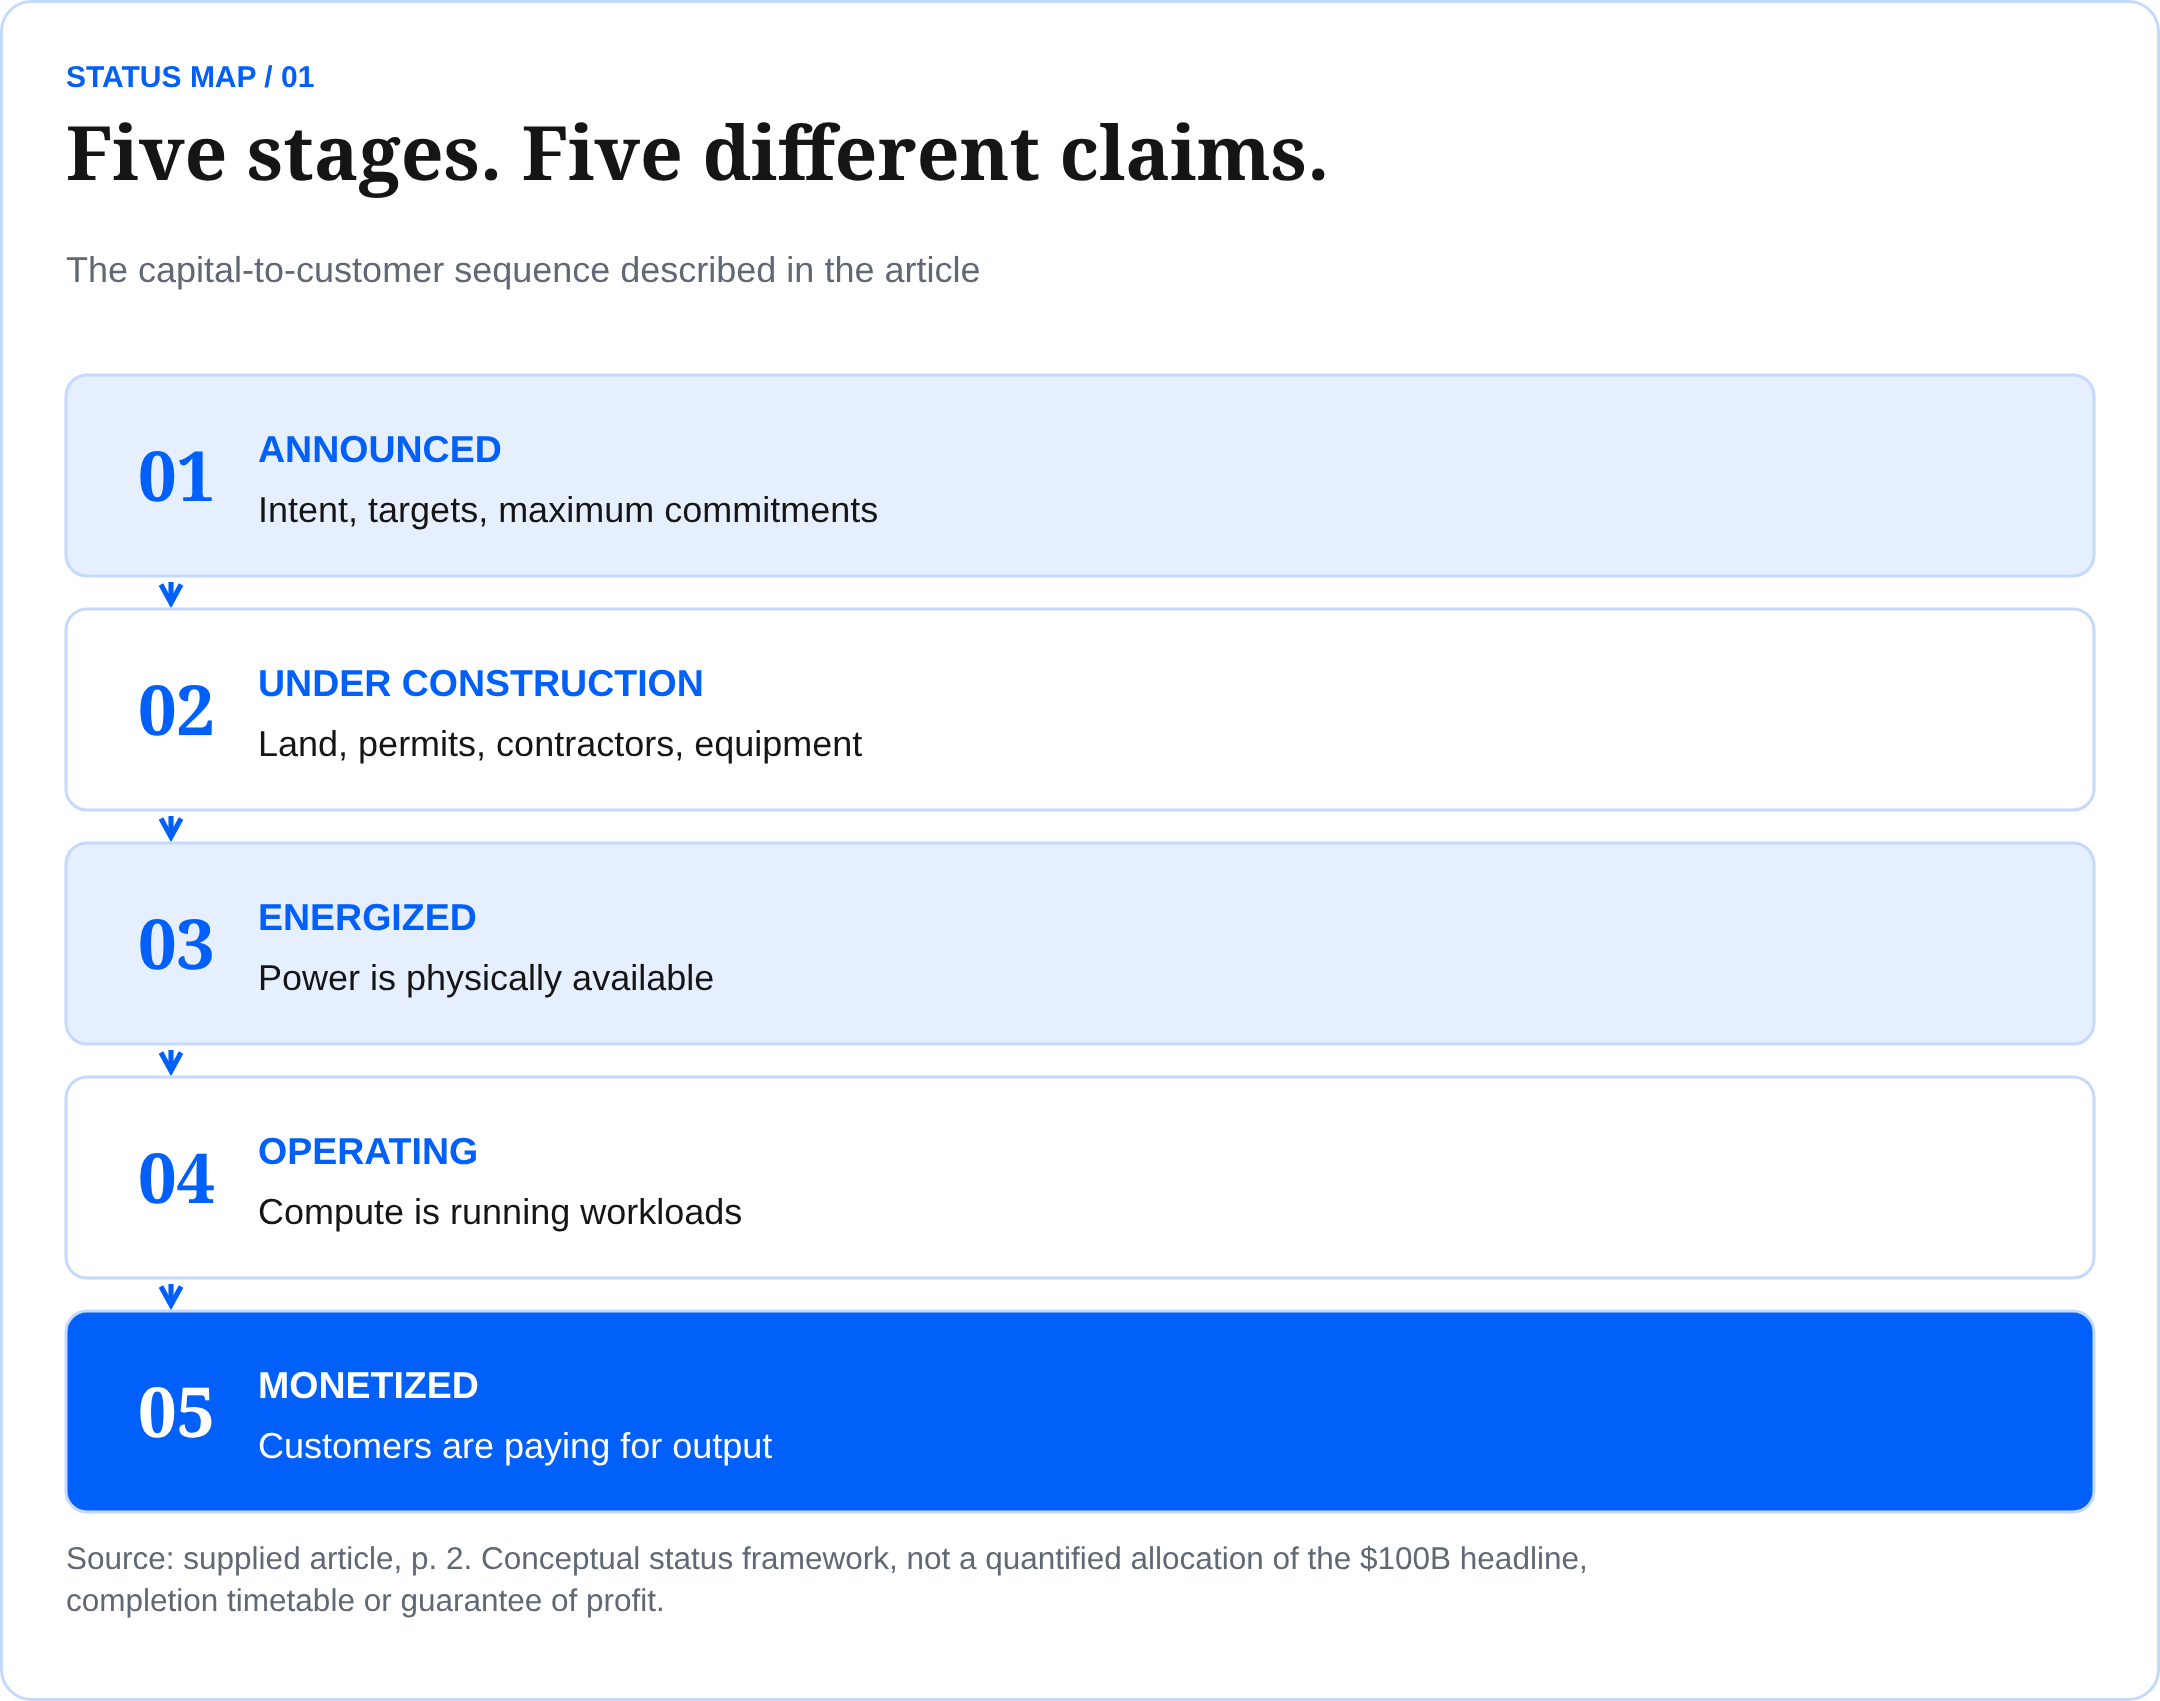
ANNOUNCED ≠ BUILT / BUILT ≠ ENERGIZED / ENERGIZED ≠ PROFITABLE |
Sources: OpenAI, Microsoft, company filings and investor relations; figures classified by current project status.
02 / FOLLOW THE CONCRETE AI DOESN’T LIVE |  |
The physical AI economy is already visible. Here are projects where capital has moved beyond the slide deck.
>5 GW UNDER DEVELOPMENT | STARGATE / ORACLE OpenAI says the U.S. Stargate footprint with Oracle is designed to run more than 2 million chips. |
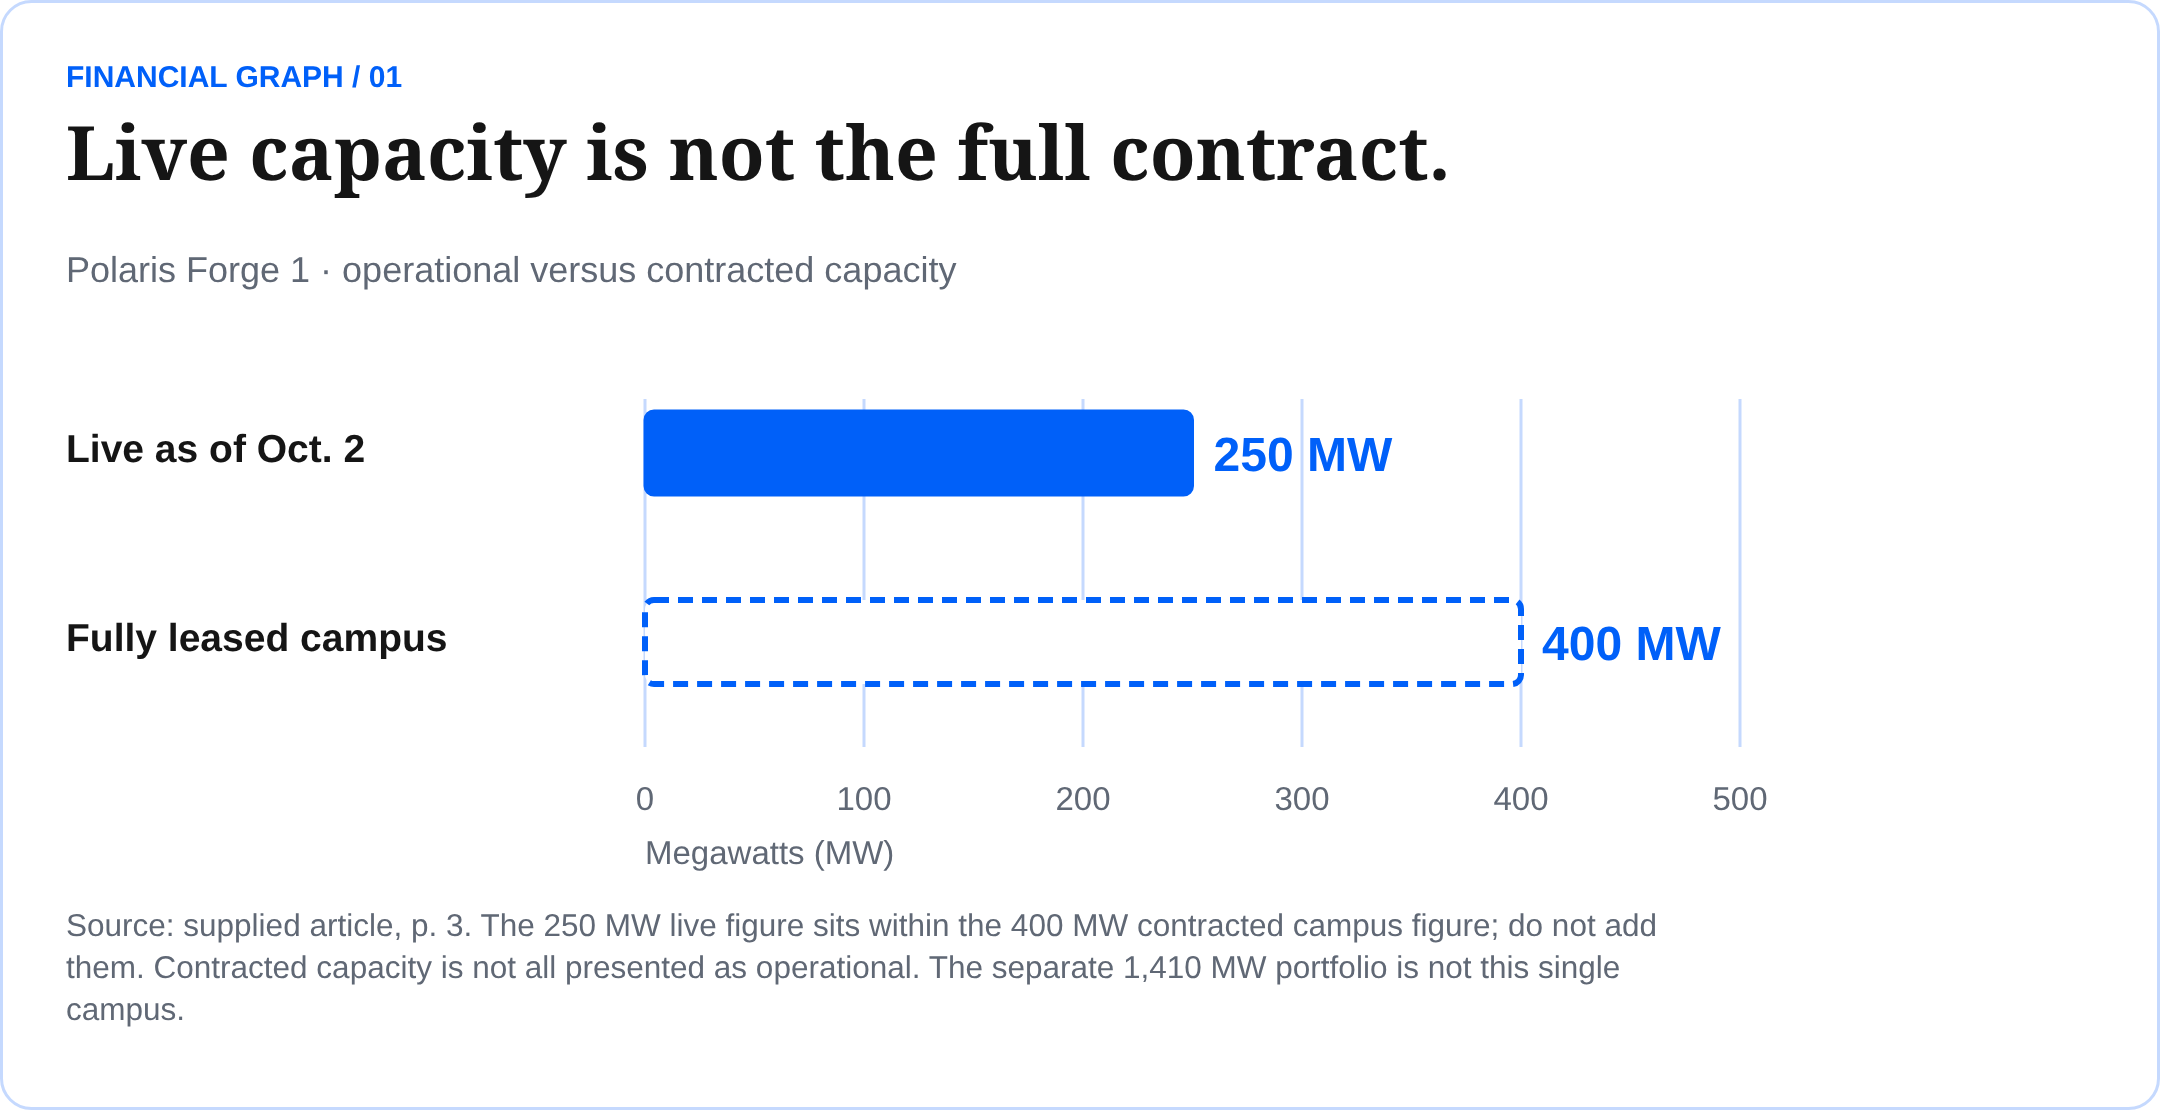
250 MW OPERATIONAL | APPLIED DIGITAL / PF1 As of Oct. 2, Polaris Forge 1 had 250 MW live; the fully leased campus is contracted for 400 MW. |
1,410 MW $36.2B CONTRACTED | APPLIED DIGITAL / PORTFOLIO Five campuses, long-term take-or-pay leases, with delivery schedules extending through 2028. |
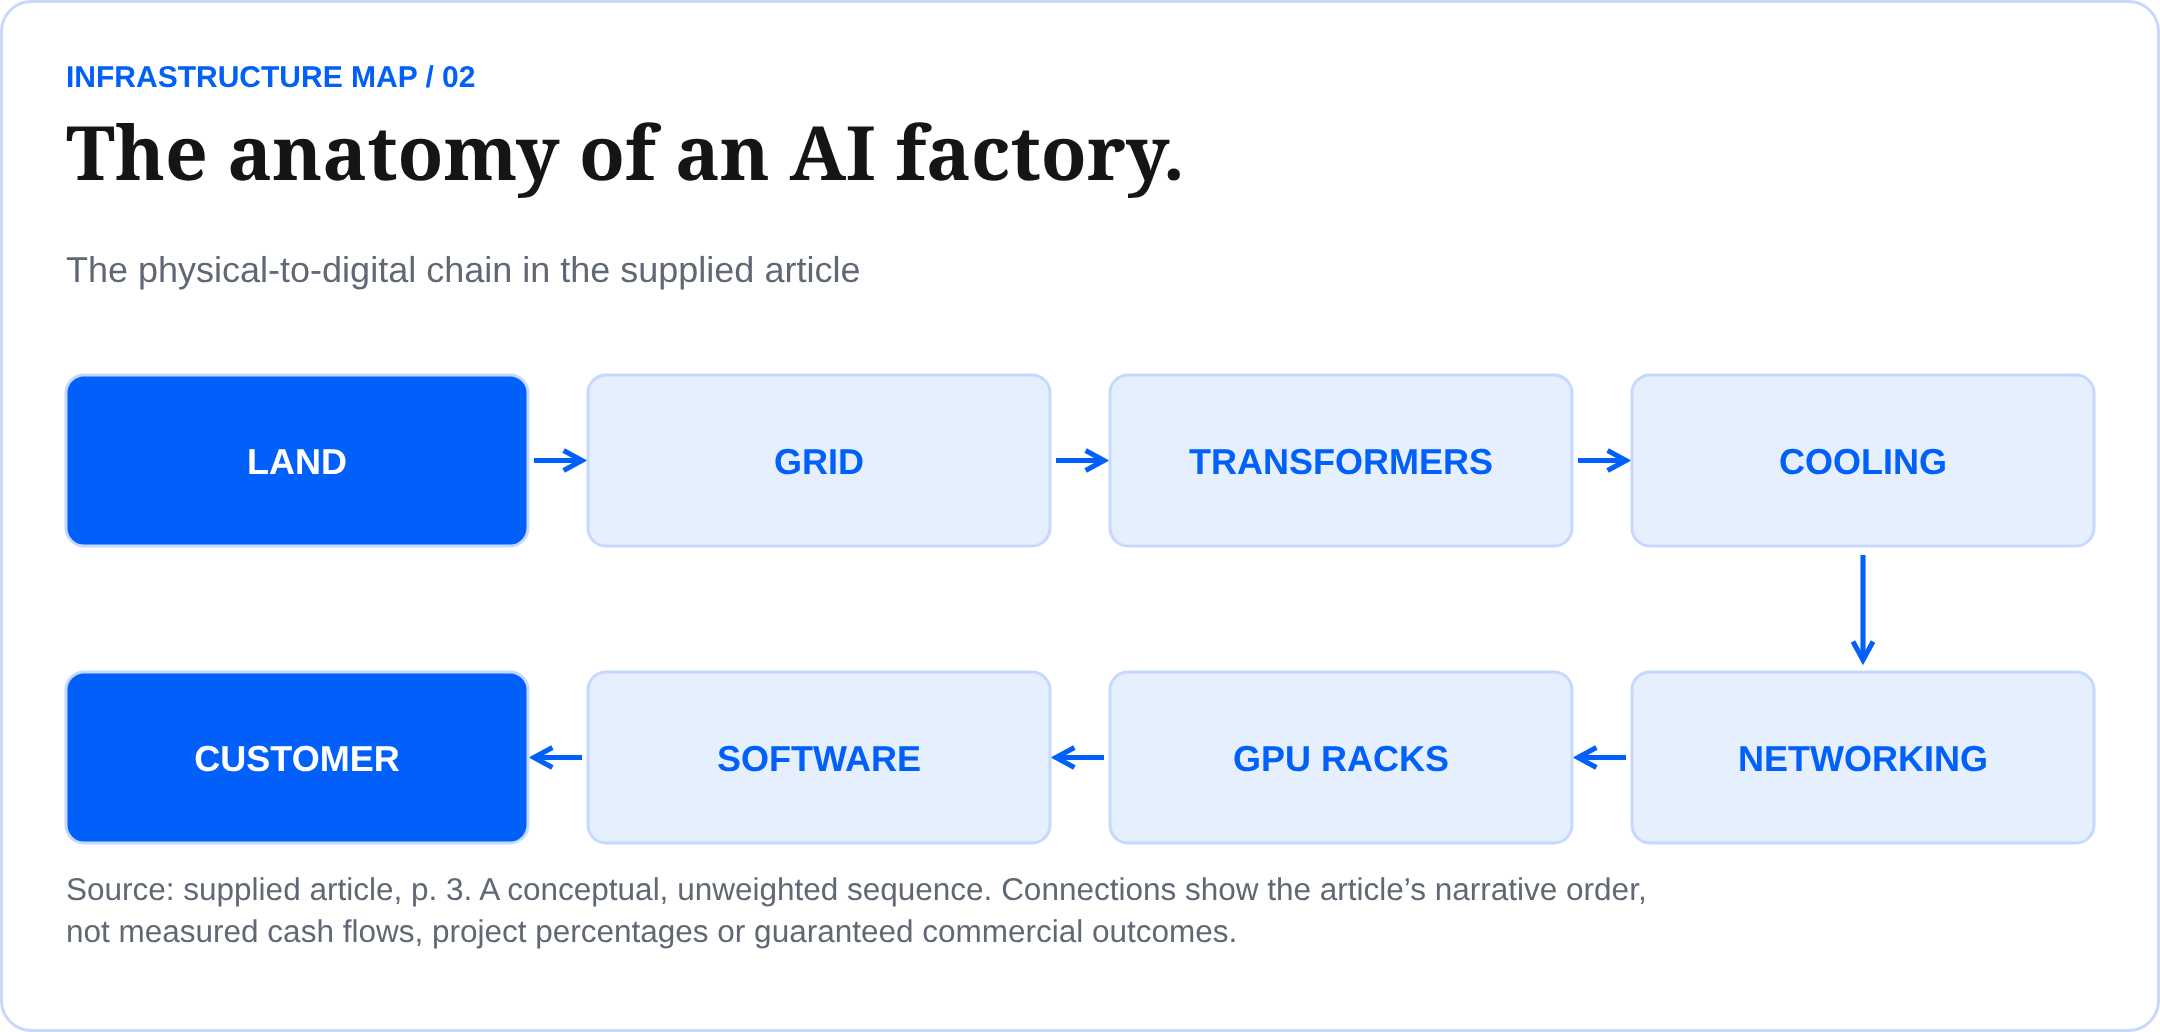
THE ANATOMY OF AN AI FACTORY
Sources: OpenAI (Stargate/Oracle); Applied Digital FY2026 10-K and Oct. 2, 2026 operating update.
03 / FOLLOW THE CHIP TWO MILLION GPUs |  |
The AI chip is not one product. It is a supply chain - design, wafers, packaging, HBM memory, networking and power delivery.
NVIDIA Compute design | Accelerators turn AI models into workloads. |
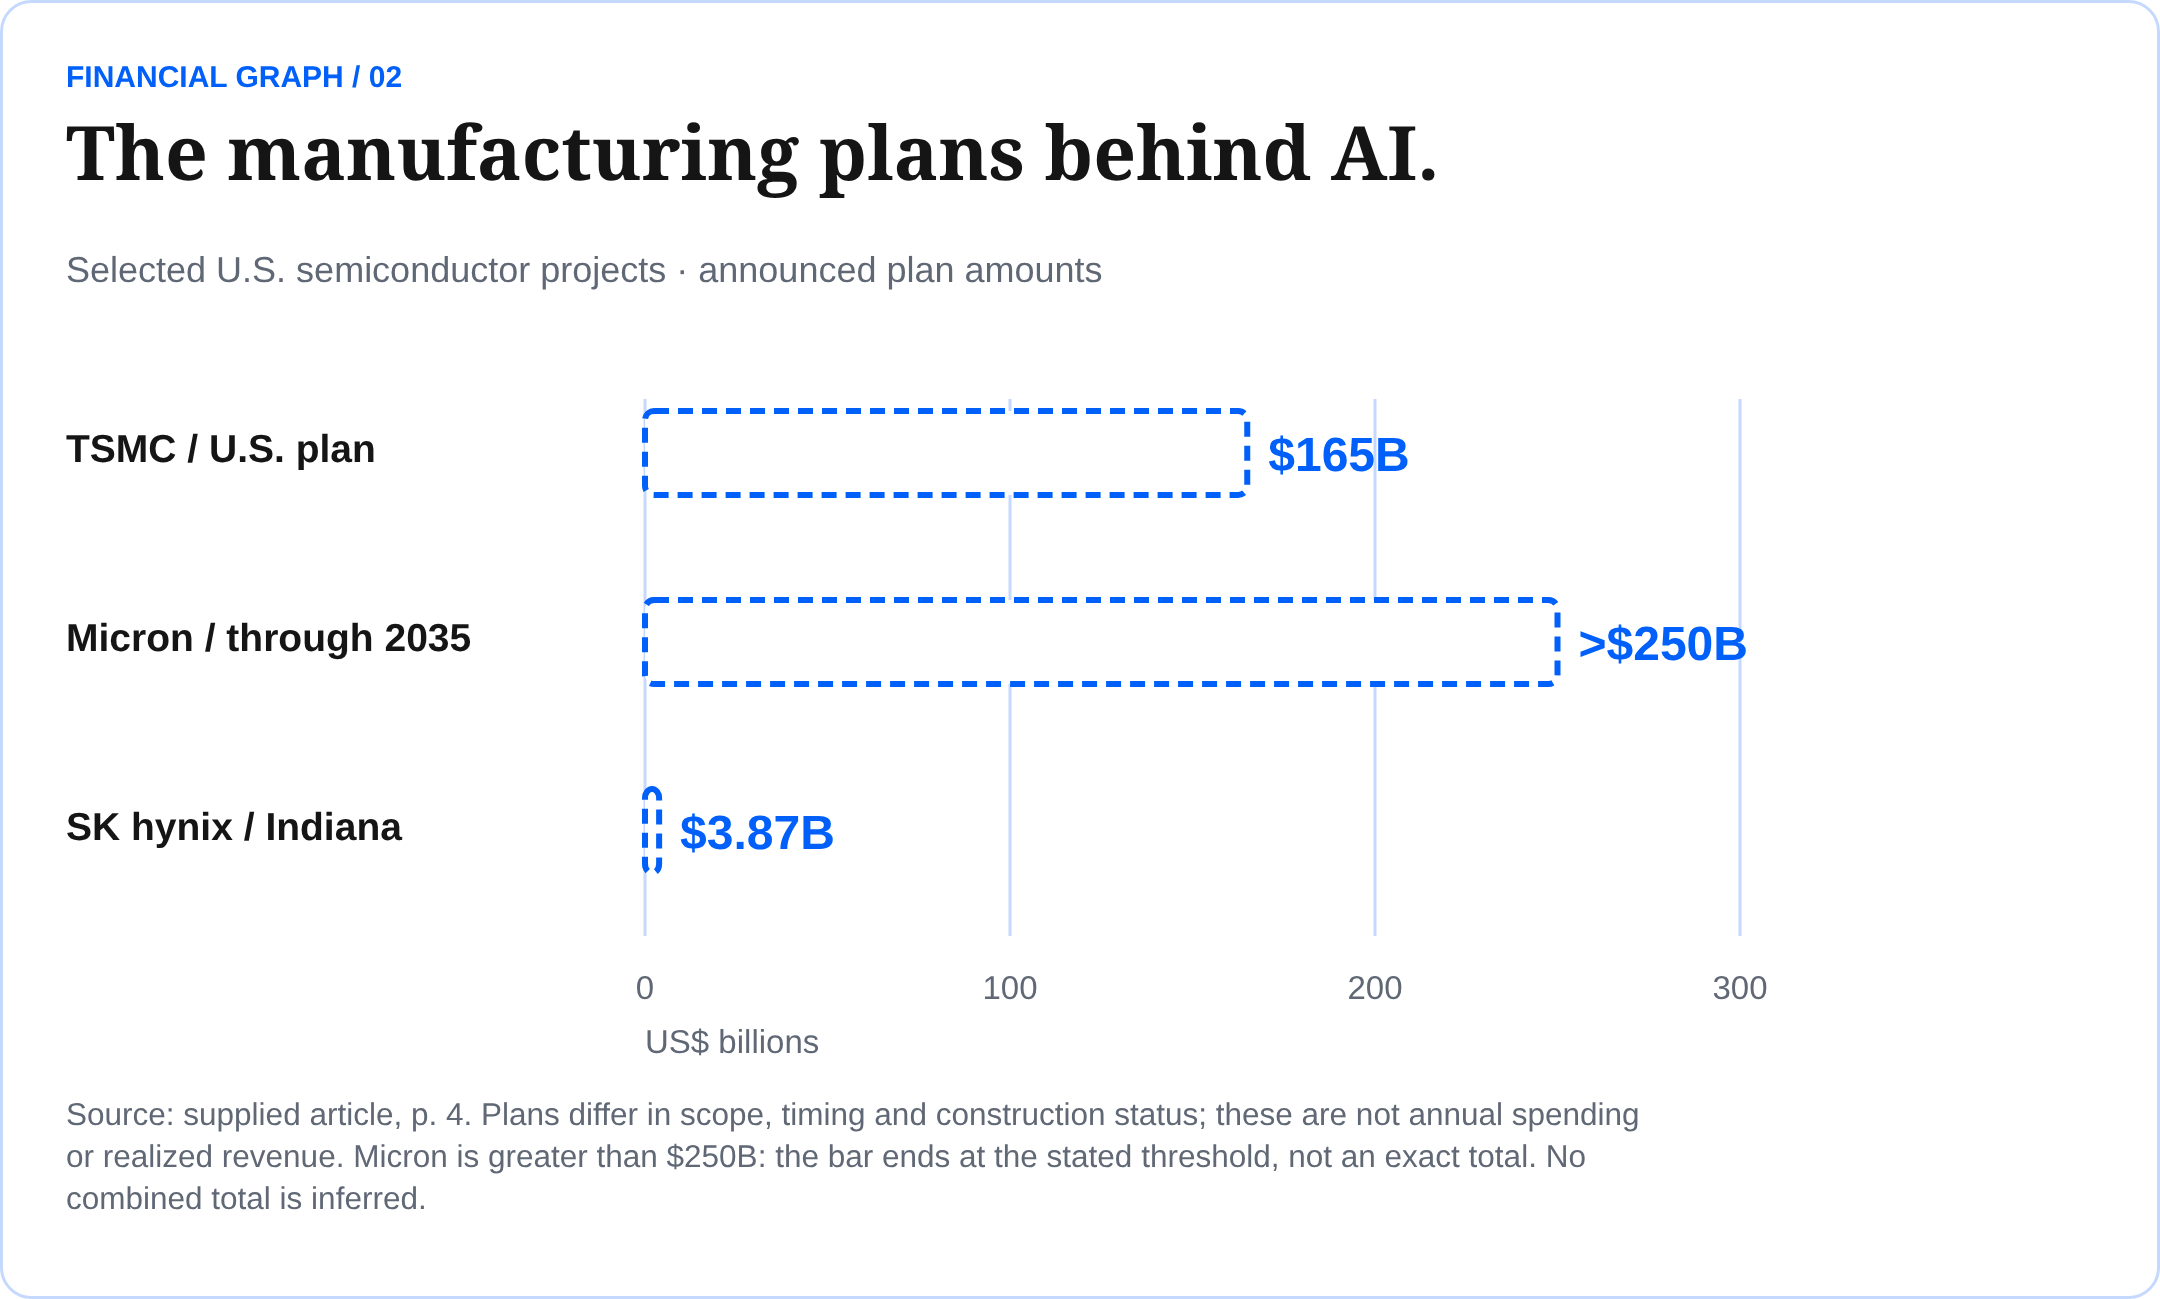
TSMC $165B U.S. plan | Six planned advanced wafer fabs, two advanced-packaging fabs and R&D; first Arizona fab entered high-volume production in 4Q24. |
MICRON >$250B U.S. plan | U.S. manufacturing/R&D through 2035; first concrete poured at Clay, NY in July 2026; Idaho DRAM output scheduled for 2027. |
SK HYNIX $3.87B Indiana | Advanced packaging and R&D facility for next-generation HBM used in AI systems. |
BROADCOM Networking + custom silicon | The connective tissue between thousands of accelerators. |
DESIGN → WAFER → PACKAGING → HBM → SERVER → NETWORK → DATA CENTER |
Sources: TSMC; Micron; SK hynix official project announcements.
|
04 / FOLLOW THE MEGAWATT WHAT IF AI DOESN’T |  |
Power is becoming strategic infrastructure. The AI factory only exists when the rack can be energized.
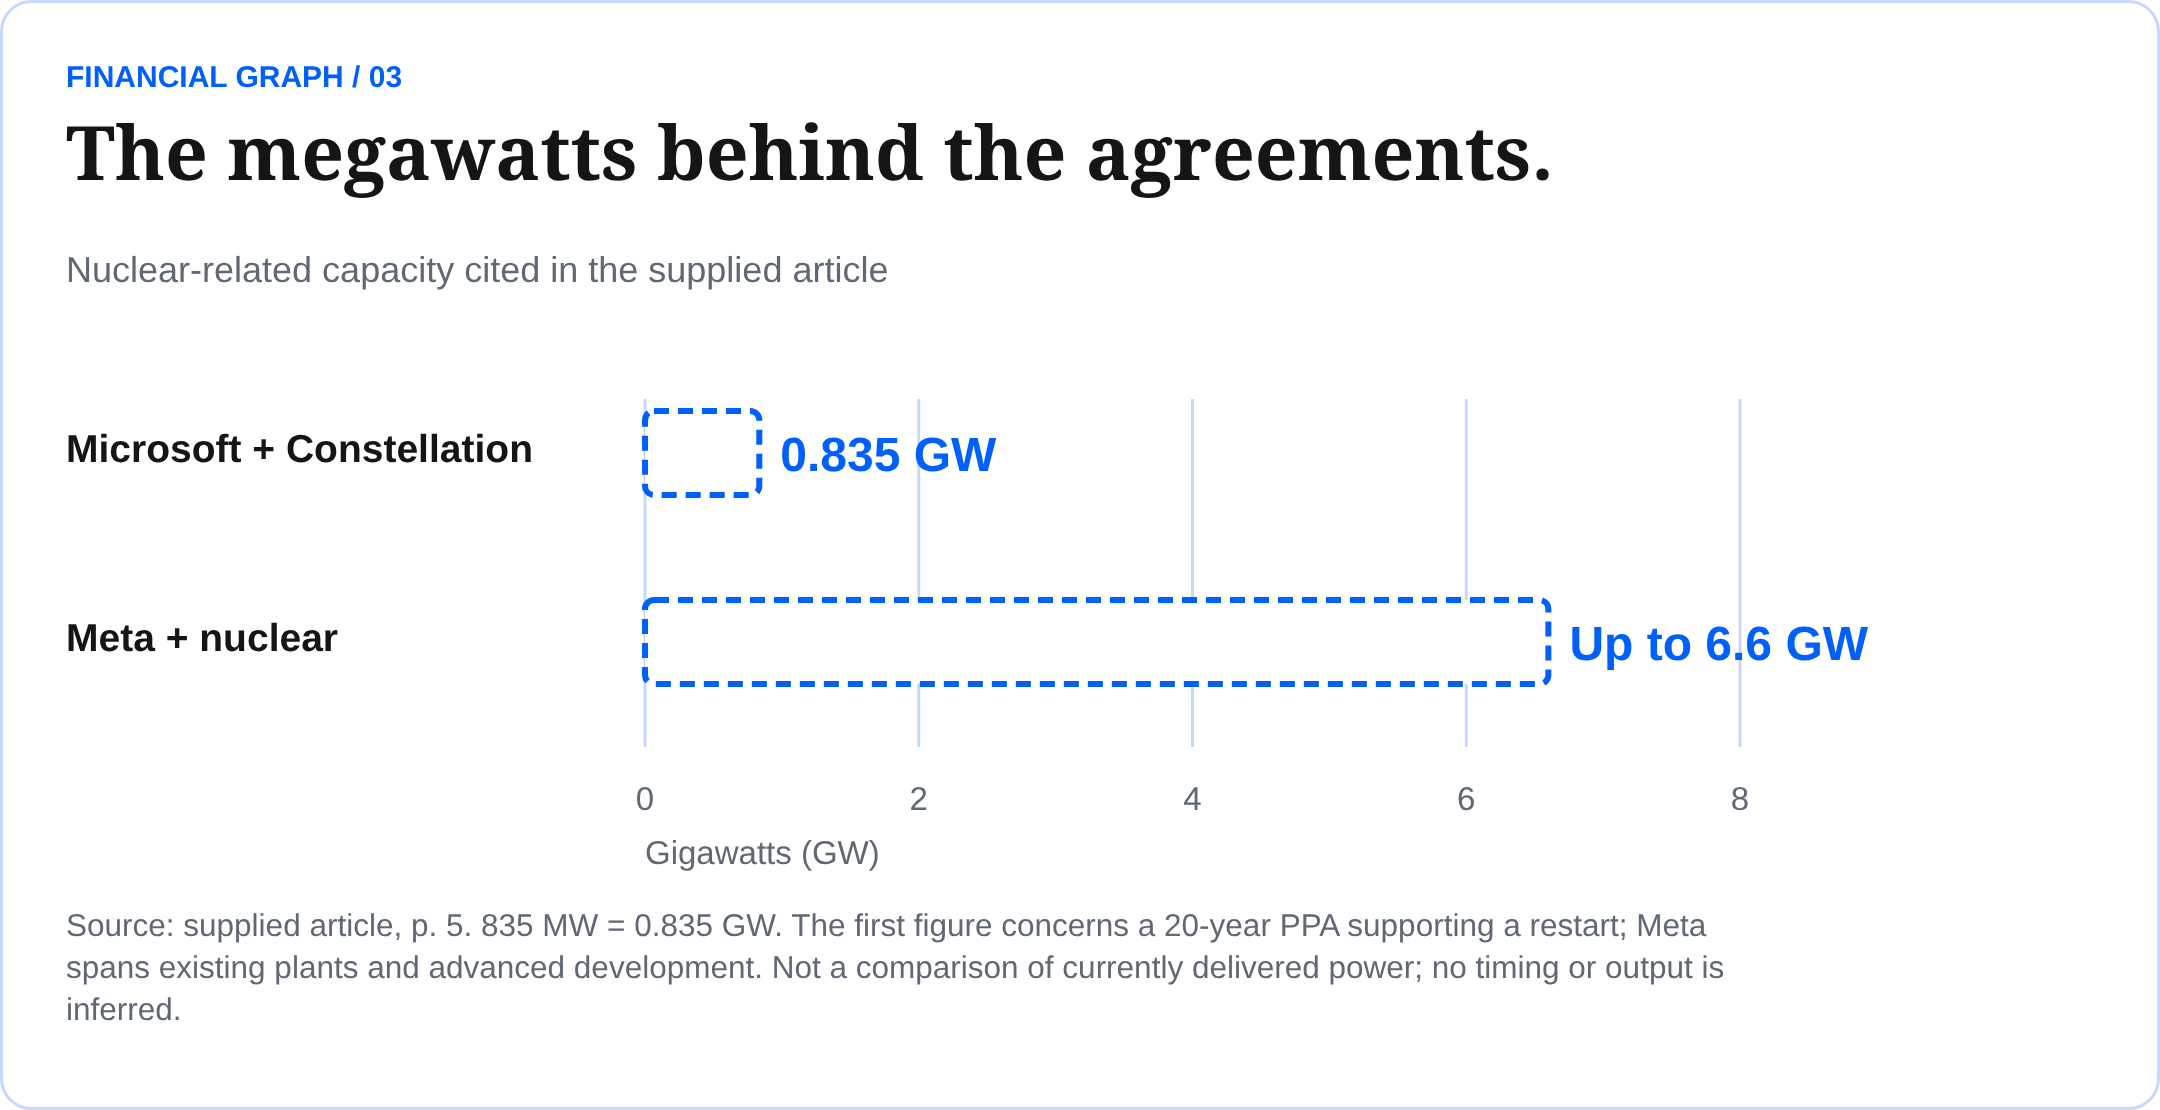
MICROSOFT + CONSTELLATION 835 MW 20-year PPA supporting the restart of Crane Clean Energy Center. | META + NUCLEAR UP TO 6.6 GW Agreements spanning existing nuclear plants and advanced nuclear development. | |
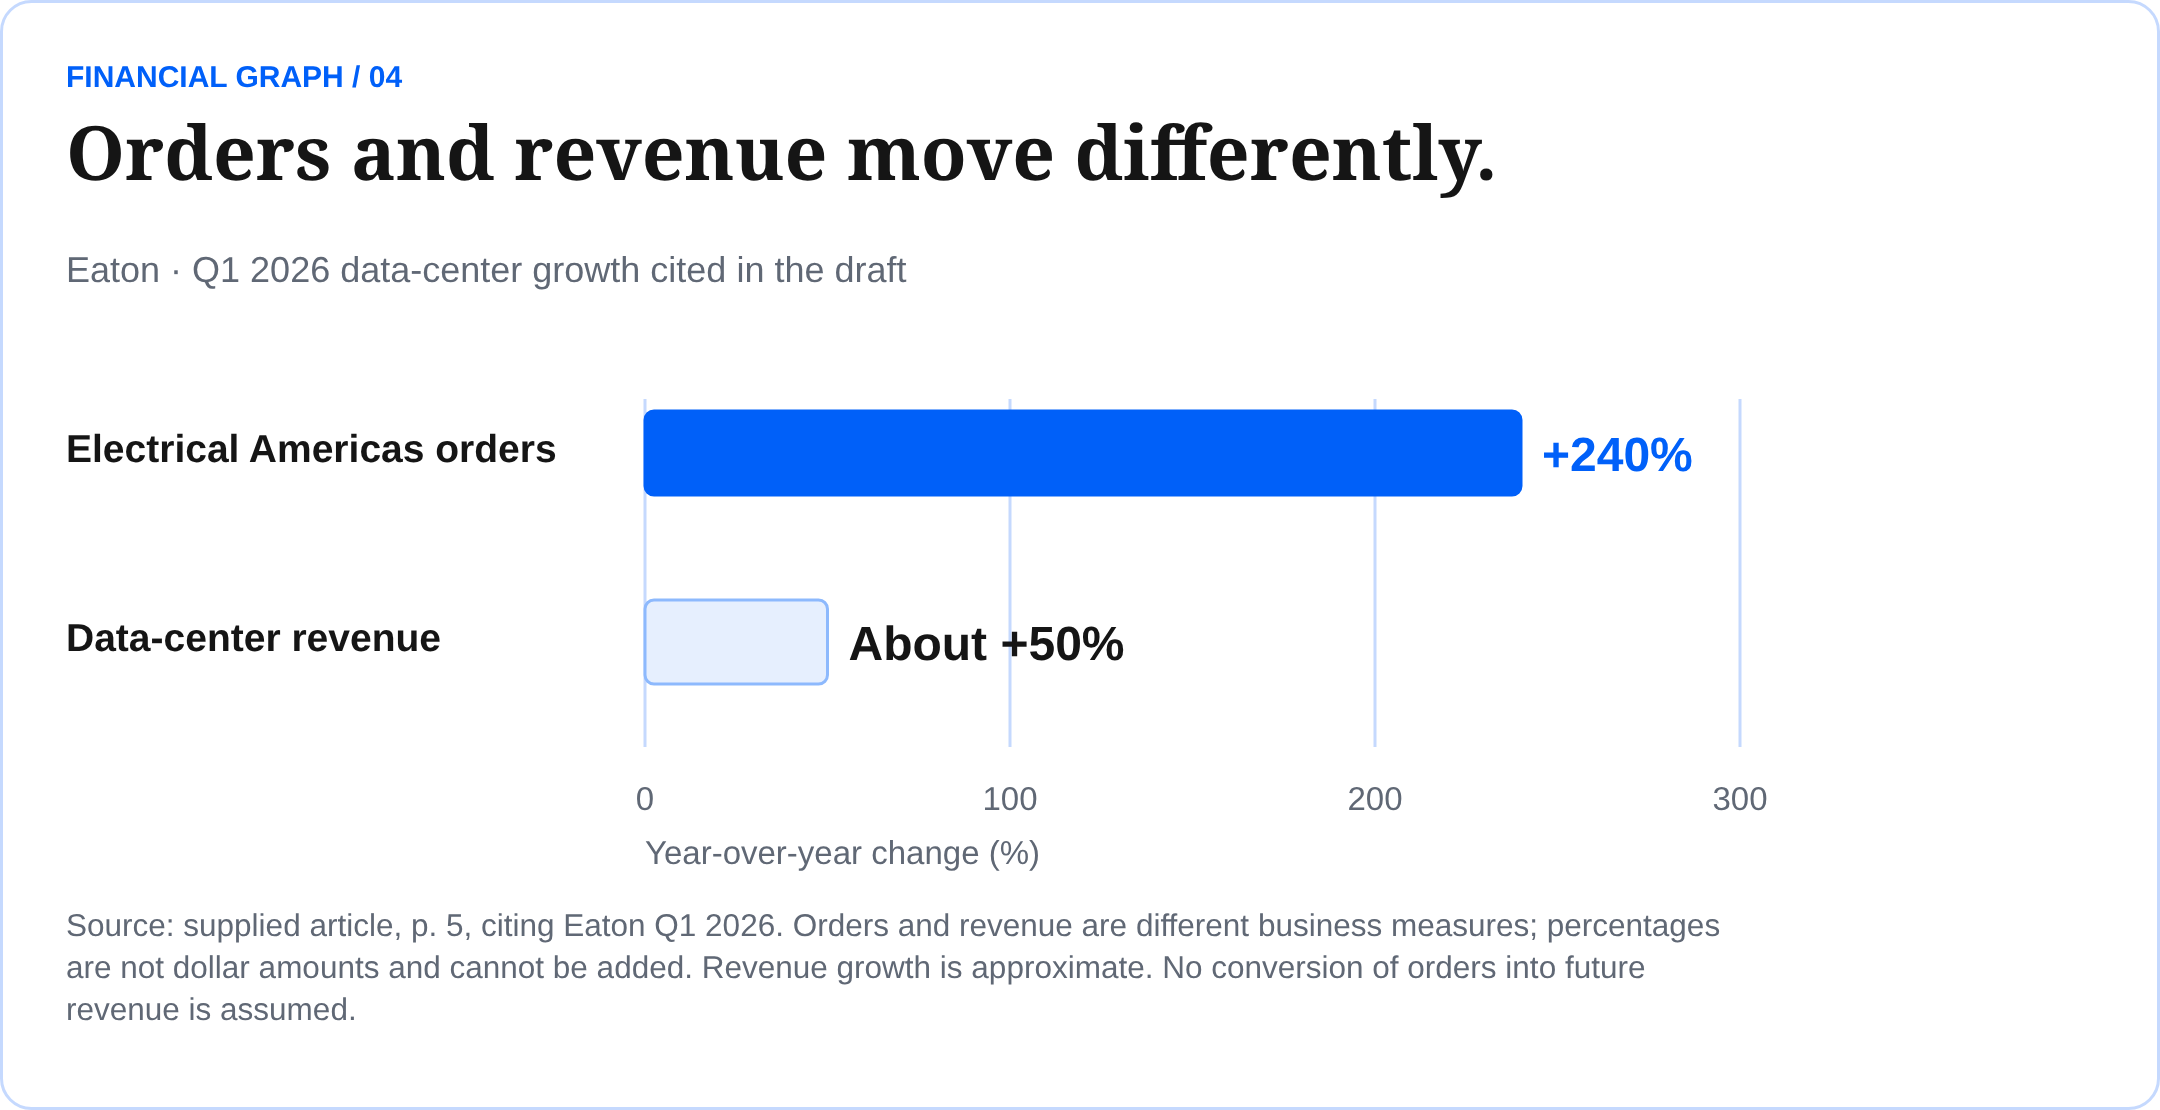
GE VERNOVA $2.4B Q1 2026 Electrification equipment orders supporting data centers - more than all of 2025. | EATON +240% Q1 2026 Electrical Americas data-center orders versus Q1 2025; data-center revenue up about 50%. |
THE BOTTLENECK BEHIND THE BOTTLENECK Transformers. Switchgear. Turbines. Cooling. Grid connections. Electricity. |
Sources: Constellation; Meta; GE Vernova Q1 2026; Eaton Q1 2026.
05 / WHERE WE COME BACK TO THE INVESTOR AND HERE IS WHERE |  |
We followed the money, the concrete and the megawatt. Now we look for companies positioned around the technologies AI infrastructure still has to buy.
SPECTRAL CAPITAL / FCCN
THE EMERGING TECHNOLOGY + IP CASE
Spectral sits in a different category from NVIDIA, Eaton or GE Vernova. It is earlier and less proven - but that is exactly why it belongs at the front of our research list. Its disclosed IP portfolio points directly at several problems this edition has identified.
HYBRID + QUANTUM Task allocation, optimization and error-mitigation methods. | DECENTRALIZED COMPUTE Software orchestration across distributed, decentralized and cloud environments. | |
DATA + SECURITY Cryptography, authentication, integrity, synthetic data and probabilistic modeling. | HARDWARE-ADJACENT Materials and physics-informed computational models remain exploratory. |
THE OPEN QUESTION: CAN SPECTRAL HELP MAKE COMPUTE MORE EFFICIENT - AND THEREFORE EASIER TO POWER? |
Spectral describes 40 utility patent applications plus trade secrets/know-how in its Sept. 28 S-1/A. Earlier filings described a broader innovation pipeline. The next question is commercialization: customers, licensing and deployment - and whether energy efficiency or electrification becomes another part of the Spectral story.
Sources: Spectral Capital S-1/A, Sept. 28, 2026; 2025 Form 10-K. Patent applications are not issued patents and commercialization is not assured.
06 / WHERE WE WOULD INVEST OUR RESEARCH FCCN FIRST. |  |
Spectral Capital is our emerging technology case. Around it sits the established physical AI chain - compute, chips, memory, networking, cooling, electrical infrastructure and power.
FCCN | SPECTRAL CAPITAL AI + quantum + decentralized compute OUR EMERGING TECHNOLOGY CASE - watch commercialization. |
NVDA | NVIDIA Compute AI accelerators and platform. |
AVGO | BROADCOM Networking + custom silicon Connects and scales AI clusters. |
TSM | TSMC Chip manufacturing Turns advanced designs into wafers. |
MU | MICRON Memory / HBM Memory bandwidth is critical to AI systems. |
VRT | VERTIV Cooling + power Keeps dense AI racks operating. |
ETN | EATON Electrical infrastructure Moves and manages power inside facilities. |
GEV / CEG | GE VERNOVA / CONSTELLATION Generation + grid AI cannot scale without reliable megawatts. |
APLD | APPLIED DIGITAL Data-center capacity Physical campuses built for AI/HPC demand. |
FCCN IS NOT THE SAME BET AS NVIDIA OR EATON. IT IS THE EARLY TECHNOLOGY LAYER WE WANT TO WATCH CLOSELY. |
Sources: Company filings and investor relations. Research list is editorial analysis, not a guarantee of performance.
07 / THE INVESTOR CALL VIEW SOMEBODY OUTSIDE |  |
The answer is bigger than any single hyperscaler. AI is becoming part of the base infrastructure of the future economy.
SO WHO PAYS?
THE FUTURE WILL.
Banks. Hospitals. Factories. Transport. Energy systems. Governments. Software. Science. Consumers.
AI does not need one customer to pay for the revolution. The economy it is helping to build becomes the customer.
THE IMPORTANT DISTINCTION The future of AI can be enormous while individual AI investments can still fail. |
That is why we are not simply following AI stocks.
WE’RE FOLLOWING WHAT AI HAS TO BUY.
Compute / Chips / Memory / Networking / Data centers / Cooling / Electrical infrastructure / Power
FOLLOW THE MONEY. FOLLOW THE CONCRETE. FOLLOW THE MEGAWATT. |
Sources: Microsoft FY2026: $214.4B cloud revenue; nearly 90% from customers outside frontier-model companies.
READY TO DO YOUR OWN RESEARCH? If you decide to trade, use a regulated broker appropriate to your jurisdiction and independently research each investment. The links below are provided for convenience, not as broker endorsements. Availability of individual securities varies by platform and jurisdiction.
Tiger Trade link opens Tiger Brokers' official regional site; availability and regulation depend on jurisdiction. |
|
Production note. The supplied October 5, 2026 article has been reformatted, not independently verified or updated. Graphs use only its figures and preserve project status, time horizons and qualifiers. The $100B headline is not a measured allocation. Patent applications are not issued patents; commercialization is not assured. This is editorial research, not personalized investment advice.
 Research that matters. Performance you can measure. Insight you can trust. www.theinvestorcall.com |  |
