
01 / APPLE'S COMEBACK / OCTOBER 26, 2026 Apple's comeback. |  |
Investors have funded the AI revolution.
Now they want to see the profits.
| Visit TheInvestorCall.com → |
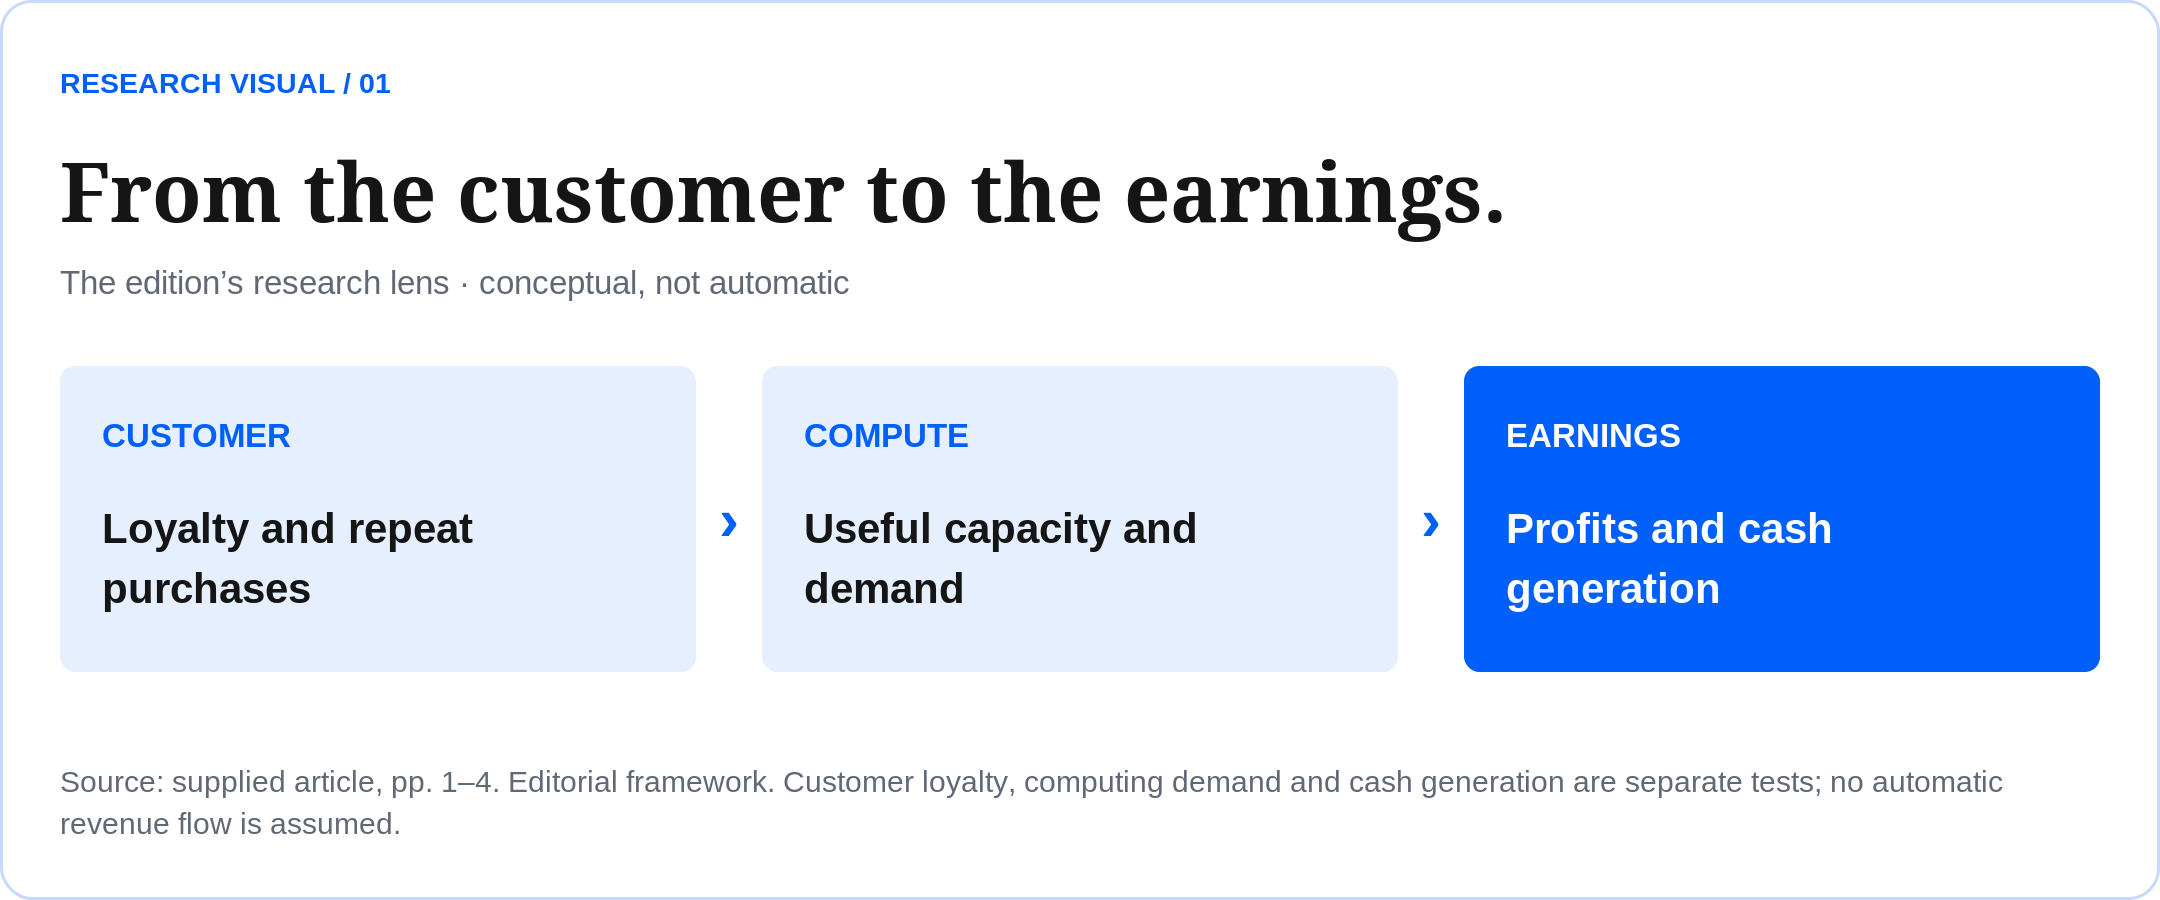
CUSTOMER LOYALTY / COMPUTING DEMAND / CASH GENERATION
A familiar name is back in the contest. Apple briefly overtook Nvidia as the world's most valuable public company on Friday, according to market reporting. Nvidia reclaimed the lead. The more useful story lies beneath the ranking.
Apple earns through devices and their surrounding services. Nvidia supplies the computing infrastructure behind the AI expansion. For investors, the question is how much future earning power each share price already assumes.
Microsoft reports on October 28; Amazon follows on October 29. Their results will offer fresh evidence about customer demand, investment bills and the profits supporting the next stage of technology growth.
We examine four established platforms, then turn to Spectral Capital: an earlier-stage technology execution story with a telecom operating base. Five investment ideas, assessed through the same lens: what can the business earn?
| AAPL | NVDA | MSFT | AMZN | FCCN |
Research as of October 26, 2026, before the U.S. regular session. All dollar figures are U.S. dollars. Reported periods differ; company statements and our editorial assessments are distinguished.
02 / APPLE / NASDAQ: AAPL The customer stays. |  |
An installed base becomes valuable when the relationship continues through upgrades, services and repeat purchases.
$109.4B Fiscal Q3 2026 revenue · +16% YoY | $2.02 Diluted EPS · includes $0.11 benefit | 50.1% Gross margin · includes tariff refunds |
A relationship with duration.
Apple reported record June-quarter Services revenue and a record active device base. These facts support the commercial question: how effectively can a business serve the same customer over many years?
An ecosystem can create opportunities across a customer's devices, storage and subscriptions. Our thesis is that the relationship matters most when continued use supports recurring spending and repeatable profitability.
AI may strengthen that relationship. Its investment value still depends on useful products and customers' willingness to pay.
Our investment assessment.
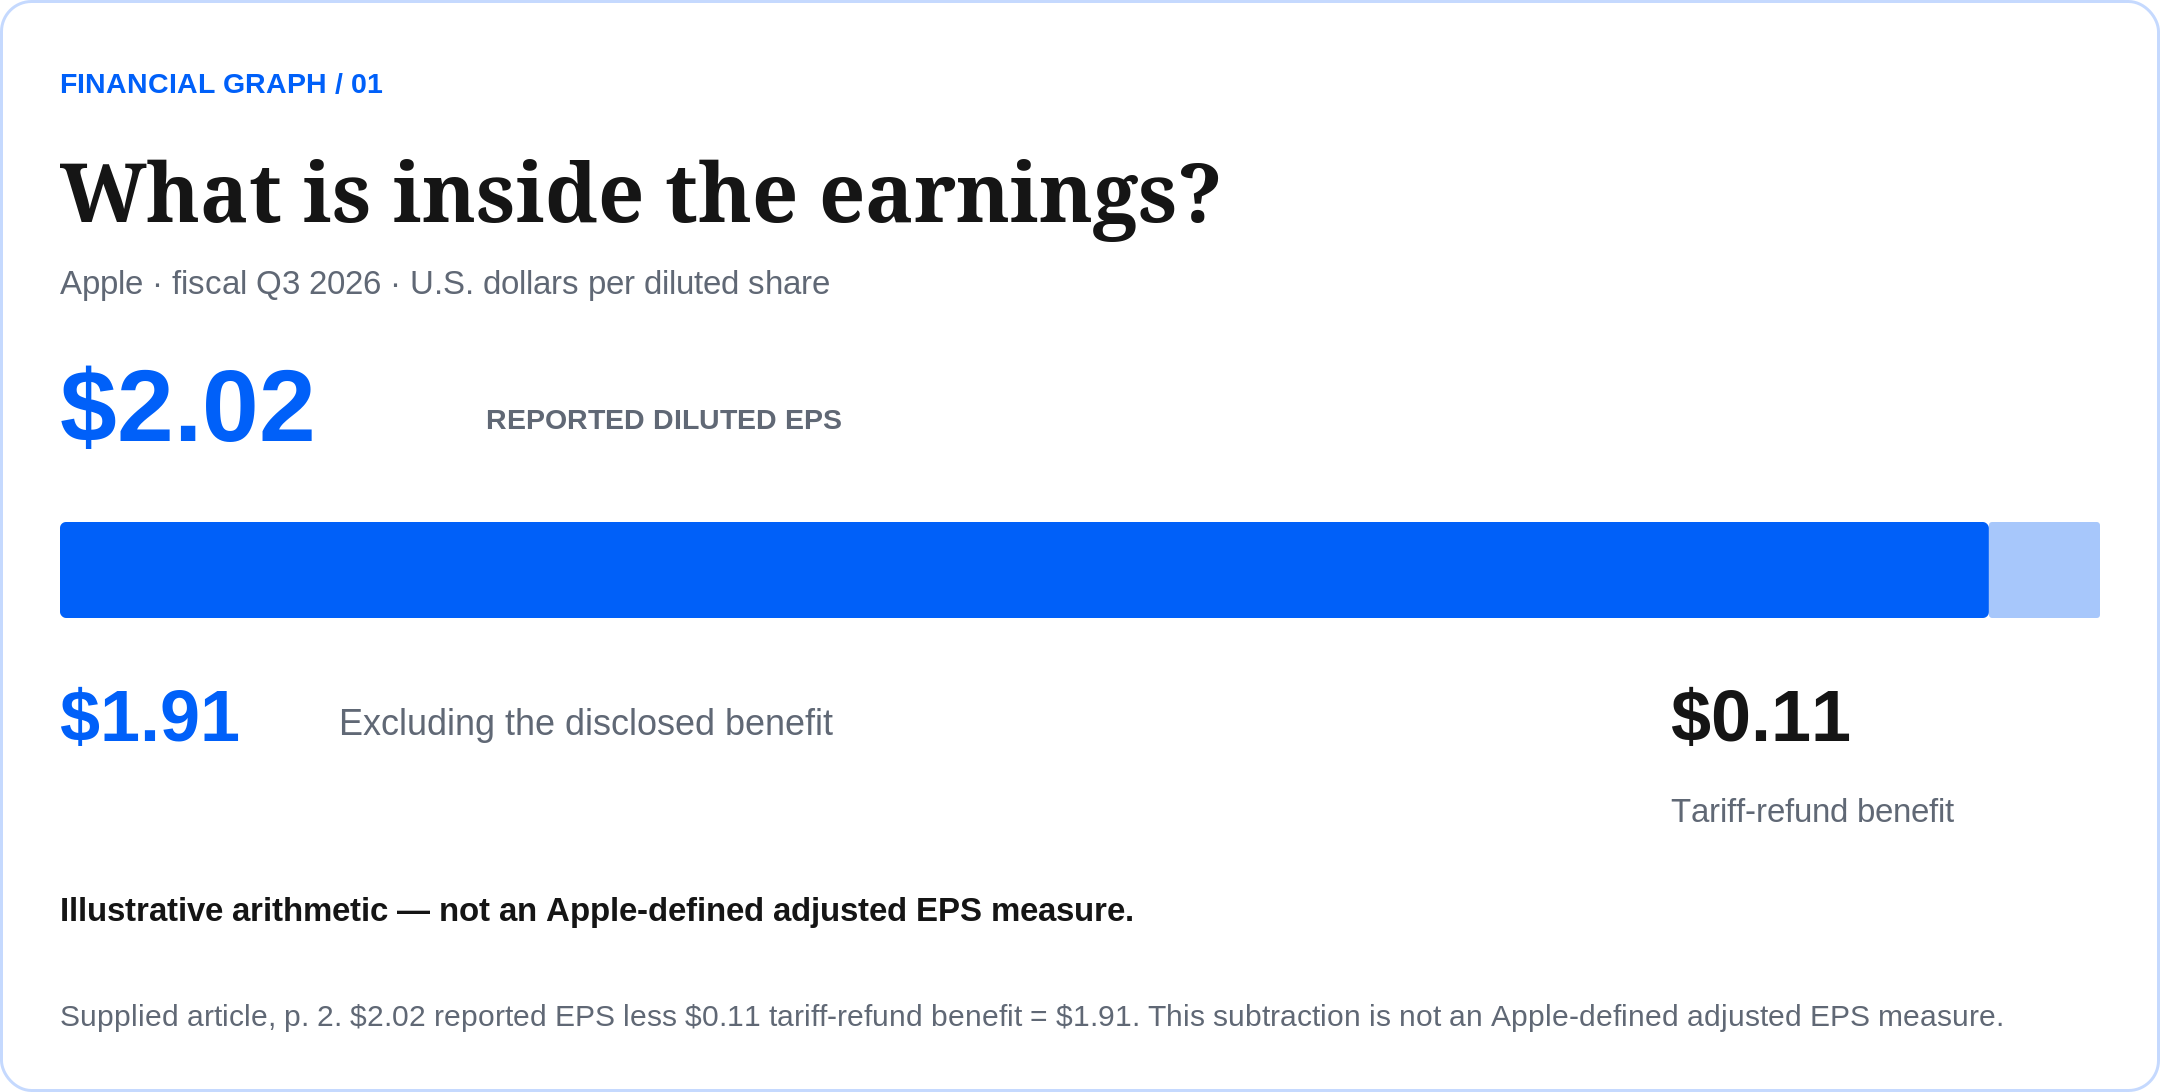
Revenue rose 16% and diluted EPS rose 29% in the quarter ended June 27. Tariff refunds contributed about two percentage points to gross margin and $0.11 to EPS; those benefits should be separated from repeatable performance.
Priority research for an established earnings position. Consider staged accumulation when a conservative view of sustainable earnings supports the purchase price.
A rising market value demonstrates investor interest. The ownership decision requires an estimate of what the business can earn per share over time.
Apple fiscal Q3 2026 ended June 27. Company-reported results; the EPS subtraction above is our calculation. Editorial stance is conditional on valuation and continued operating progress.
03 / NVIDIA / NASDAQ: NVDA Your customer's spending. |  |
Nvidia makes the infrastructure cycle visible. Its customers must make the economics of using that infrastructure visible next.
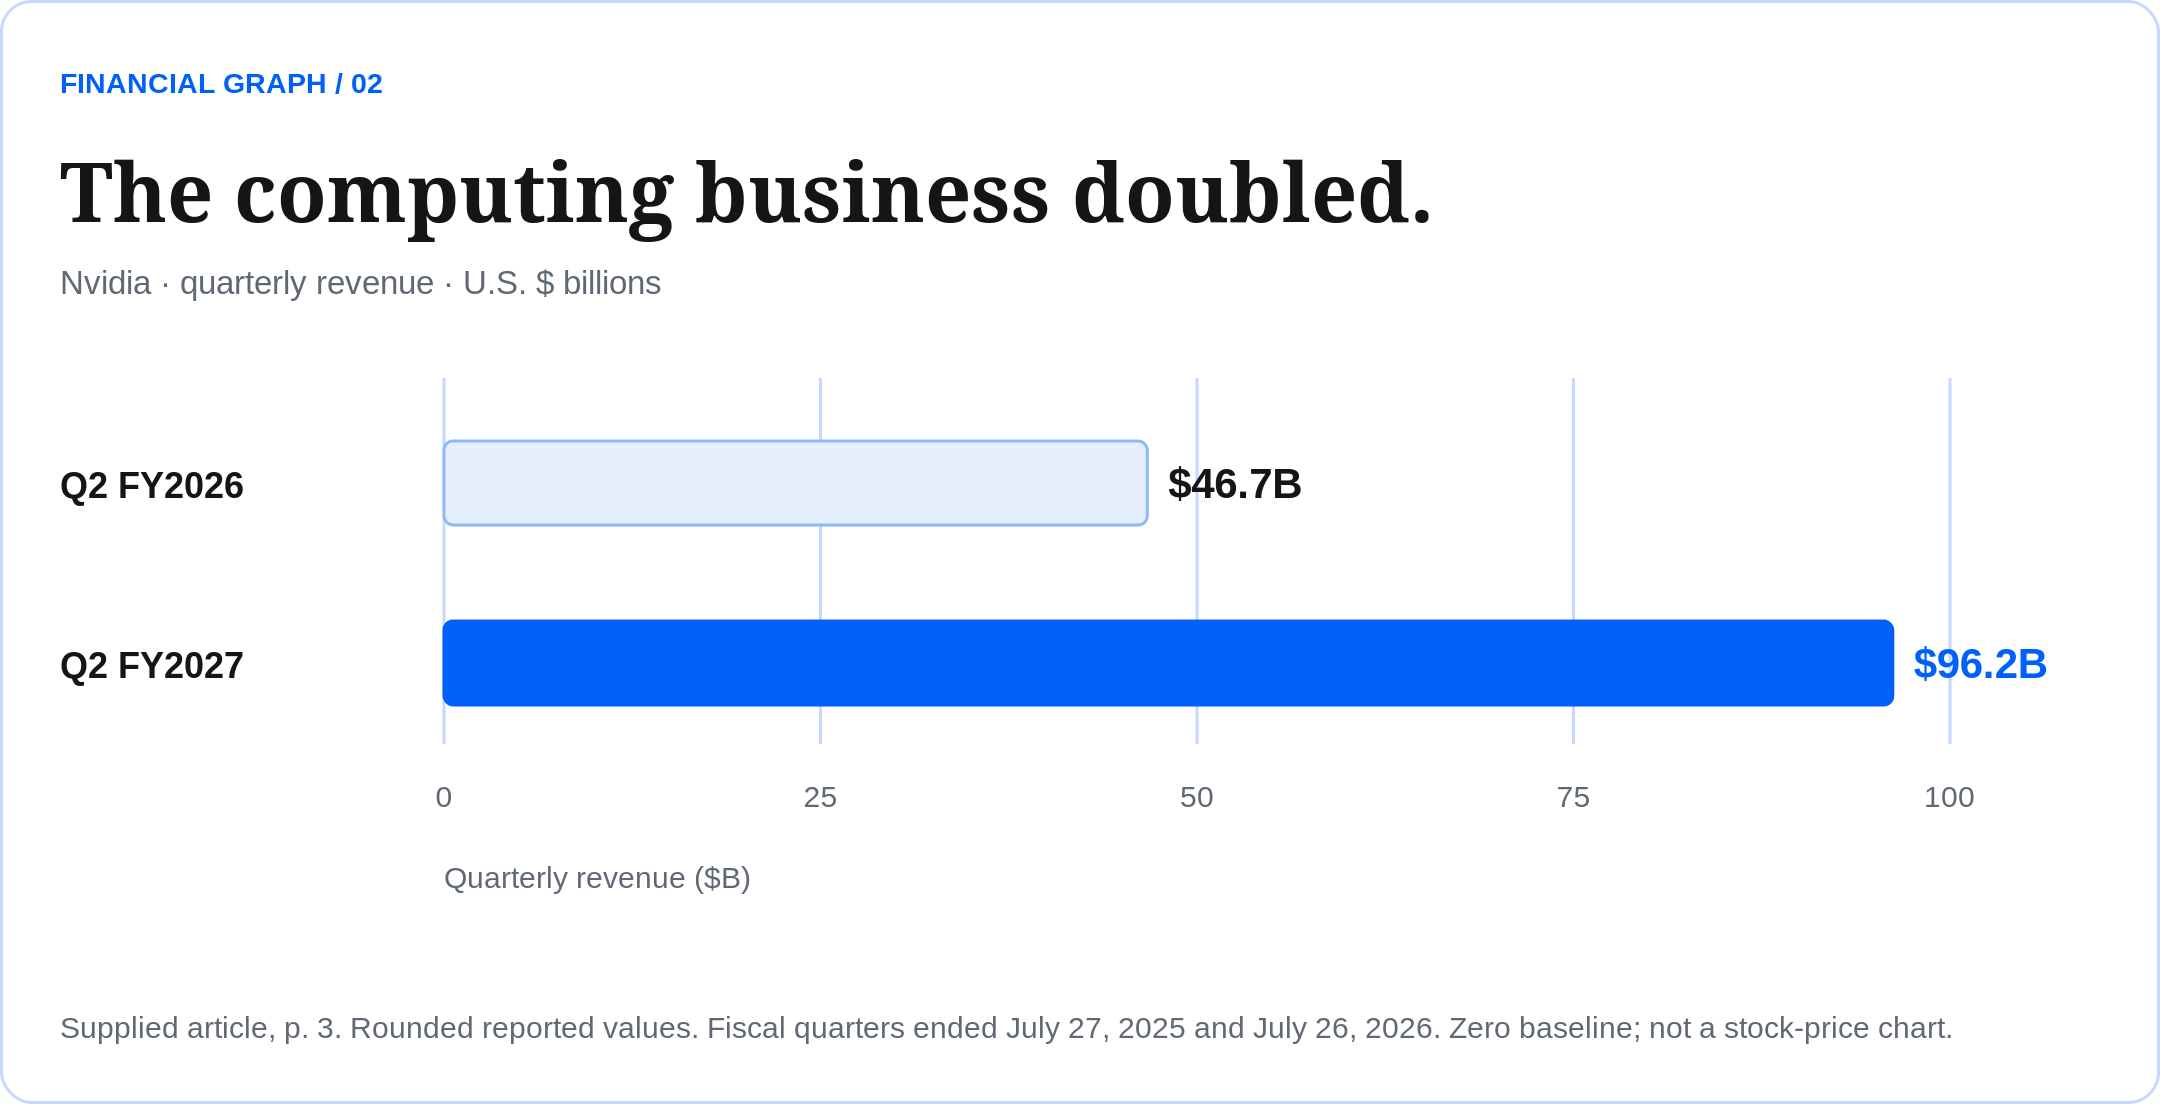
$96.2B Fiscal Q2 2027 revenue · +106% YoY | $89.0B Data Center revenue · +117% YoY | 75.0% Reported GAAP gross margin |
Orders are the first chapter.
Nvidia's fiscal second-quarter revenue doubled from a year earlier. Data Center sales accounted for about 92.5% of total revenue, calculated from the reported figures. The scale makes customer investment decisions central to the story.
A useful research chain follows the purchase into actual use: capacity comes online, customers run workloads, services earn revenue, and that revenue supports further investment.
Our interpretation: demand is most durable when customers earn satisfactory returns from the equipment they buy.
Keep the valuation disciplined.
Management guided to $108 billion of fiscal third-quarter revenue, plus or minus 2%, and a 74% GAAP gross margin, plus or minus 0.5 percentage points. These are forecasts, rather than completed results.
Growth position for valuation-led research. Favor an entry price that leaves room for slower growth and more normal margins than an optimistic case assumes.
Watch this week's cloud-company results for evidence about utilization, spending commitments and the commercial demand behind the infrastructure orders.
Nvidia fiscal Q2 2027 ended July 26, 2026. Data Center share is our calculation: $89.0B / $96.221B. Company guidance may differ from actual results; gross margin is not operating margin.
04 / MICROSOFT + AMAZON / MSFT + AMZN Build the capacity. |  |
Two established platforms. Two earnings reports this week. The same question: how effectively does investment become profitable customer demand?
MSFT / MICROSOFT
Microsoft reported $90.0 billion of revenue and $40.6 billion of operating income in the quarter ended June 30, both up 18%. It also reported more than 30 million paid Microsoft 365 Copilot seats.
The commercial attraction is distribution: an established software relationship creates opportunities to introduce additional paid services. Track adoption, retention and profitability together.
October 28: watch Azure demand, paid AI adoption, cloud margins and investment commitments. Revenue growth deserves more conviction when earnings and cash support it.
Our stance: first priority for enterprise-AI research. A potential core holding when sustainable earnings justify the valuation; new results should inform additions.
AMZN / AMAZON
Amazon's Q2 AWS revenue reached $42.2 billion; AWS operating income was $16.6 billion. Over the trailing twelve months, company-wide operating cash flow was $161.4 billion, while free cash flow was negative $7.6 billion.
Amazon attributed the cash-flow difference primarily to higher property and equipment investment for AI. Its headline net income also included substantial non-operating investment gains.
October 29: assess whether new capacity supports growth, operating profit and an eventual improvement in cash after investment. Separate investment gains from operating execution.
Our stance: constructive on the operating opportunity. Add selectively when cloud profitability and investment economics support the price paid.
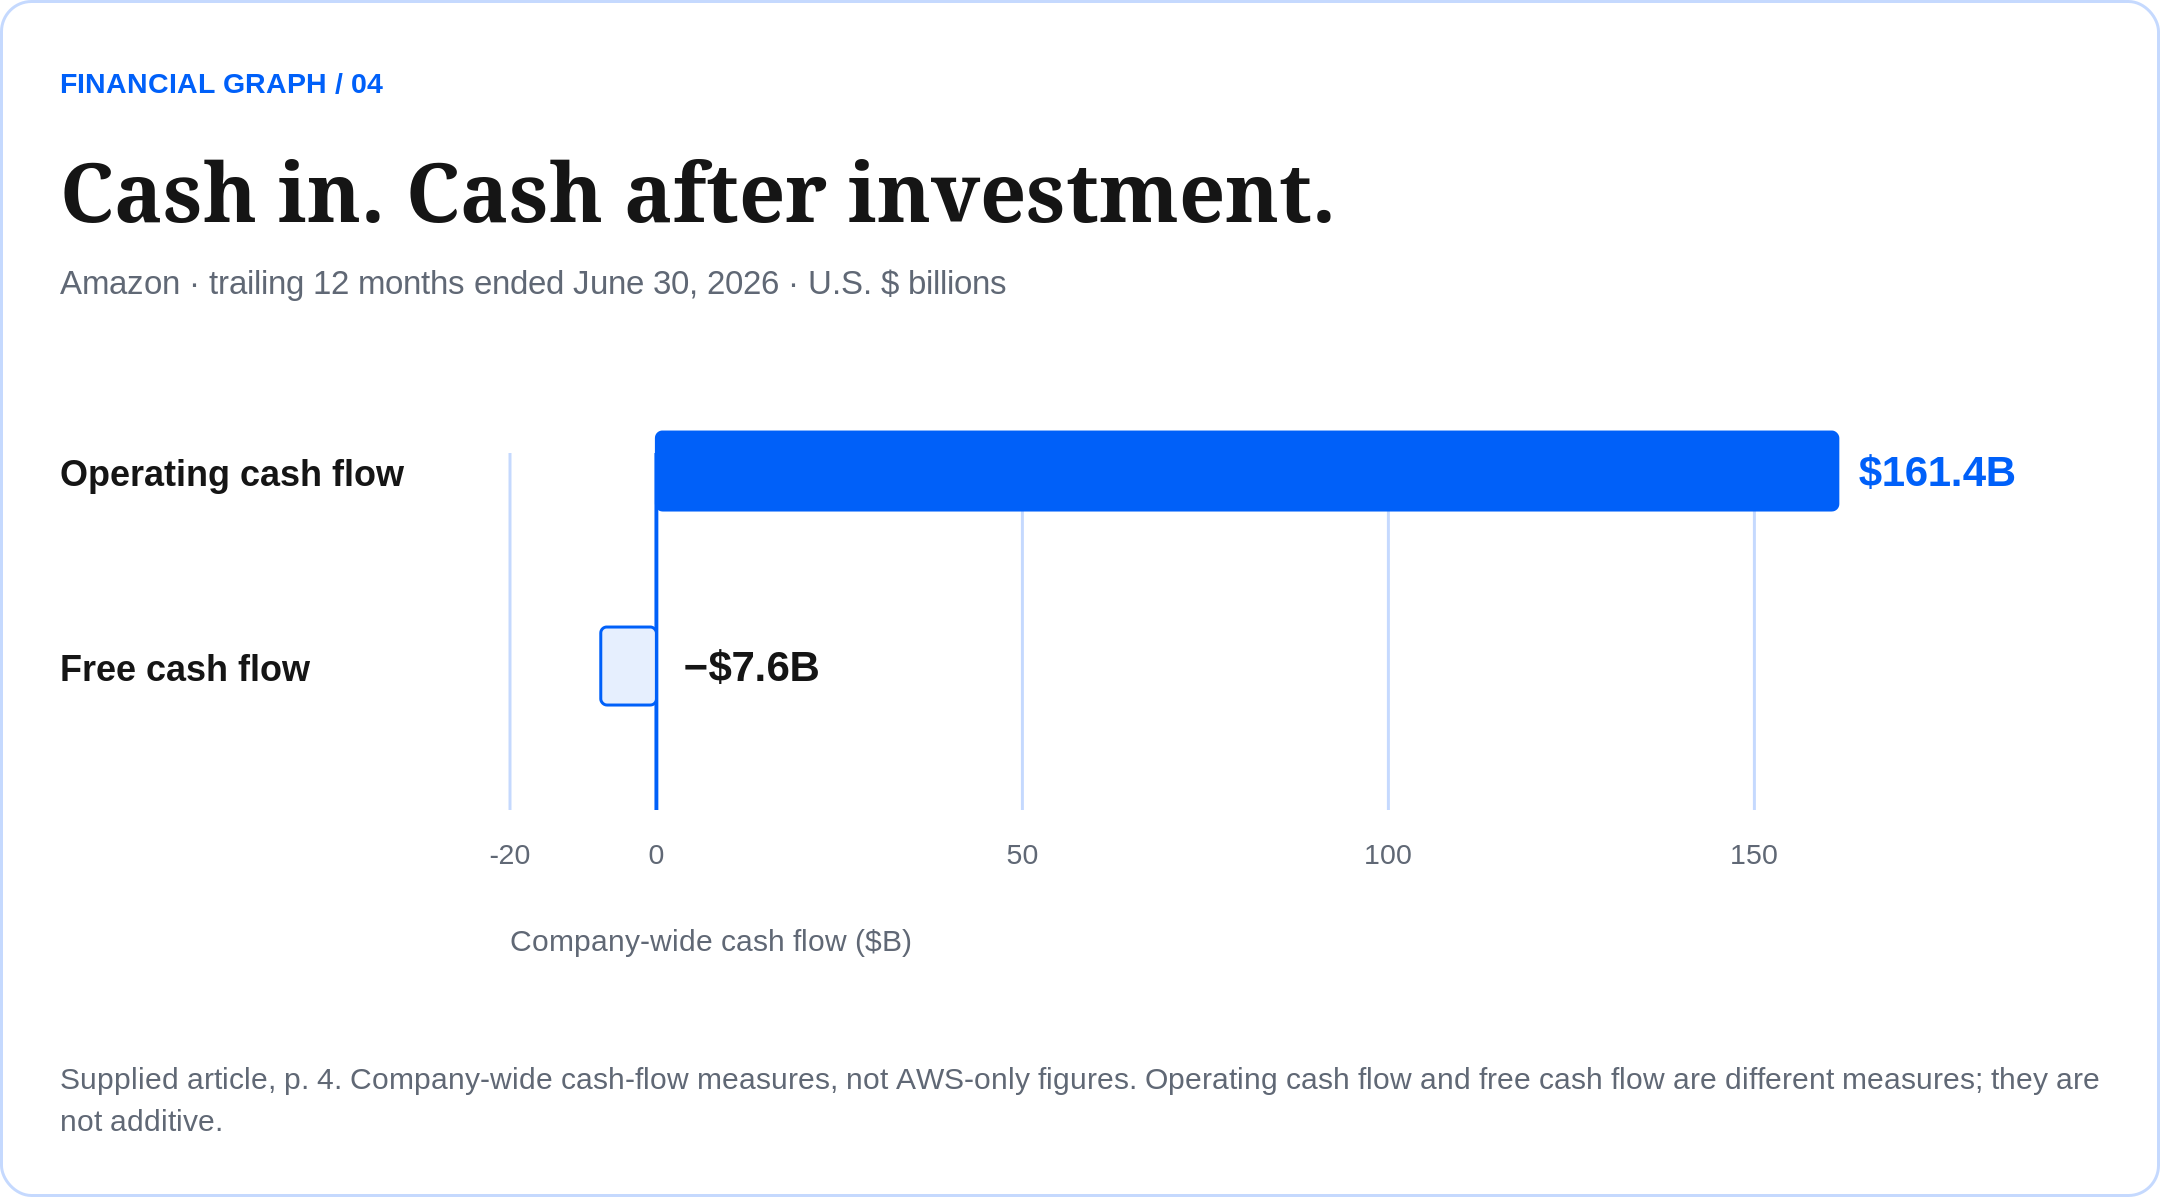
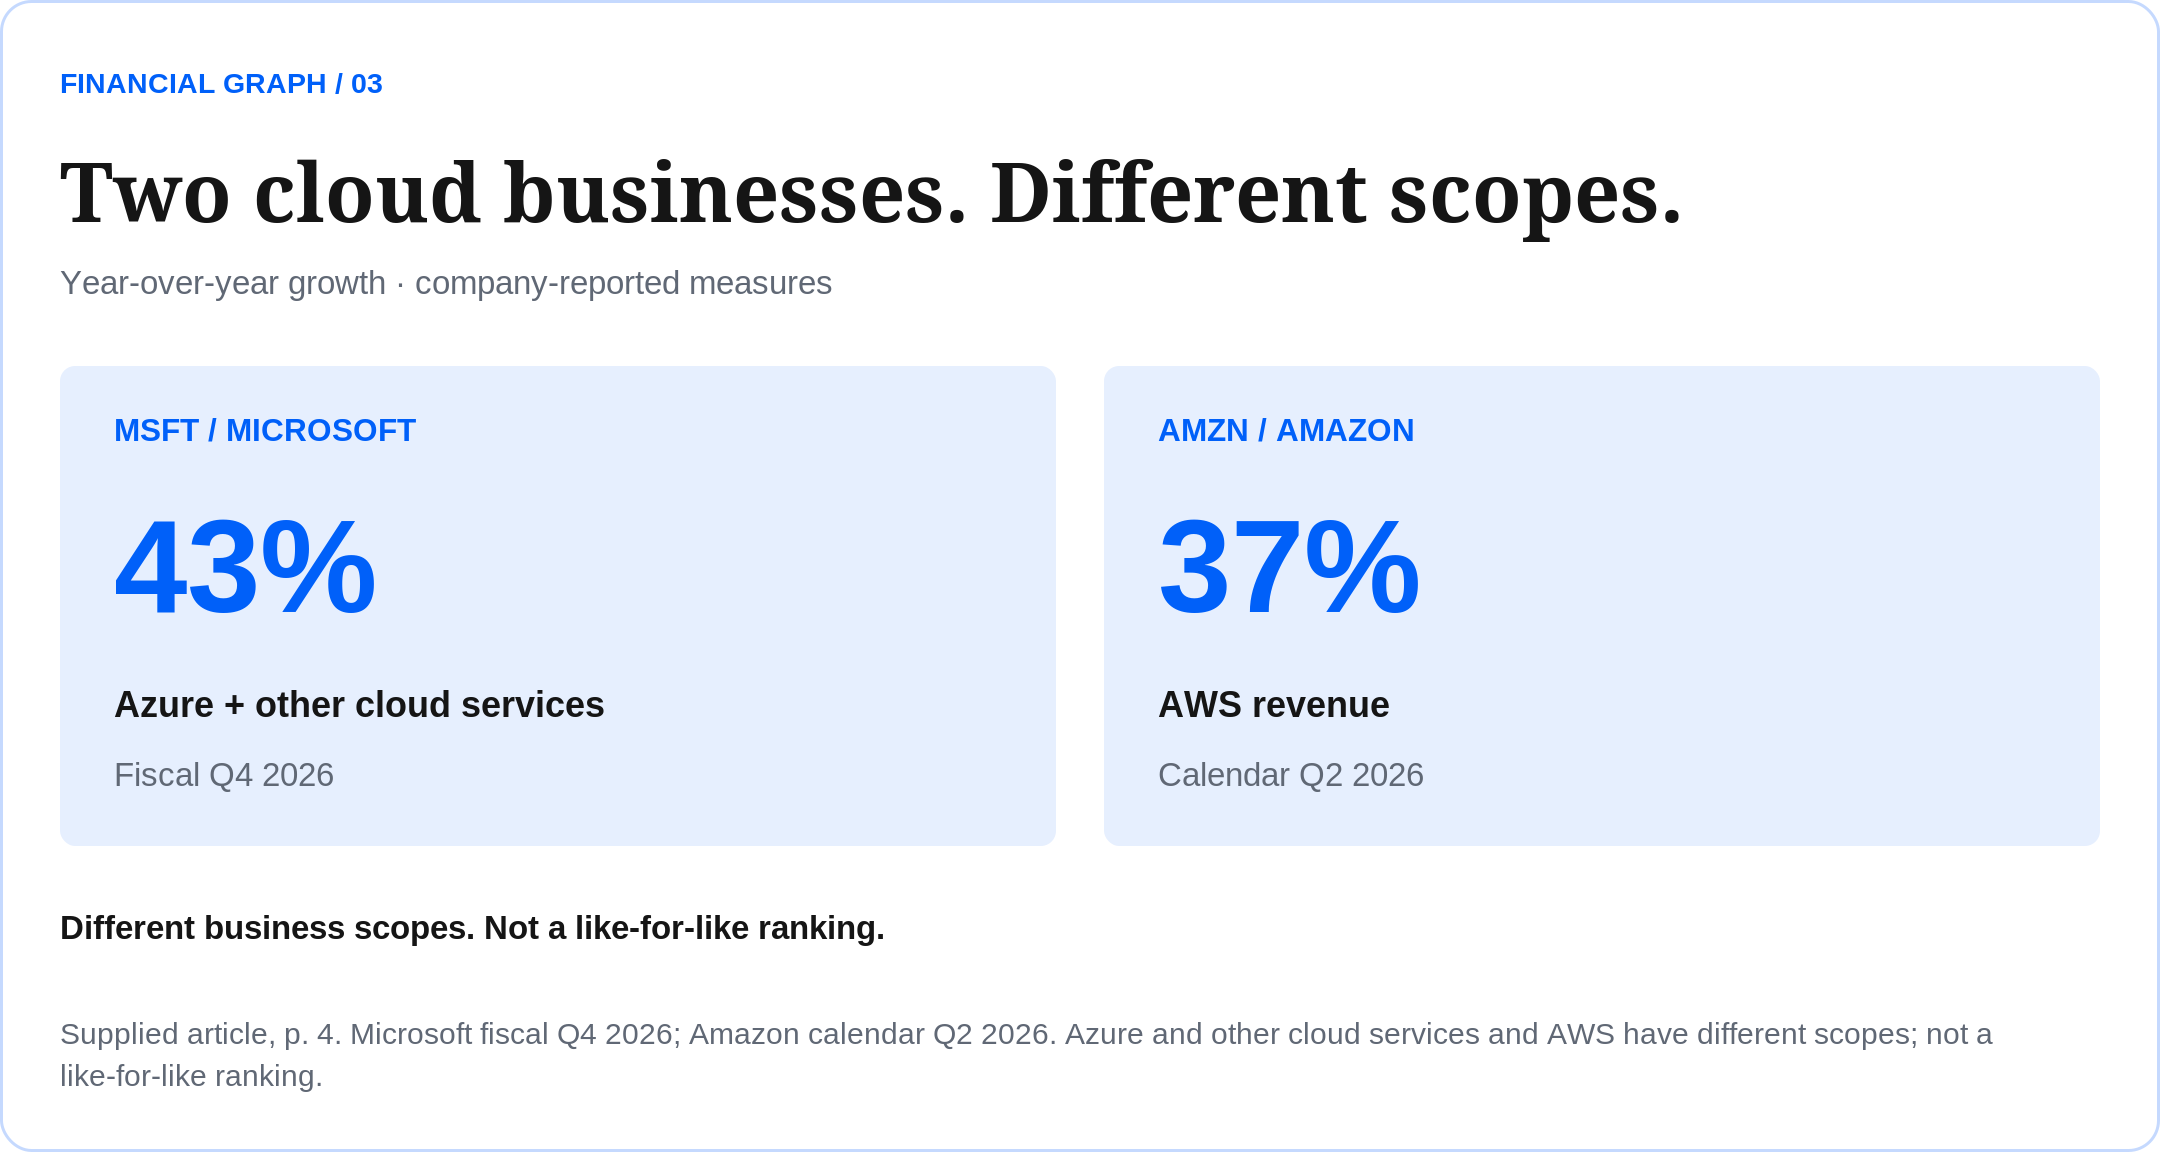
Microsoft: fiscal Q4 2026; Amazon: calendar Q2 2026. Growth is year over year. Amazon cash-flow measures cover 12 months ended June 30. Cloud business scopes differ; these percentages are not a like-for-like ranking.
| Visit TheInvestorCall.com → |
05 / SPECTRAL CAPITAL / OTCQB: FCCN An operating base. |  |
Spectral adds an earlier-stage question to the story: can software and intellectual property improve the economics of an existing business?
21 Acquired utility applications · filed | 19 Internal applications · not yet filed | $5.267M Cash · June 30, 2026 |
THE COMMERCIAL TEST / EDITORIAL FRAMEWORK
Deployment. Customer gains.
Cash generation.
The milestones that would connect development work to shareholder value.
A foundation to build on.
Spectral operates international voice and messaging services through Telvantis Voice Services and 42 Telecom. Management's strategy is to use technology and intellectual property to support and expand its operating businesses.
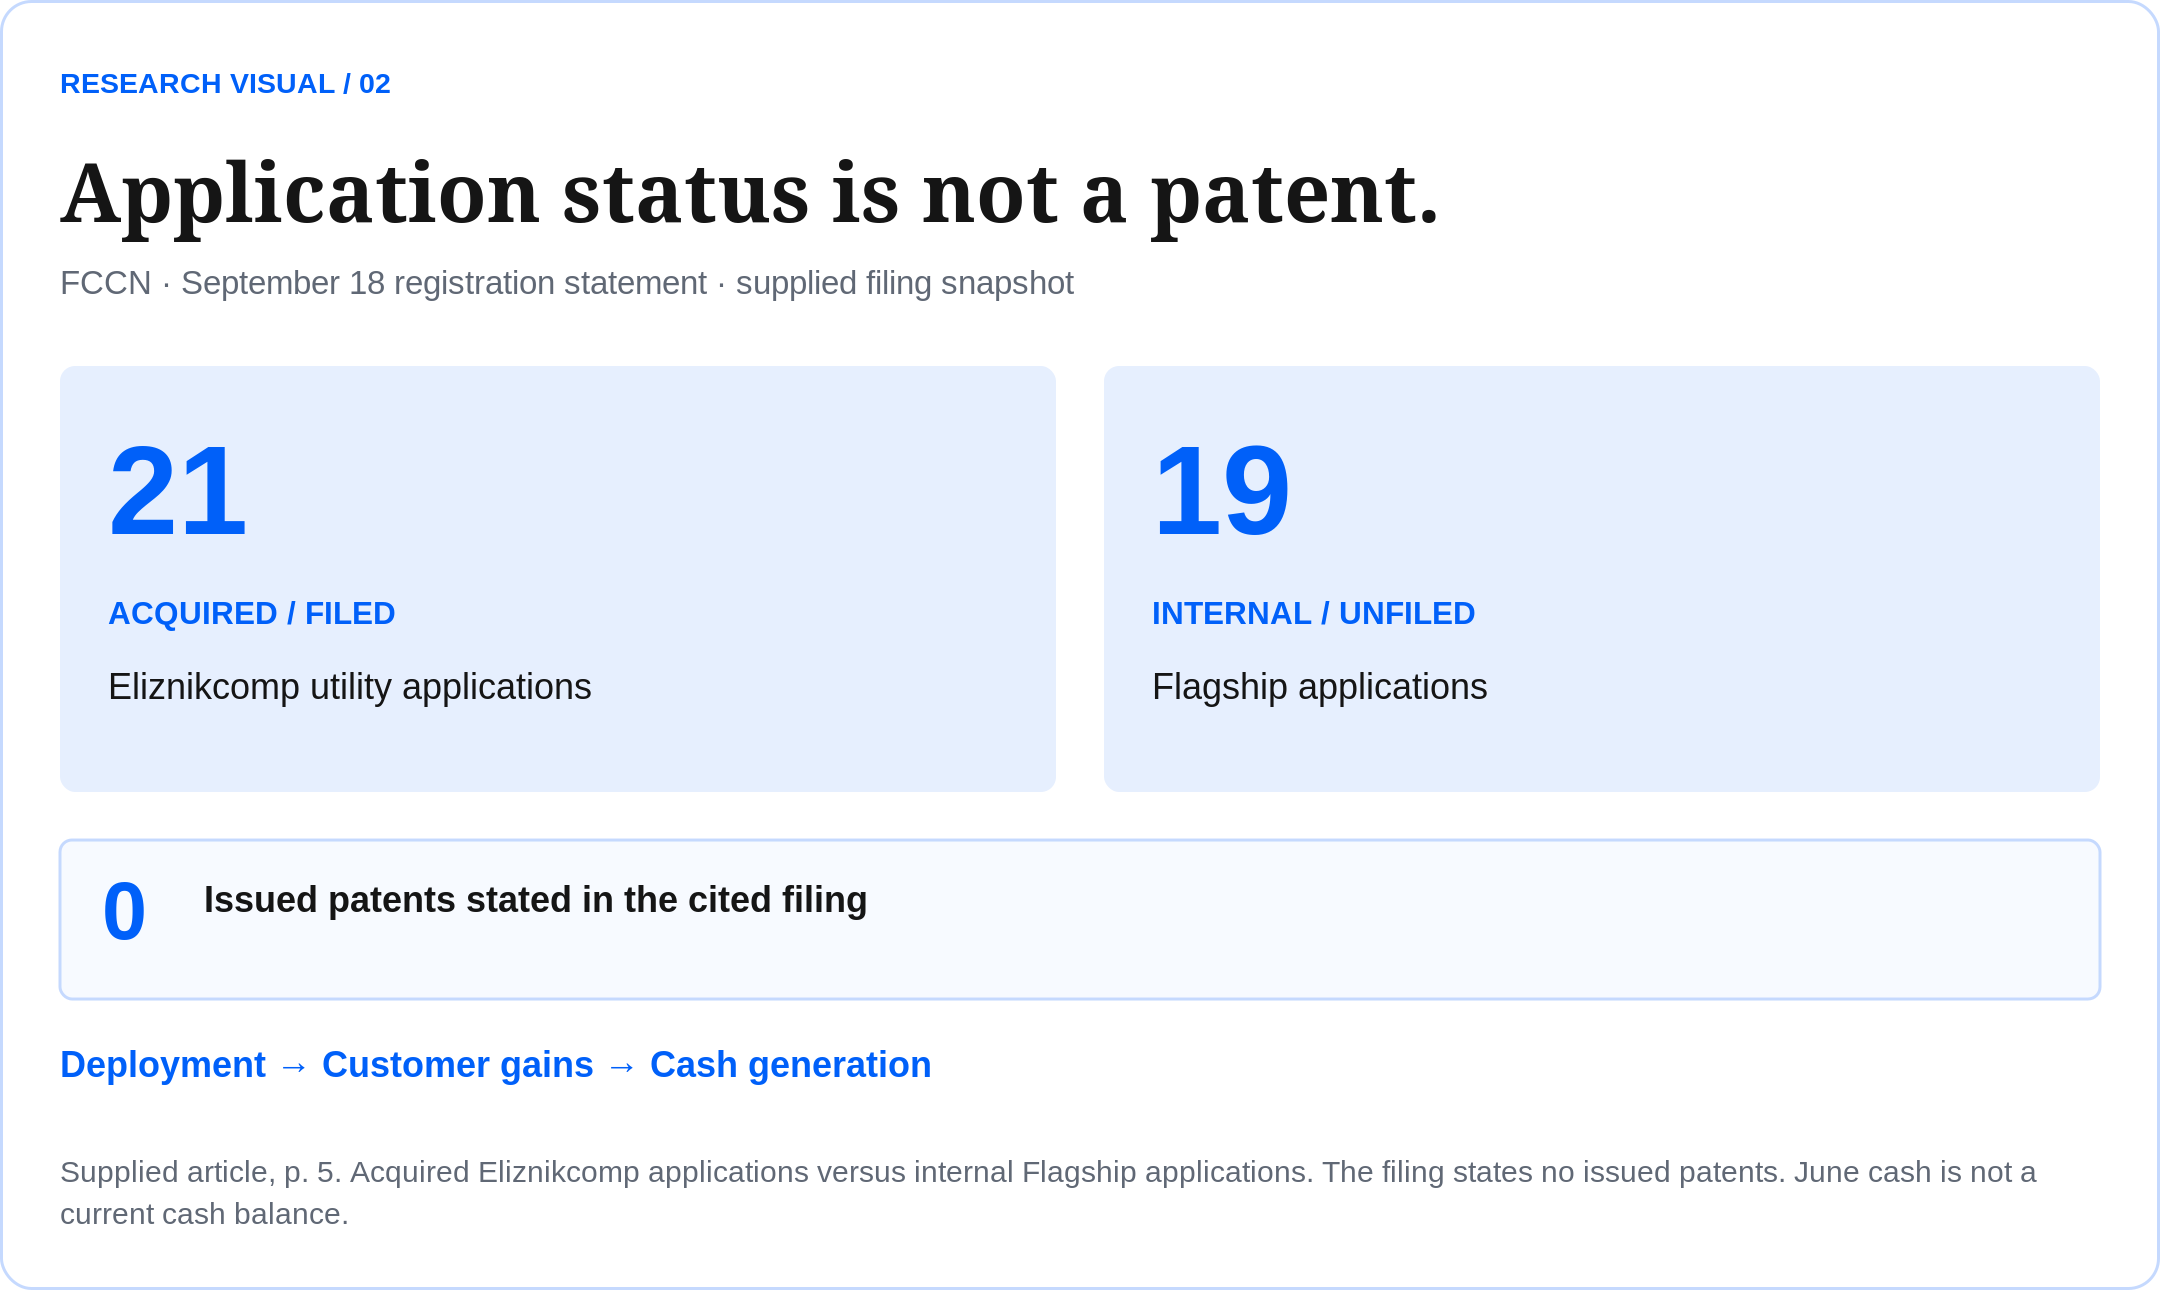
The September 18 registration statement distinguishes 21 acquired, filed Eliznikcomp utility applications from 19 internally developed Flagship applications that had not been filed. It states that the company owns no issued patents.
Current telecom revenue remains telecom revenue. Commercial value from development depends on implementation.
Our investment assessment.
A possible long-term thesis is practical: better routing, resource use or automation could improve a service business. This is our interpretation of the opportunity, rather than proof of realized gains.
FCCN belongs on the earlier-stage research list. Before a position, examine funded execution, customer adoption, margins, financing terms and cash generation. The filing describes proposed financing; proceeds are not cash already received.
If evidence justifies investing, use a smaller, milestone-led allocation. OTC liquidity and execution-stage economics call for appropriate position sizing.
Application status and cash reflect the cited filing, not issued patent rights or a current cash balance. June cash was $5.267M. Proposed financing and development plans remain subject to completion and execution.
06 / THE INVESTOR CALL / FIVE INVESTMENT IDEAS Five tickers. |  |
Our investment shortlist: established earnings, AI infrastructure, enterprise adoption, cloud economics and technology execution.
AAPL | Customer ecosystem Revenue +16%; record active device base. Stance: valuation-led accumulation research. |
NVDA | AI computing infrastructure Revenue +106%; GAAP gross margin 75%. Stance: growth research; test expectations. |
MSFT | Enterprise software + cloud Azure and other cloud services growth of 43%. Stance: priority research; Oct. 28 results. |
AMZN | AWS + commercial platforms AWS revenue +37%; assess cash after spending. Stance: selective additions; Oct. 29 results. |
FCCN | Telecom + technology development Operating base; filed and unfiled applications. Stance: smaller, milestone-led position research. |
Our first research priority is Microsoft, with Apple for ecosystem durability; Amazon and Nvidia require careful investment-cycle valuation. FCCN is a smaller execution-led proposition. These are conditional views, not current-price buy ratings. Buying in stages can align additions with evidence; all five share technology exposure.
EXPLORE YOUR TRADING PLATFORM
| Fidelity | Charles Schwab |
| Interactive Brokers | Tiger Trade |
Availability varies by country, account and permissions. Confirm FCCN OTC access with your broker.
Research the business. Invest with conviction.
Give long-term value time to develop.
| Subscribe now for free | Get in touch with our team |
Production note. Article wording, figures, dates and link destinations are retained from the supplied October 26, 2026 draft. Visuals use only the supplied figures and explicitly labelled arithmetic. Claims have not been independently verified or updated. This presentation does not establish current-price buy ratings or broker eligibility.
| Visit TheInvestorCall.com → |
 Research that matters. Insight you can trust. www.theinvestorcall.com |  |
