Record sales. Higher expectations. The investment picture for Apple, Micron and Spectral Capital. 
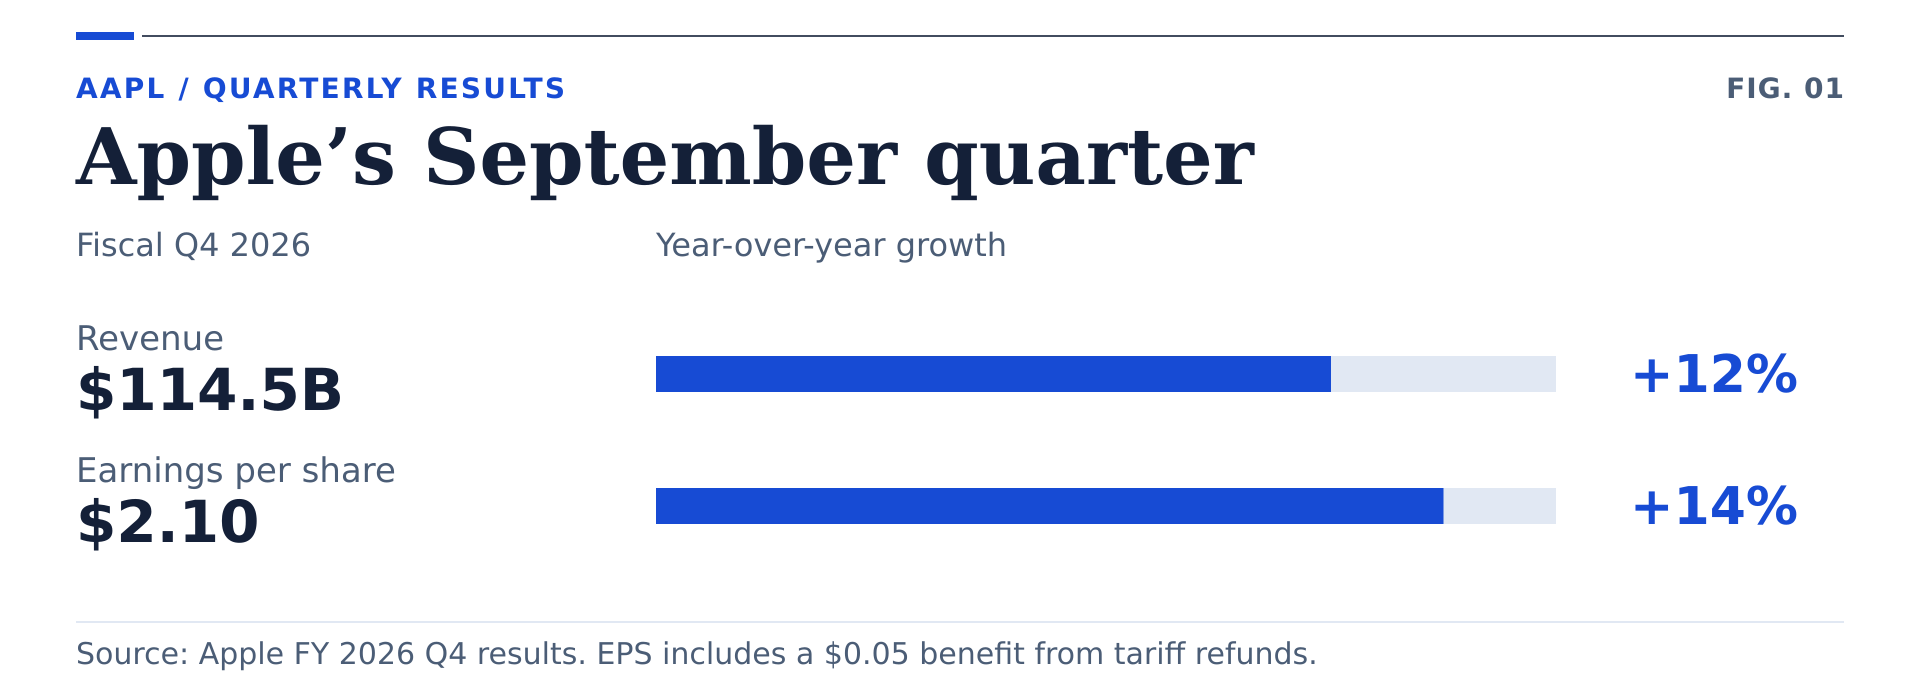 The numbers arrived with force: $114.5 billion in quarterly revenue, up 12%, and earnings of $2.10 per share, up 14%. Apple had given investors a September quarter worth reading. Its iPhone business set a record for the period. Services reached a new high. Cash generation added weight to the story. The customer was still spending; the business was still delivering. Then the conversation moved forward. Investors wanted to know how much profit Apple could retain during the holiday quarter as memory became more expensive. Strong sales had opened the discussion. The outlook would shape the reaction. We follow that question into three investment cases: Apple's demand, Micron's memory economics, and FCCN's operating foundation and technology ambitions. Each deserves a different investment lens. Can Apple keep growing while protecting the profit behind every sale? Research cut-off: November 3, 2026, before the U.S. regular session. USD throughout. Editorial views are distinguished from company reporting; guidance describes expectations, not achieved results.
A strong report starts the conversation. Expectations for future profitability determine what comes next. APPLE / GROSS MARGIN / REPORTED VS. MANAGEMENT GUIDANCE
Common scale: 0%-50%. Q4 includes about 1 percentage point from tariff refunds; the December range is a forecast, not a reported result. 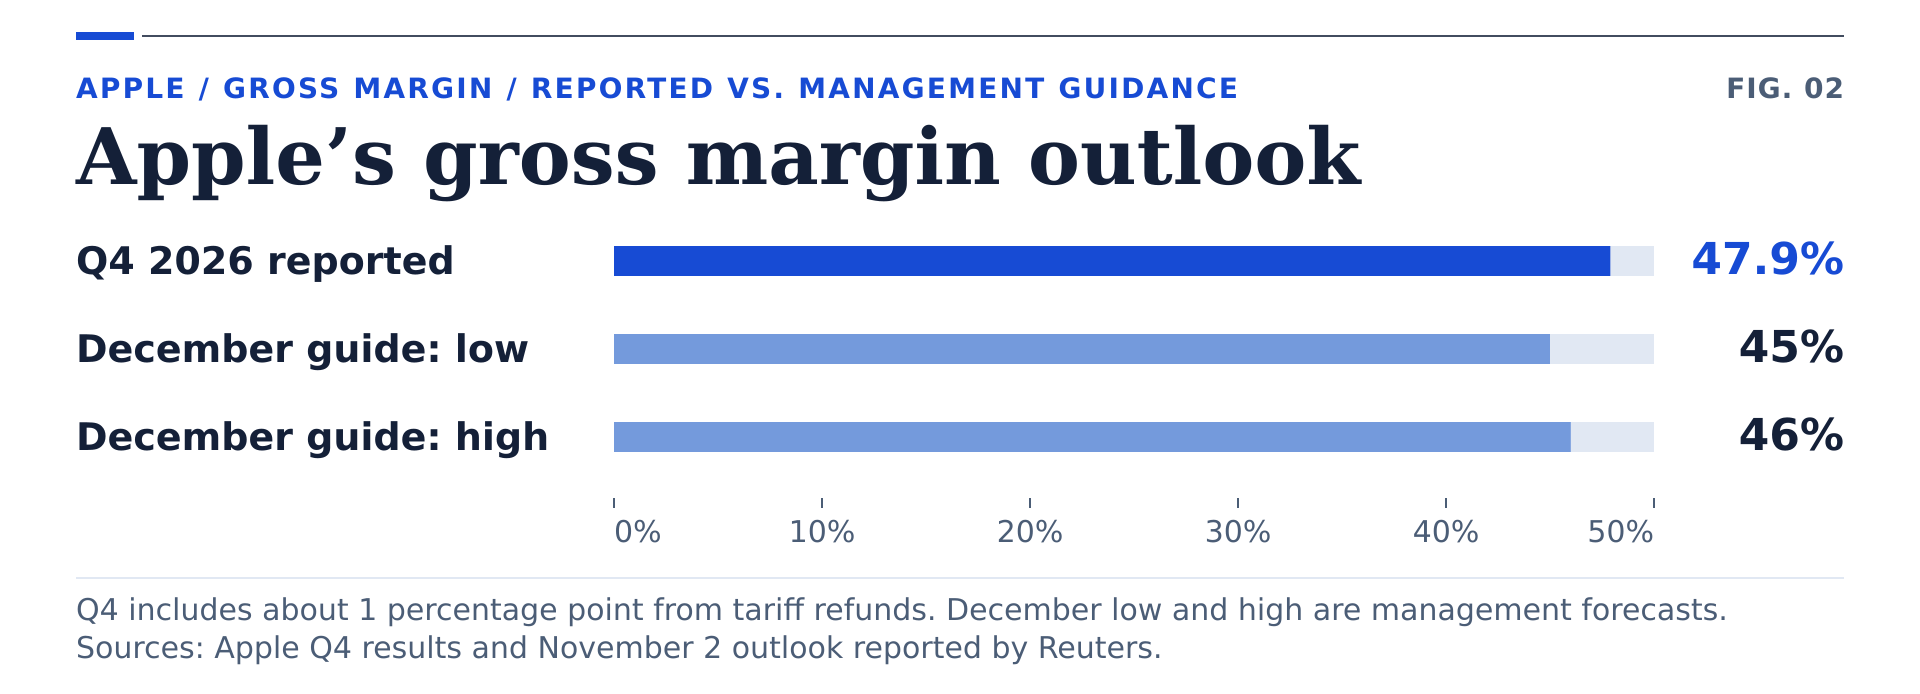 What the market heard Apple outlined a December-quarter gross margin of 45%-46%, versus 47.9% reported for September. Higher memory costs were a central factor. Services growth guidance of 8%-9% also came below the 10.7% analysts expected, according to Reuters. During the November 2 earnings call, the shares fell as much as 4% in after-hours trading before paring the decline to about 2%, Reuters reported. That reaction belongs to the call, not the next regular trading session. Follow each sales dollar Revenue measures customer spending. Gross margin shows what remains after direct costs, before operating expenses and taxes. A company can grow sales while retaining a smaller share of each dollar. Investors therefore need both measures. Our interpretation: the debate is about the quality and durability of future earnings. For this report, strip out the tariff benefit before comparing periods. The next test is whether pricing, product mix and operating execution can absorb more expensive components. September-quarter EPS included $0.05 from tariff refunds. Gross margin is not operating margin. The outlook comparison uses management guidance and analyst estimates reported by Reuters on November 2.
A compelling business still needs an investment price that leaves room for future returns.
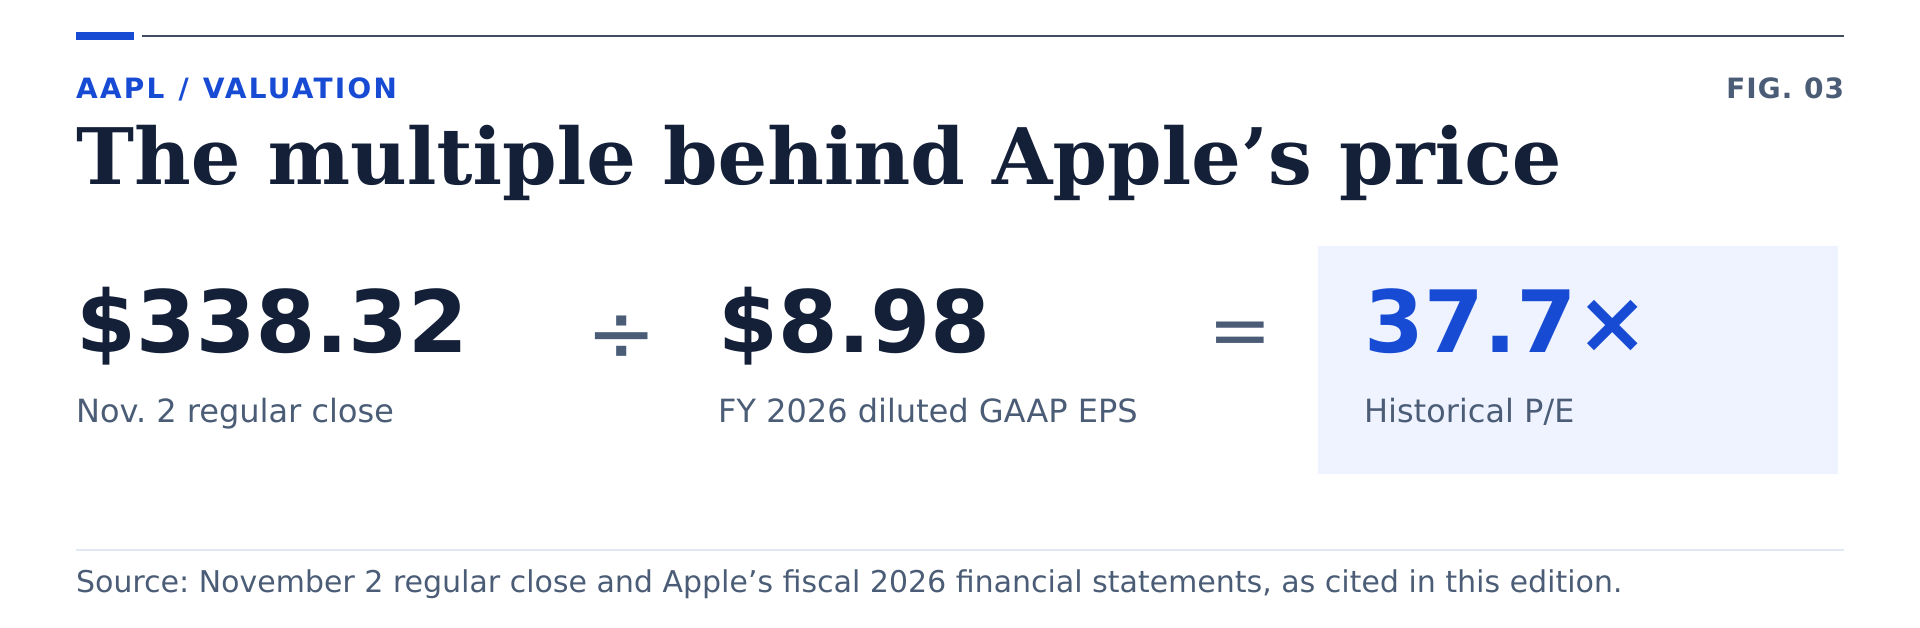 A business built to repeat The strongest long-term argument for Apple is the relationship between devices and the services used on them. A hardware purchase creates opportunities for recurring engagement; the next upgrade can renew the relationship. Customer retention and monetization should be evaluated together. The latest quarter generated roughly $28 billion in operating cash flow. That gives the earnings story a cash anchor. Investors should then follow investment spending and capital returns to see how that operating strength translates into value per share. What the price assumes At $338.32, the shares trade at about 37.7 times fiscal 2026 diluted GAAP EPS of $8.98. That is a trailing full-year comparison, not a forward forecast. A premium multiple makes sustained earnings growth important to the investment case. Separate growth from value A useful valuation exercise starts with reasonable earnings expectations and a range of possible future multiples. Faster growth can support a premium; buying at a demanding price can also reduce the benefit of good business performance. The current multiple should guide position size and patience. The holiday quarter is the next operating catalyst. Watch product demand, the gross-margin outcome and whether recurring Services growth supports overall profitability. Compare those developments with the assumptions behind the purchase price. Our investment view Hold for existing long-term investors. New investors can consider a modest, staged position, adding when valuation or operating evidence improves. Our horizon is three to five years. We favor a disciplined entry over treating an earnings beat as an automatic buying signal. *Indicative value = $338.32 x 14.570195 billion Q4 weighted-average basic shares; this is a proxy, not an exact current share count. P/E = 338.32 / 8.98. Prices exclude after-hours trading. Apple price · FY 2026 financial statements · Apple Investor Relations
When memory becomes more valuable, the economics reach well beyond the device maker.
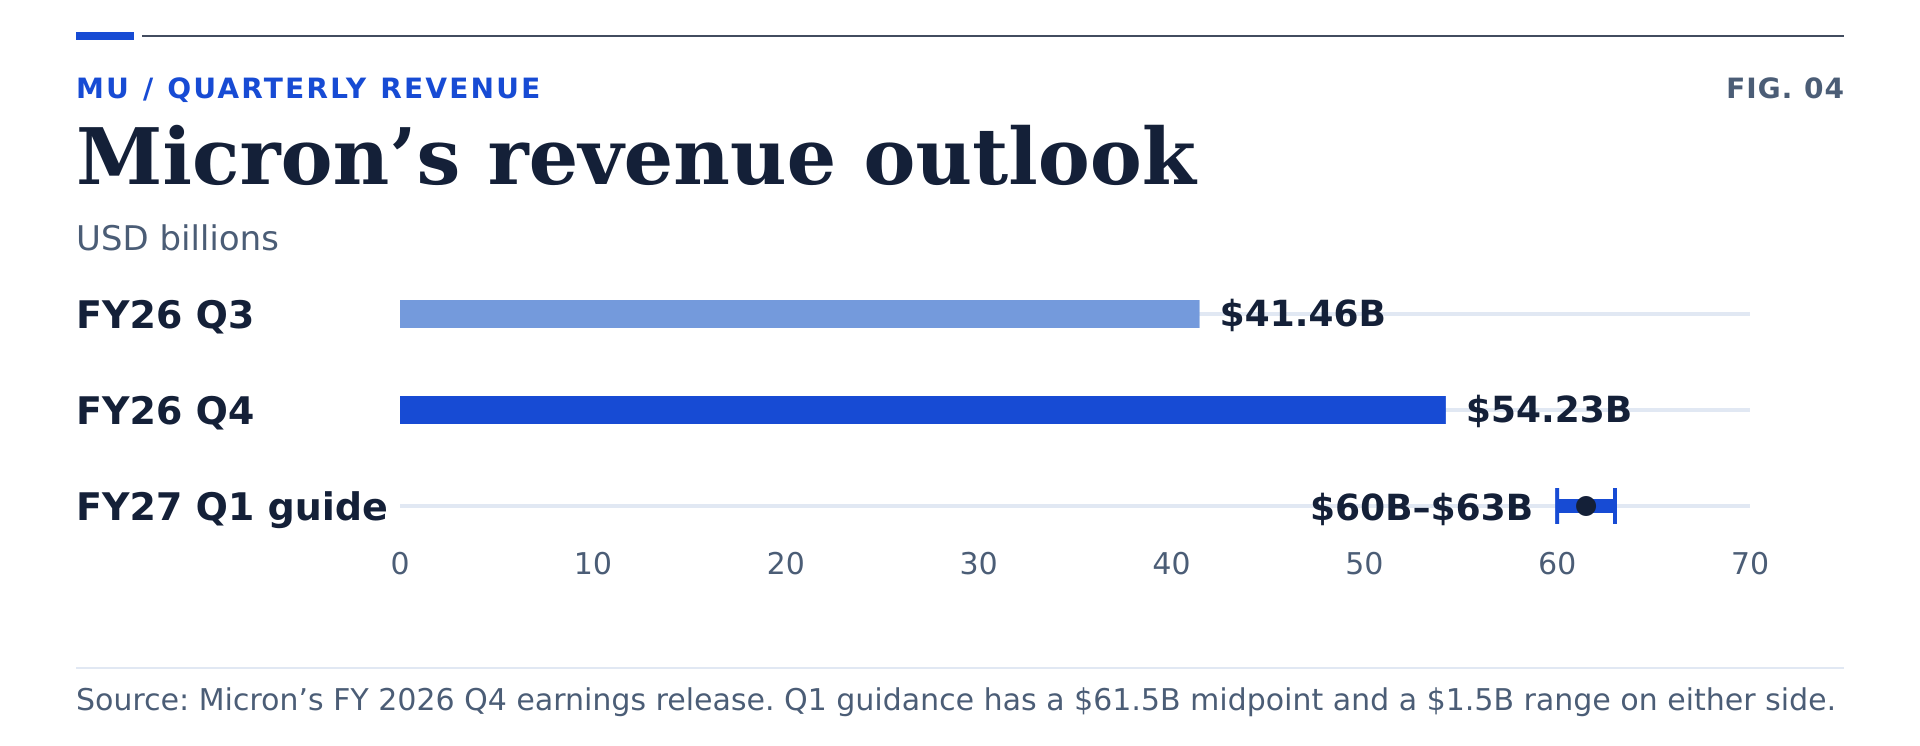 Why memory matters Micron produces memory and storage, including DRAM and NAND. These components help systems hold working data and store information. Smartphones, computers and data centers all depend on them. More demanding workloads can increase the value of memory performance and capacity. The investment connection is economic: higher component prices can lift a supplier's revenue per unit while raising a device manufacturer's bill. This edition makes no claim that Micron supplies a particular Apple product. The latest evidence Micron's fiscal Q4 revenue was $54.23 billion, compared with $41.46 billion in the prior quarter. It reported $32.87 of GAAP diluted EPS. For fiscal Q1 2027, management guided to revenue of $61.5 billion, plus or minus $1.5 billion. The guide is a forecast. Value across the cycle At the November 2 close, the shares traded at roughly 11.2 times fiscal 2026 GAAP diluted EPS of $74.33. That is a historical earnings multiple. It should not be read as proof that the shares are inexpensive: semiconductor profits can move sharply across a supply cycle. New manufacturing capacity takes time and capital. Strong pricing can support expansion, which eventually changes supply. Investors should study demand, capacity additions, customer commitments and cash generation together rather than extrapolating one quarter indefinitely. Our investment view Consider gradual accumulation for a two- to three-year horizon, with a smaller initial position until the next results confirm the outlook. Follow pricing, cash conversion and investment requirements. The opportunity is exposure to memory demand; the entry decision still depends on sustainable earnings. Micron period ended September 3, 2026; results released September 30. GAAP figures unless stated. Historical P/E = $833.59 / $74.33 = 11.2x. Price source: Yahoo Finance, November 2 regular close. Micron Q4 / SEC earnings release · Micron Investor Relations · MU price history
An operating foundation. A technology-driven ambition. A commercial story with room to develop.
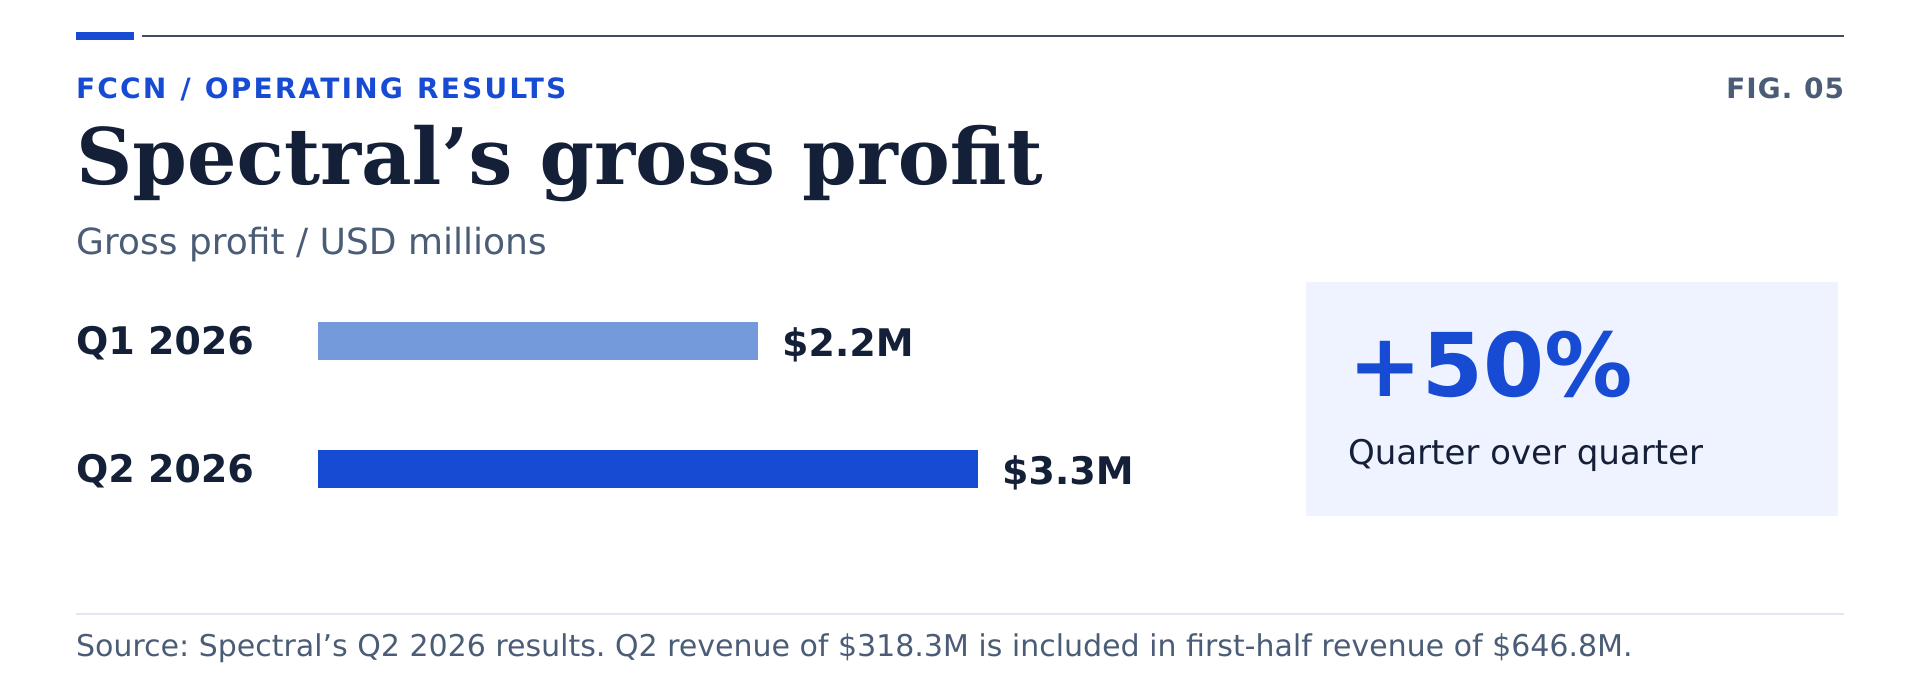 A foundation to build on Spectral operates international voice and messaging businesses through Telvantis Voice Services and 42 Telecom. Its Q2 release describes wholesale voice termination, SMS aggregation and enterprise messaging. These operations give its strategy a real-world setting: networks, traffic and customers. Reported Q2 gross profit reached $3.3 million, compared with $2.2 million in Q1. For readers following the company, that sequential progress offers a concrete measure alongside the scale of its telecommunications revenue. From ambition to application The company says it is evaluating intellectual property for use in its subsidiaries. The opportunity is to connect development work with commercial needs. Successful implementation could improve efficiency, deepen customer relationships and create additional services. These are opportunities to pursue, rather than completed outcomes. The next chapter takes shape Spectral's September 18 prospectus describes an application to list on the Nasdaq Capital Market under FCCN. The September 28 amendment updates exhibits and leaves that prospectus unchanged. The documents reviewed describe an application, not an approved listing; the company website continues to identify OTCQB: FCCN. The most useful milestones are practical: customer implementations, repeat usage and evidence that technology adds commercial value. Following those developments gives a long-term investor a way to connect ambition with business progress. Our investment view FCCN merits a place on an opportunity-focused research watchlist. Study the operating businesses now and build conviction as implementation evidence develops. Our constructive thesis centers on commercial execution: an existing foundation can become a platform for a broader business over time. Company-reported results for the quarter and six months ended June 30, 2026. Technology opportunities are forward-looking editorial scenarios. Research the latest filings through the clickable sources below. Company Q2 results · Sept. 18 prospectus · Sept. 28 amendment
Match the investment decision to the business, its valuation and the next piece of evidence.
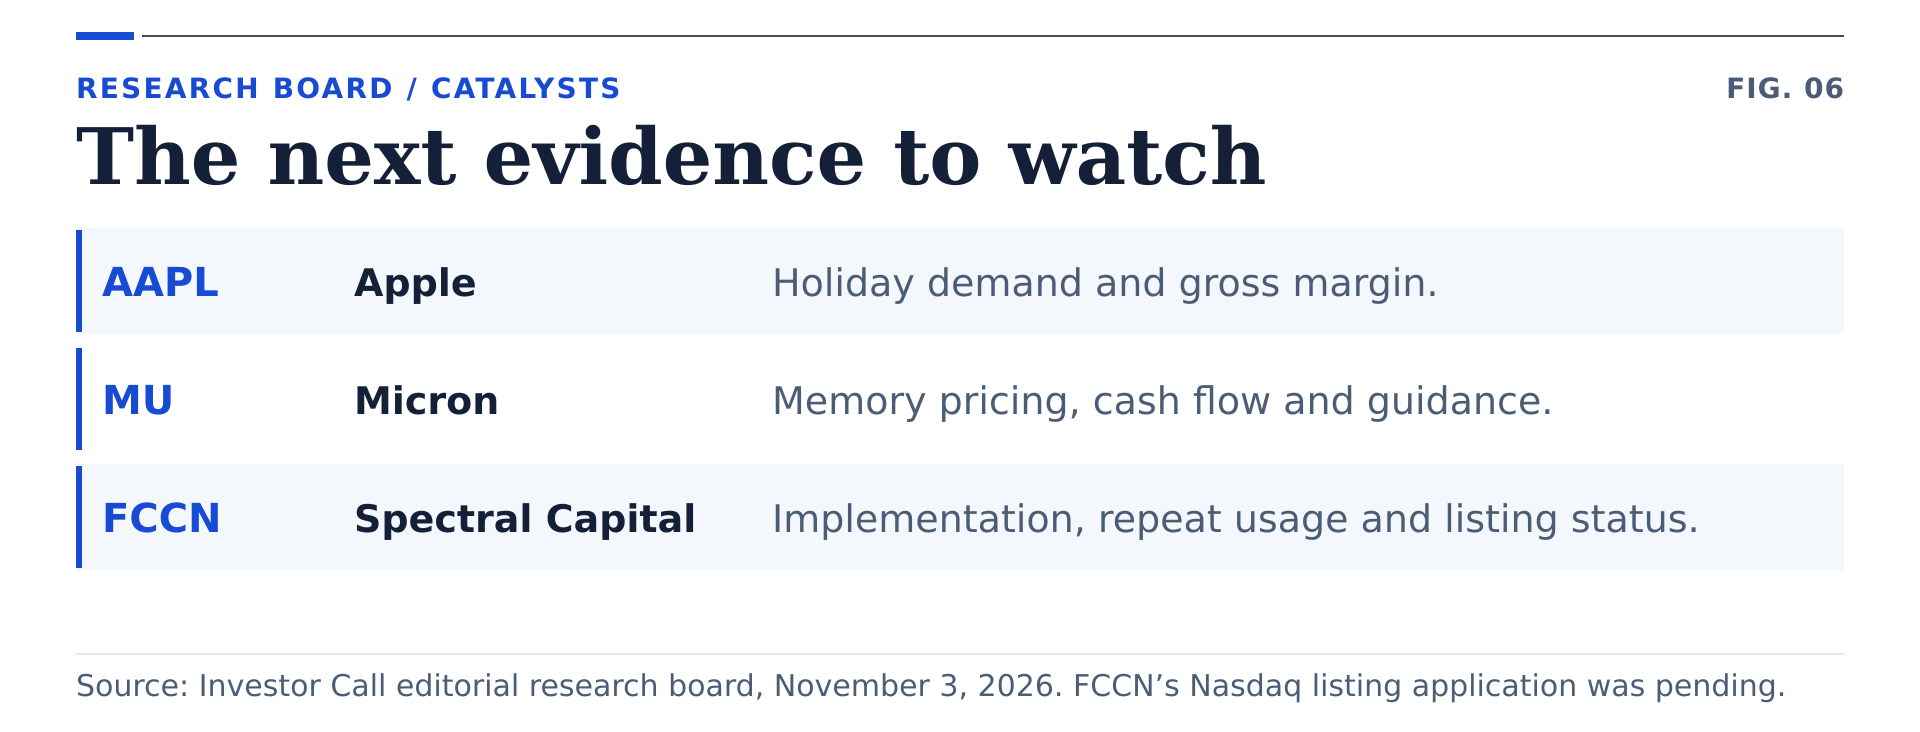 These are different business exposures, not an equal-weight portfolio. Size positions around your investment horizon and the evidence supporting each thesis. Research the business, assess the price and give commercial progress time to develop. EXPLORE TRADING PLATFORMS
Platform and ticker access depend on country, account and permissions. Independent editorial research. Not personalized investment advice. Apple IR · Micron IR · Spectral IR · SEC EDGAR
Research cutoff: November 3, 2026, before the U.S. regular session. Figures, guidance and investment views follow the supplied edition.
|